IRS Payment Plans
IRS Installment Agreement Interest Rate: The True Cost of Paying Over Time (2026)
The short answer: there is no special installment agreement interest rate. Your balance carries the standard federal underpayment rate — the federal short-term rate plus 3 percentage points, reset each quarter and compounded daily (recently around 7–8%). A payment plan doesn't lower that rate; it halves the late-payment penalty, from 0.5% to 0.25% a month.
This guide covers what an IRS installment agreement really costs: the interest rate the balance carries, the penalty a plan cuts in half, how the two stack on a real balance over 72 months, what a default does to the math, and the levers that lower the total. If you searched "installment agreement interest rate" expecting a discounted plan rate, here is the fact that changes everything. The IRS does not offer one. The same underpayment interest applies whether you pay tomorrow or over 72 months. What a plan buys you is a cut to the penalty, and understanding that split is how you figure out what paying over time costs.
So the real question is the total carry: interest plus the reduced penalty, compounded daily, for as long as a balance remains. The image below shows how those two charges stack on a real IRS balance and where each one comes from.
⏱ The clock that never stops: interest compounds daily and the 0.25% monthly failure-to-pay penalty keeps running the entire time you are on the plan. A payment plan stops levies. It does not stop the meter. Every day the balance sits, it grows.
What is the installment agreement interest rate?
The rate on an IRS installment agreement is the federal underpayment rate set under Internal Revenue Code §6621: the federal short-term rate plus 3 percentage points. It applies to individual balances no matter how you are paying them off.
The IRS resets this rate every calendar quarter, so it can move up or down while you pay. In recent quarters it has run in the 7% to 8% range. Check the current quarter's figure in our breakdown of IRS interest rates 2026 quarterly. Because it compounds daily, the effective yearly cost is a touch higher than the posted rate.
Here is the part most articles skip. The interest is only half the cost. Alongside it runs the failure-to-pay penalty. Off a plan, that penalty is 0.5% of the unpaid tax per month. The moment your installment agreement is approved, that penalty drops to 0.25% per month, an automatic discount for getting on a plan. For the mechanics of how interest itself builds day over day, see how IRS interest actually compounds.
| Charge | Rate | How it behaves |
|---|---|---|
| Underpayment interest | Federal short-term rate + 3% (recently ~7–8%) | Reset quarterly; compounds daily; never caps |
| Failure-to-pay penalty — no plan | 0.5% of unpaid tax / month | Caps at 25% of the tax |
| Failure-to-pay penalty — on an approved plan | 0.25% of unpaid tax / month | Halved once the IA is active; still counts toward the 25% cap |
| Combined effective carry (illustrative) | ≈ 10–11% per year | Interest + reduced penalty while the plan runs |
“You can enter into an Installment Agreement to pay the remaining balance. Interest will continue to accrue daily on any amount not paid, including on both penalties and interest.”
— Interest (IRS.gov)
Why are you paying interest at all?
Interest is the price of using money that legally belonged to the Treasury on the original due date. It is neither a penalty nor optional. It starts accruing the day after your return's filing deadline, whether or not you have received a bill, and it runs until the balance hits zero.
That is why a payment plan feels frustrating. You make payments on time, in good standing, and the balance barely moves in the early months. Nothing is wrong. Early on, a large share of each payment covers the interest and penalty that accrued that month, and only the remainder chips at principal, exactly like a mortgage in its first years.
Two transcript codes tell you this is happening on your account. When you pull your account transcript, you will watch these post month after month while you pay.
| Code | What it means | What to do |
|---|---|---|
| 196 | Interest assessed on your balance | Confirm the amount tracks the current quarterly rate; interest is rarely removable |
| 276 | Failure-to-pay penalty posted | Verify it dropped to 0.25%/month after your plan was approved; ask about abatement if it's your first slip |
| 971 | Notice issued (often a plan reminder or rate/adjustment notice) | Read it — a CP521 reminder is routine; a CP523 default warning is urgent |
| 780 | Manual abatement of penalty or interest | Appears if the IRS grants reasonable-cause or §6404 interest relief |
What does a payment plan cost? A worked example
Say you are a W-2 employee filing single and you owe $92,700 after a rough tax year. You can't clear it in one shot, so you look at a long-term installment agreement. Because this balance is above $50,000, expect to provide financials on Form 433-F or set up direct debit. Details are in our guide to an IRS payment plan over $50,000. Here is the arithmetic on the carry, using an illustrative 8% interest rate.
- Month one interest: $92,700 × 8% ÷ 12 ≈ $618.
- Month one reduced penalty: $92,700 × 0.25% ≈ $232.
So before you touch a dollar of principal, month one costs about $850 in interest and penalty. If your monthly payment is roughly $1,765 (what it takes to amortize this balance over 72 months at that combined carry), only about $915 of that first payment reduces what you owe.
Over the full 72-month term at those assumptions, you would pay in the neighborhood of $127,000 total, meaning roughly $34,000 of interest and penalty on top of the $92,700. That is the true cost of paying over time, and it is why every dollar paid early matters. Want to model your own numbers? Estimate the running total with our IRS penalty & interest calculator.
Note the penalty side has a ceiling the interest does not. The failure-to-pay penalty stops once it reaches 25% of the original tax. On $92,700 of tax, that cap is about $23,175, after which only interest keeps compounding. Interest itself never caps.
What happens if you let the plan lapse?
Defaulting on an installment agreement restarts collection and flips your reduced penalty back to full price. The consequences arrive in a set sequence:
- You miss a payment. There is a short cure window before the plan formally defaults. Act inside it and you can usually avoid everything below. See what happens when you miss an IRS payment plan payment.
- CP523 issues. The IRS notifies you the agreement is defaulted or about to terminate. The 0.25% penalty reverts to 0.5% per month on the remaining balance.
- Collection resumes. With the plan gone, the IRS can move to levy your wages or bank account and file or maintain a federal tax lien.
- Costs compound faster. Interest keeps running daily, and the penalty is back to full rate. You may owe a reinstatement fee to restart, covered in reinstate your IRS payment plan.
In 2026 this matters more than usual. IRS staffing is down sharply, and installment agreements, defaults, and levies are handled by automated systems that never slowed down. The machine keeps charging and escalating whether or not a human ever reviews your file.
Worried a payment plan will cost more than you can carry?
Interest compounds daily and the penalty keeps running the whole time, so the plan structure you choose changes what you pay by thousands. An experienced tax professional will map your real carrying cost and the cheapest path out, free and confidential.
How can you lower the interest cost?
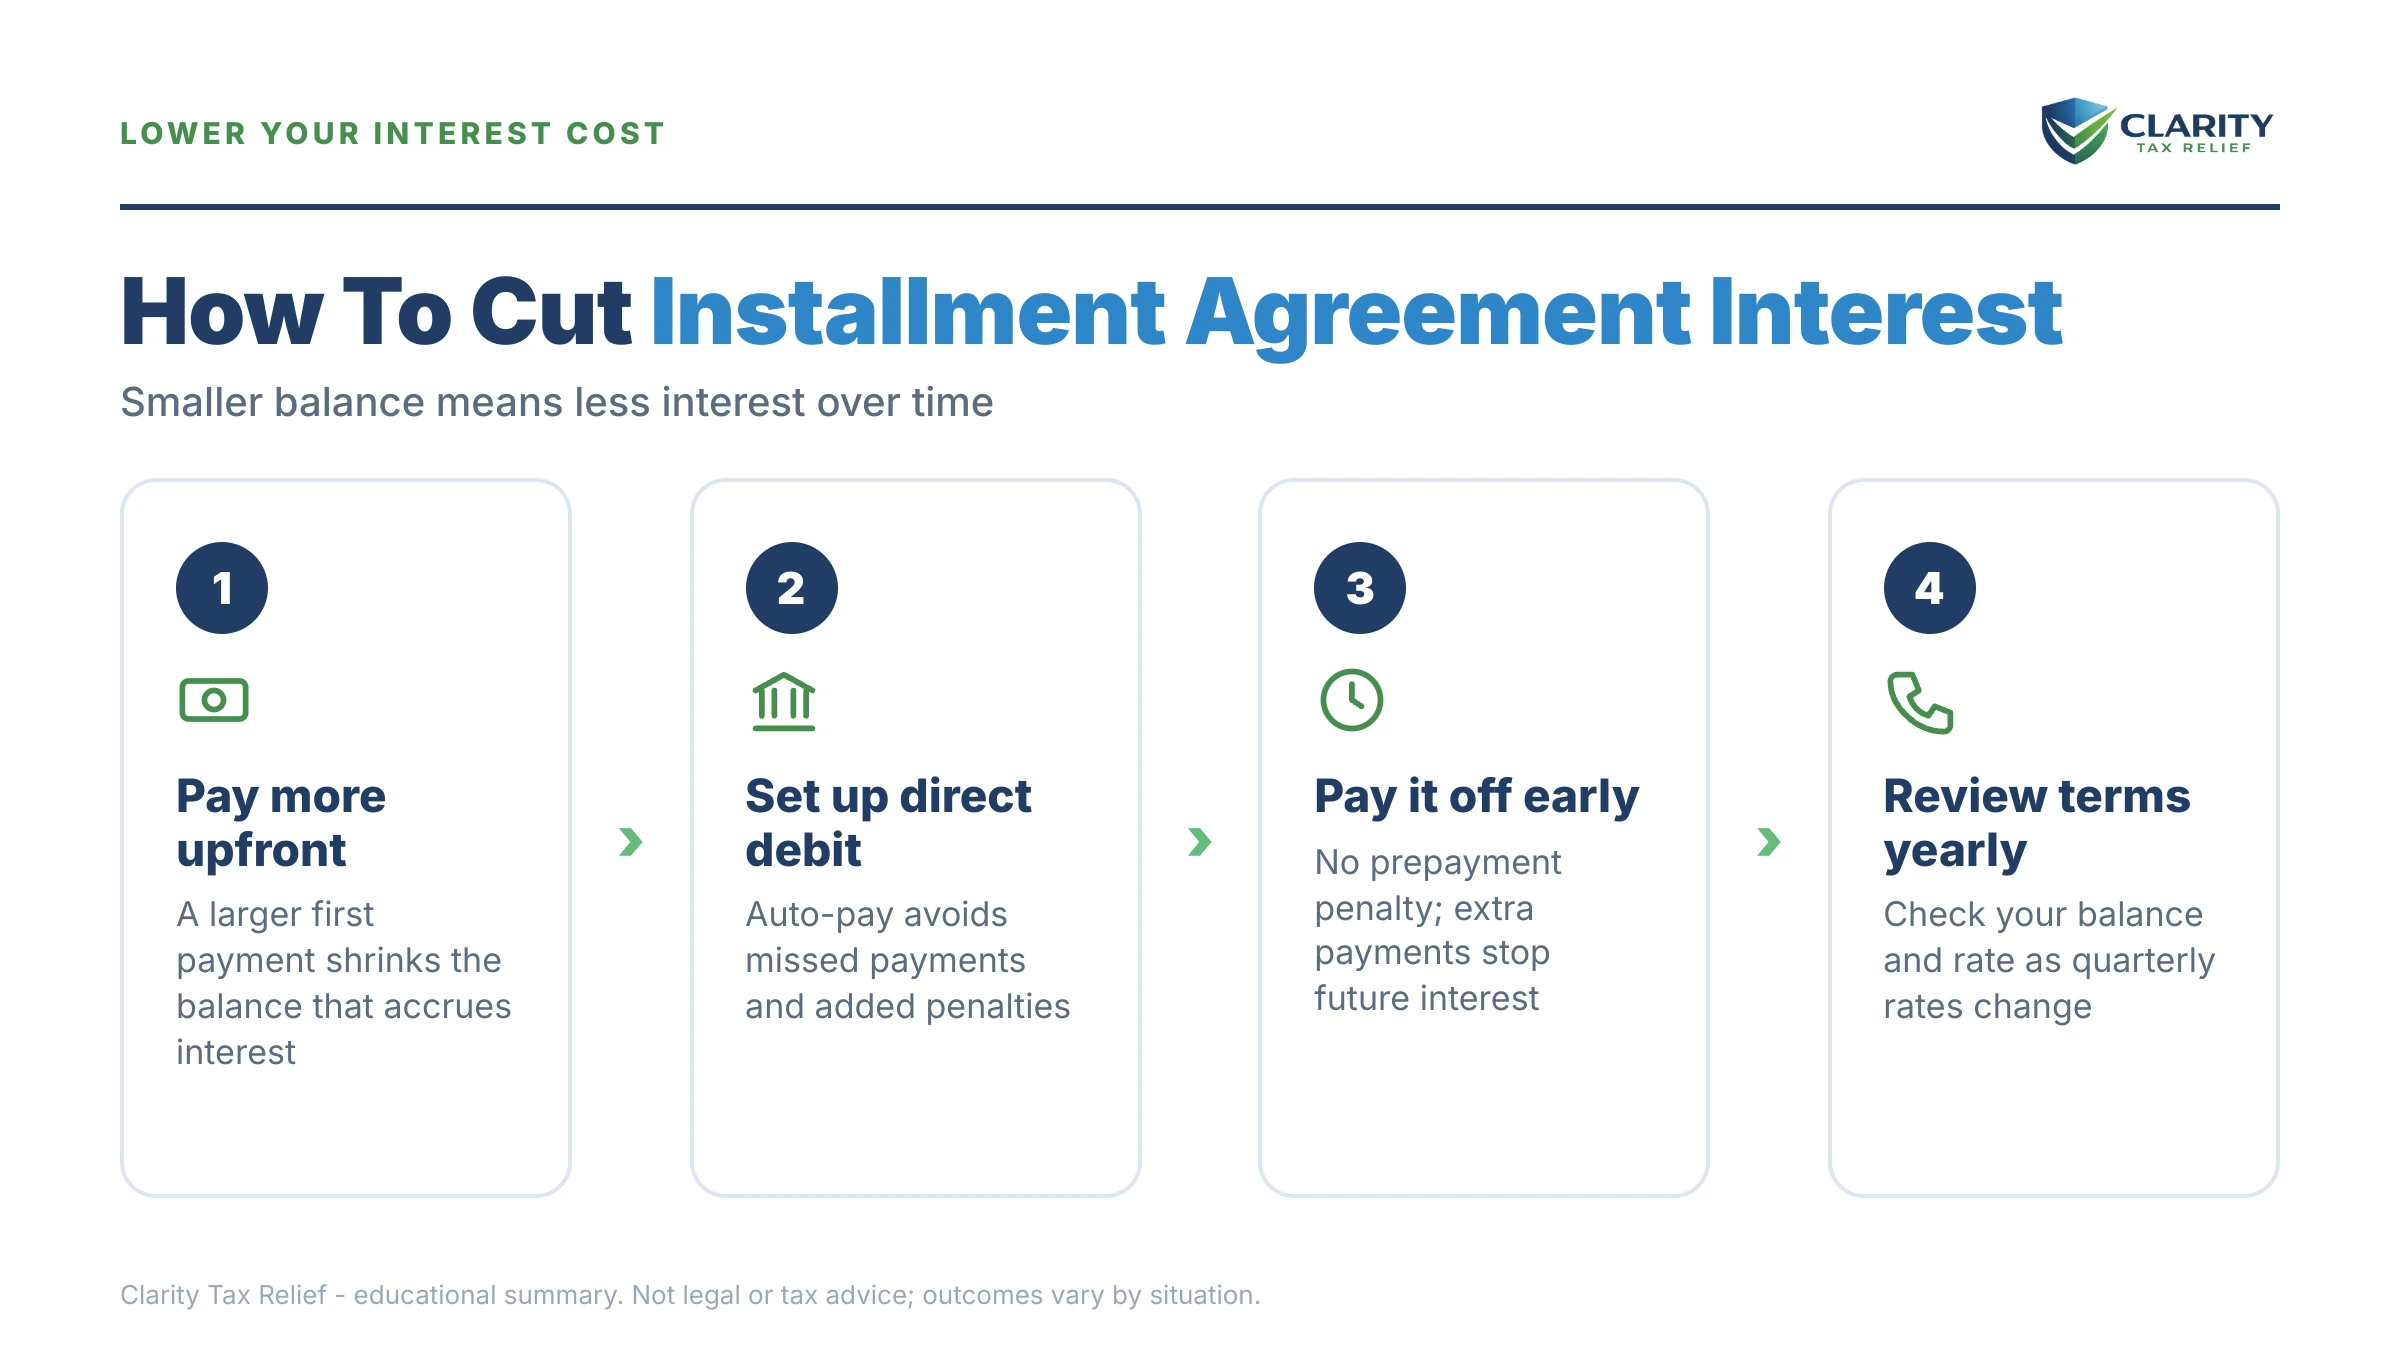
You can't negotiate the interest rate. It is fixed by statute. You can shrink the amount interest is charged on and how long it runs, and those are the levers that move the total.
| Option | What it does to your cost | Best when |
|---|---|---|
| Larger down payment before setup | Cuts the principal interest compounds on from day one | You have some cash but not the full balance |
| Shorter term / higher monthly payment | Less time accruing = far less total interest | Your budget can carry a bigger payment |
| Direct debit installment agreement | Lower setup fee; no rate change, but avoids default costs | You want the cheapest setup and steady payments |
| Pay off the plan early | No prepayment penalty; stops all future interest instantly | You get a bonus, refund, or windfall mid-plan |
| First-time or reasonable-cause penalty relief | Removes the penalty portion (not the interest) | Clean prior 3 years, or a genuine hardship |
| §6404 interest abatement | Removes interest tied to IRS error/delay only | The IRS caused an unreasonable delay |
The interest itself is nearly untouchable. See whether IRS interest can be waived and the narrow path in IRS interest abatement for IRS error. The penalty is a different story. Because a plan already halves it, stacking first-time abatement on top can remove the penalty piece entirely. If a smaller monthly payment is what you need, look at lowering your IRS monthly payment, and remember a longer term means more total interest.
For the full setup walkthrough (eligibility tiers, forms, and how to apply), start with our hub on how to set up an IRS payment plan online, step by step. If your balance is under the streamlined ceiling, the streamlined installment agreement route skips the financial disclosure. And if you want to know what fees ride on top, the IRS payment plan setup fee guide breaks down every tier and waiver.
How to minimize what your installment agreement costs, step by step
- Confirm your current quarterly rate so you know what is compounding on your balance today.
- Pay down as much principal as you can before setup. Interest is charged only on what remains.
- Choose the shortest term your budget survives. A higher monthly payment means far less total interest.
- Enroll in direct debit to lower the setup fee and remove the risk of a costly default.
- Ask about penalty abatement. A plan already halves the penalty. First-time relief can remove it.
- Throw windfalls at the balance. There is no prepayment penalty, so every extra dollar stops future interest instantly.
Red flags to check on your plan
- Code 276 still posting at 0.5% after approval. The penalty should have dropped to 0.25% per month once the plan was active. Ask about it.
- A balance that is not shrinking. Early-month payments mostly cover interest and penalty. If the principal never moves, the payment is too small for the carry.
- A CP523 in the mail. That is a default warning, and the penalty reverts to full rate when the plan terminates.
- A plan with no direct debit on a balance above $50,000. You may be paying a higher setup fee and carrying more default risk than you need to.
- Anyone offering to negotiate your interest rate. The rate is set by statute. Nobody can lower it.
- Paying a fee to request First-Time Abate you may qualify for on your own. A plan already halves the penalty, and the request itself is free.
Can you handle this yourself?
If your balance is modest and you agree with it, and you can pay it off within 180 days or a short streamlined plan, you do not need anyone. Set up the plan at IRS.gov, choose direct debit, pay more than the minimum, and you will carry the interest cheaply on your own. The math in this article is all you need.
Experienced help changes the outcome when the carrying cost is the real problem. On a $92,700 balance stretched over years, the interest-and-penalty carry runs into the tens of thousands, and the gap between a well-structured plan, penalty abatement, and a completely different resolution can be enormous. If you have a payment plan versus an offer in compromise decision to make, multiple years involved, or a balance where the interest is outrunning your payments, a professional review before you sign is worth far more than it costs. Curious how common each path is? Our IRS installment agreement statistics put your situation in context.
Terms on your notice, decoded
- Underpayment rate: the interest rate the IRS charges on unpaid tax. The federal short-term rate plus 3 percentage points, set each quarter.
- Federal short-term rate: a benchmark rate tied to short-term Treasury yields. The base the IRS adds 3 points to.
- Daily compounding: interest added to your balance every day, so the next day's interest is calculated on the slightly larger amount.
- Failure-to-pay penalty: a separate 0.5%-per-month charge (0.25% once you are on a plan) that caps at 25% of the tax.
- CSED: the Collection Statute Expiration Date, generally 10 years from assessment, after which the IRS can no longer collect. Being on a plan keeps interest running until then or until you pay.
The bottom line
There is no special plan rate. Your balance carries the federal short-term rate plus 3 points, reset each quarter and compounded daily, for as long as anything is owed. A plan halves the failure-to-pay penalty to 0.25% per month and holds levies off, and that is all it does to the meter. The total you pay is decided by how much principal you clear up front, how short a term you can carry, whether you enroll in direct debit, and whether you ask for the penalty relief a plan already sets you up for. Every extra dollar paid early stops interest you would otherwise owe.
Installment agreement interest rate questions, answered
What is the interest rate on an IRS installment agreement?
There is no special installment-agreement interest rate. Your balance carries the standard federal underpayment rate — the federal short-term rate plus 3 percentage points — which the IRS resets every calendar quarter and compounds daily. In recent quarters that has run in the 7–8% range. Being on a payment plan does not lower this rate; it only reduces the separate late-payment penalty.
Does an installment agreement lower my interest rate?
No. The interest rate is set by statute and applies whether or not you have a plan. What a plan does change is the failure-to-pay penalty — once an installment agreement is approved, that penalty is cut in half, from 0.5% of the unpaid tax per month to 0.25% per month. So a plan lowers your total carrying cost, but through the penalty, not the interest rate.
Is IRS installment agreement interest tax deductible?
For personal income tax, no — interest on individual federal tax debt is nondeductible personal interest. Businesses can generally deduct interest paid on business tax liabilities as a business expense. If your balance mixes personal and business tax, only the business portion's interest is deductible, so keep the two liabilities separate.
How is interest on an IRS payment plan compounded?
Interest on federal tax debt compounds daily, not monthly or annually. Every day your unpaid balance sits, that day's interest is added to the principal. The next day's interest is calculated on the slightly larger amount. Because of daily compounding, the effective annual cost is a little higher than the stated quarterly rate suggests.
Can I avoid interest on an IRS installment agreement?
Almost never — interest is statutory and the IRS rarely removes it. The main exception is interest caused by an unreasonable IRS error or delay, which can be abated under Internal Revenue Code §6404. The most reliable way to reduce interest is to pay the balance down faster, since interest is charged only on what's still unpaid.
Is an IRS payment plan cheaper than a credit card?
Usually, yes. An installment agreement's combined interest and reduced 0.25% monthly penalty typically works out to roughly 10–11% per year, while most credit cards charge 20% or more. The catch is that IRS balances can trigger a tax lien, which a credit card won't. For most people the IRS plan is the cheaper carry, but the right choice depends on the balance and your credit terms.
Does the interest rate change during my payment plan?
Yes. The IRS sets the underpayment rate every quarter based on the federal short-term rate, so the rate applied to your balance can rise or fall while you're paying. Your monthly payment usually stays the same. But a higher rate means more of each payment goes to interest and less to principal, which can stretch out how long you pay.
Can I pay off my installment agreement early to save interest?
Yes, and there is no prepayment penalty. Because interest and the 0.25% monthly penalty are charged only on the remaining balance, every extra dollar you pay stops future interest on that dollar immediately. Making a large lump-sum payment or paying more than the required monthly amount is the single most effective way to cut your total cost.
Does interest keep accruing while I'm on the plan?
Yes — interest keeps compounding daily the entire time you owe a balance, even with a plan in perfect standing. A payment plan stops enforcement like levies and garnishments; it does not stop the meter. That's why the total you pay over 72 months is meaningfully more than the amount printed on your original notice.
Your next 24 hours
- Find your current balance and the interest already charged. Pull your IRS account transcript and look for the code 196 (interest) and 276 (penalty) lines so you know what's compounding today.
- Gather your last return, any plan notice. Your monthly budget number. The payment you can afford decides your term. The term decides your total interest.
- Get a free case review. Use the 2-minute form or call (888) 825-7779. Because interest compounds daily and the penalty runs every month, the sooner your plan is structured right, the less you pay.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.
Primary sources: Interest