Back Taxes & Collections
Do I Owe the IRS If I Never Got a Notice? How to Check in 2026
The short answer: yes. You can owe the IRS even if you never got a notice. A tax debt starts the moment the IRS assesses it, not when a letter lands in your mailbox. Penalties and interest keep building whether or not the mail ever reached you. Log into your IRS online account to see your real balance for every year.
What this guide covers: whether you can owe the IRS when no letter ever reached you, why that happens, how to check your own account in about fifteen minutes, what an unseen balance costs while it sits, and what to do once you confirm the number.
Maybe a friend got a letter. Maybe a refund got held. Maybe you moved and lost track. Nothing arrived with "IRS" in the corner, so part of you hopes that means you are clear. It usually does not.
The IRS mails to your last known address, the one on your most recent filed return. Legally, that mailing counts as notice whether or not you ever saw it. The debt and its deadlines run on the IRS calendar, so the person who "never got a notice" can be the one a levy surprises. You can pull the whole picture quickly, and every option stays on the table once you do.
⏱ The clock you can't see: no envelope is setting your deadline here, but the failure-to-pay penalty (0.5% of the unpaid tax per month, up to 25%) and daily-compounding interest accrue from the original due date regardless of whether you got a notice. The 10-year collection clock also runs quietly in the background. The sooner you confirm the balance, the less it grows.
Can you owe the IRS if you never got a notice?
Yes. A tax debt comes into existence at assessment. When the IRS records that you owe, after processing your return, adjusting it, or filing one for you, the balance exists from that point. The notice is the IRS telling you it happened.
Think of a credit card statement lost in the mail. The charge is still real. You still owe it. The interest did not pause because the envelope went to the wrong house. The IRS works the same way, and its collection tools reach much further than a bank's.
So "I never got a notice" does nothing to the balance itself. It can matter for certain Collection Due Process appeal rights and for penalty relief. The underlying tax stays.
Why didn't you get the IRS notice?
The most common reason is a stale address on file. The IRS is allowed to mail to your last known address, so if that address is out of date, the letters piled up somewhere you no longer live. These are the situations that create a balance you never saw.
| Reason | What happened | What it means |
|---|---|---|
| You moved | Notices went to your last filed address; you didn't file since or submit Form 8822 | The debt and deadlines are all valid. You just weren't there to read them |
| The IRS filed for you | A substitute for return (SFR) created a balance with no deductions | The number is usually inflated; filing your own return often lowers it |
| A return you filed was adjusted | Math error, CP2000 underreporter change, or exam adjustment | You may owe more than your return said — check the tax-year balance |
| Identity theft | Someone filed or opened an account in your name | File Form 14039; the balance may not be yours at all |
| Mail delay or lost letter | The notice was mailed but never arrived | Delivery still counts as legal notice under the last known address rule |
If you suspect a letter never reached you, our guide on why the IRS sends letters and the one on what a certified letter from the IRS means both explain which notices carry legal weight even when undelivered.
How do you find out if you owe the IRS?
The fastest and most reliable way is your IRS online account. It shows your balance by year, your payment history, and every notice the IRS has issued to you. There is no need to wait for mail.
| Method | What it shows | Speed |
|---|---|---|
| IRS online account | Current balance by year, payments, notices issued | Instant once ID is verified |
| Account transcript | Assessment date, each penalty and interest charge, adjustments | Instant online; ~5–10 days by mail |
| Wage & income transcript | Every W-2 and 1099 the IRS received (catches unfiled-year debt) | Same day online |
| Calling the IRS | Balance and status by phone (long waits in 2026) | Slow — staffing is down sharply |
If identity verification blocks you online, order transcripts by mail (allow 5 to 10 days) or read our walkthrough on getting your transcripts online. The account transcript is the one that shows the assessment date, which is the date each year's 10-year collection clock starts running.
Red flags to look for once you are in:
- A balance for a year you never filed. That usually means a substitute for return, and the number is likely inflated.
- W-2 or 1099 income on the wage and income transcript that you do not recognize. That can point to identity theft, which calls for Form 14039.
- A balance higher than the return you filed. Look for a math error, CP2000 change, or exam adjustment on the transcript.
- A CP504 or LT11 already listed under notices issued. Enforcement may be close or already under way.
- An address on file that is years out of date. Every future letter will go there too until you fix it.
What happens if you never respond, even to a notice you never saw?
The IRS collection sequence is automated. It does not wait for you to open your mail. Every notice below was mailed to your last known address; if you were not there, the sequence kept going.
- Assessment. The balance posts to your account. Penalties and interest start growing from the original due date.
- CP14. The first balance-due bill, mailed to your address on file. No enforcement yet, but the clock is running.
- CP501 / CP503. Reminder notices. Still bills, with the balance climbing monthly.
- CP504. Notice of Intent to Levy. The IRS can now take your state tax refund, and a federal lien becomes possible.
- LT11 / Letter 1058. The final notice. After 30 days, wage garnishment and bank levies can begin. This is the last notice that carries formal appeal rights.
This is where an unmonitored address gets expensive. Because proper mailing counts as proper notice, a bank levy or wage garnishment can hit an account you did not know was exposed, and from where you sit it looks like it came out of nowhere. See whether the IRS can freeze a bank account without notice for how that plays out. For the full letter-by-letter map, read the order of IRS collection letters.
Not sure what you owe, or whether a letter went to an old address?
Send us your name and the years in question. An experienced tax professional will pull your account, find every balance the IRS shows, and tell you what's real before penalties and interest grow or an automated levy hits — free, confidential, no pressure.
What does a hidden balance really cost?
Say you filed your 2023 return, underpaid by $8,000, then moved. The CP14 and every notice after it went to your old apartment. Two years pass before you check your account.
- Failure-to-pay penalty: 0.5% of $8,000 per month. Over 24 months that is 12% (it caps at 25%), or about $960.
- Interest: compounding daily on the tax and the penalty at roughly 8% a year adds about $1,330 over two years.
- New balance: roughly $10,290. You never spent a dollar, and the debt grew by nearly $2,300 while you had no idea it existed.
Caught at the CP14 stage, you could have paid the $8,000, set up an installment agreement, or requested first-time penalty abatement to remove the penalty. Finding the balance early is the whole game. You can estimate how long the IRS has left to collect on an assessed year with our CSED calculator. That 10-year clock started at assessment, which may be long before you found out.
What are your options once you confirm the balance?
Once you know what you owe, the path forward is the same as anyone else's. The notice you missed does not limit your choices. Which option fits depends on the amount and your finances.
| Option | Best when | Key threshold |
|---|---|---|
| Short-term plan | You can clear it within 180 days | $0 setup fee; interest/penalties continue |
| Installment agreement | You need monthly terms | Streamlined up to $50,000 over ≤72 months, no full financials |
| Currently Not Collectible | Paying anything causes hardship | Pauses collection; debt and interest remain |
| Offer in Compromise | Assets + income can't cover the debt | $205 fee (waived if low-income); ~1 in 5 accepted |
| Penalty abatement | Clean prior 3 years, or reasonable cause | Can remove the failure-to-pay penalty entirely |
If the balance came from a year you never filed, file that return first. Your own accurate return usually brings the inflated SFR number down before you pick a payment path. If you owe for more than one year, resolve them together. The order in which you fix returns and penalties changes the balance, and the balance changes what you pay in the end. Not sure where a hidden balance puts you? See the amount-specific playbooks such as I owe the IRS $10,000.
How do you respond, step by step?
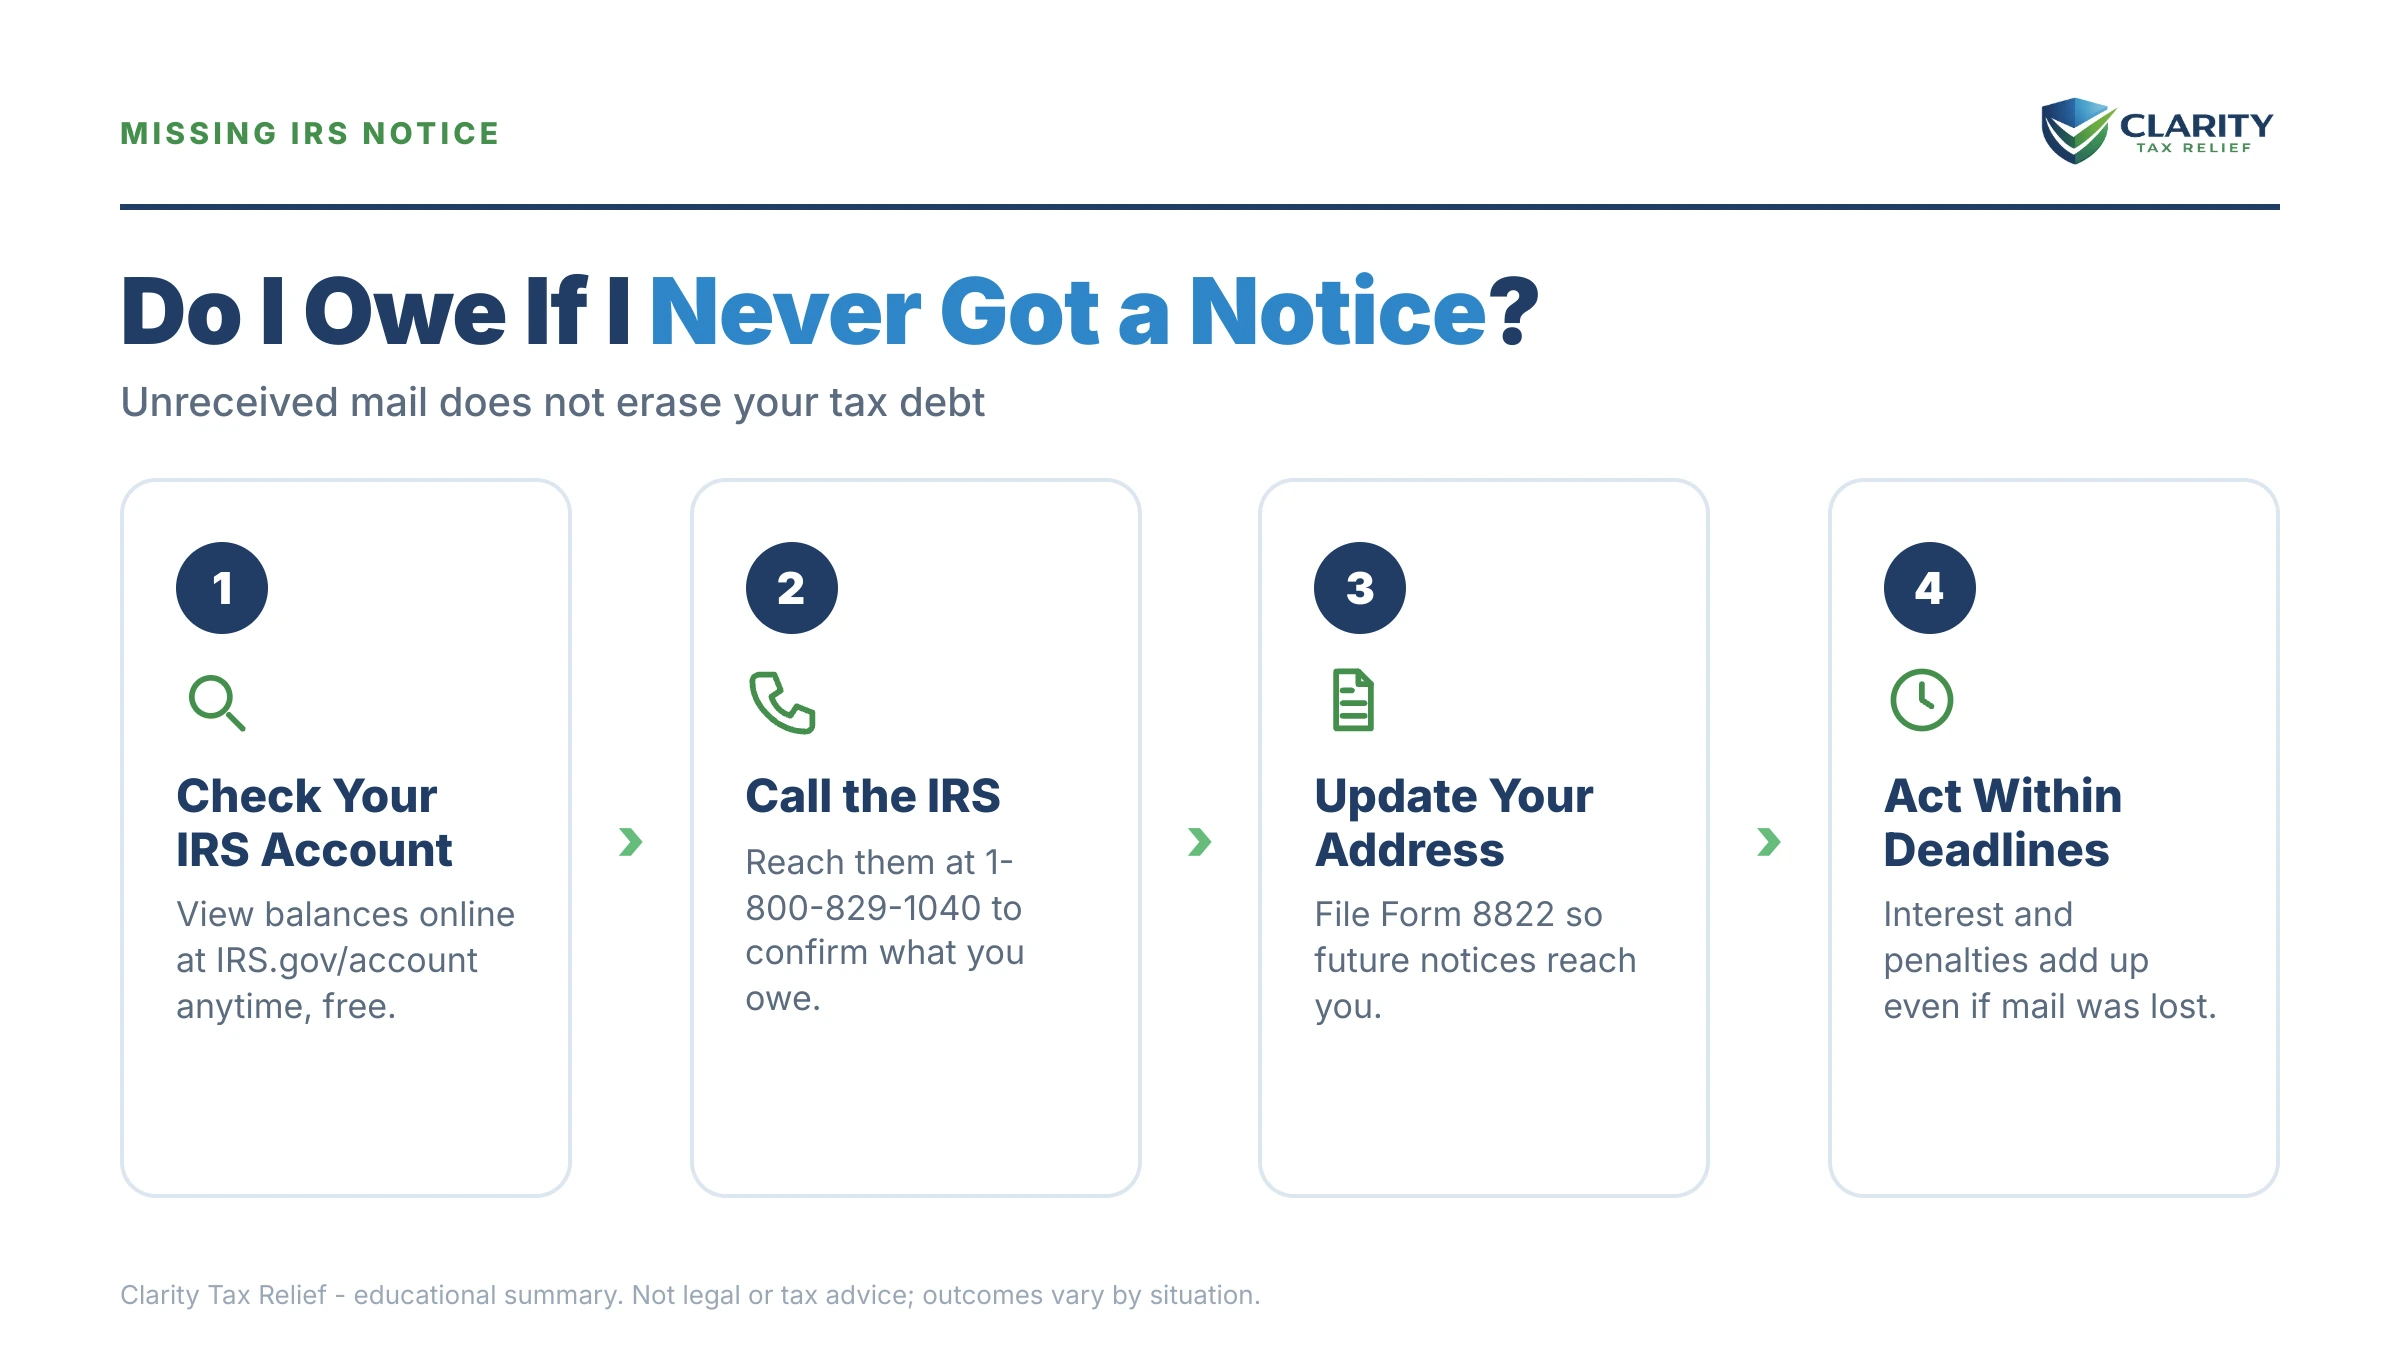
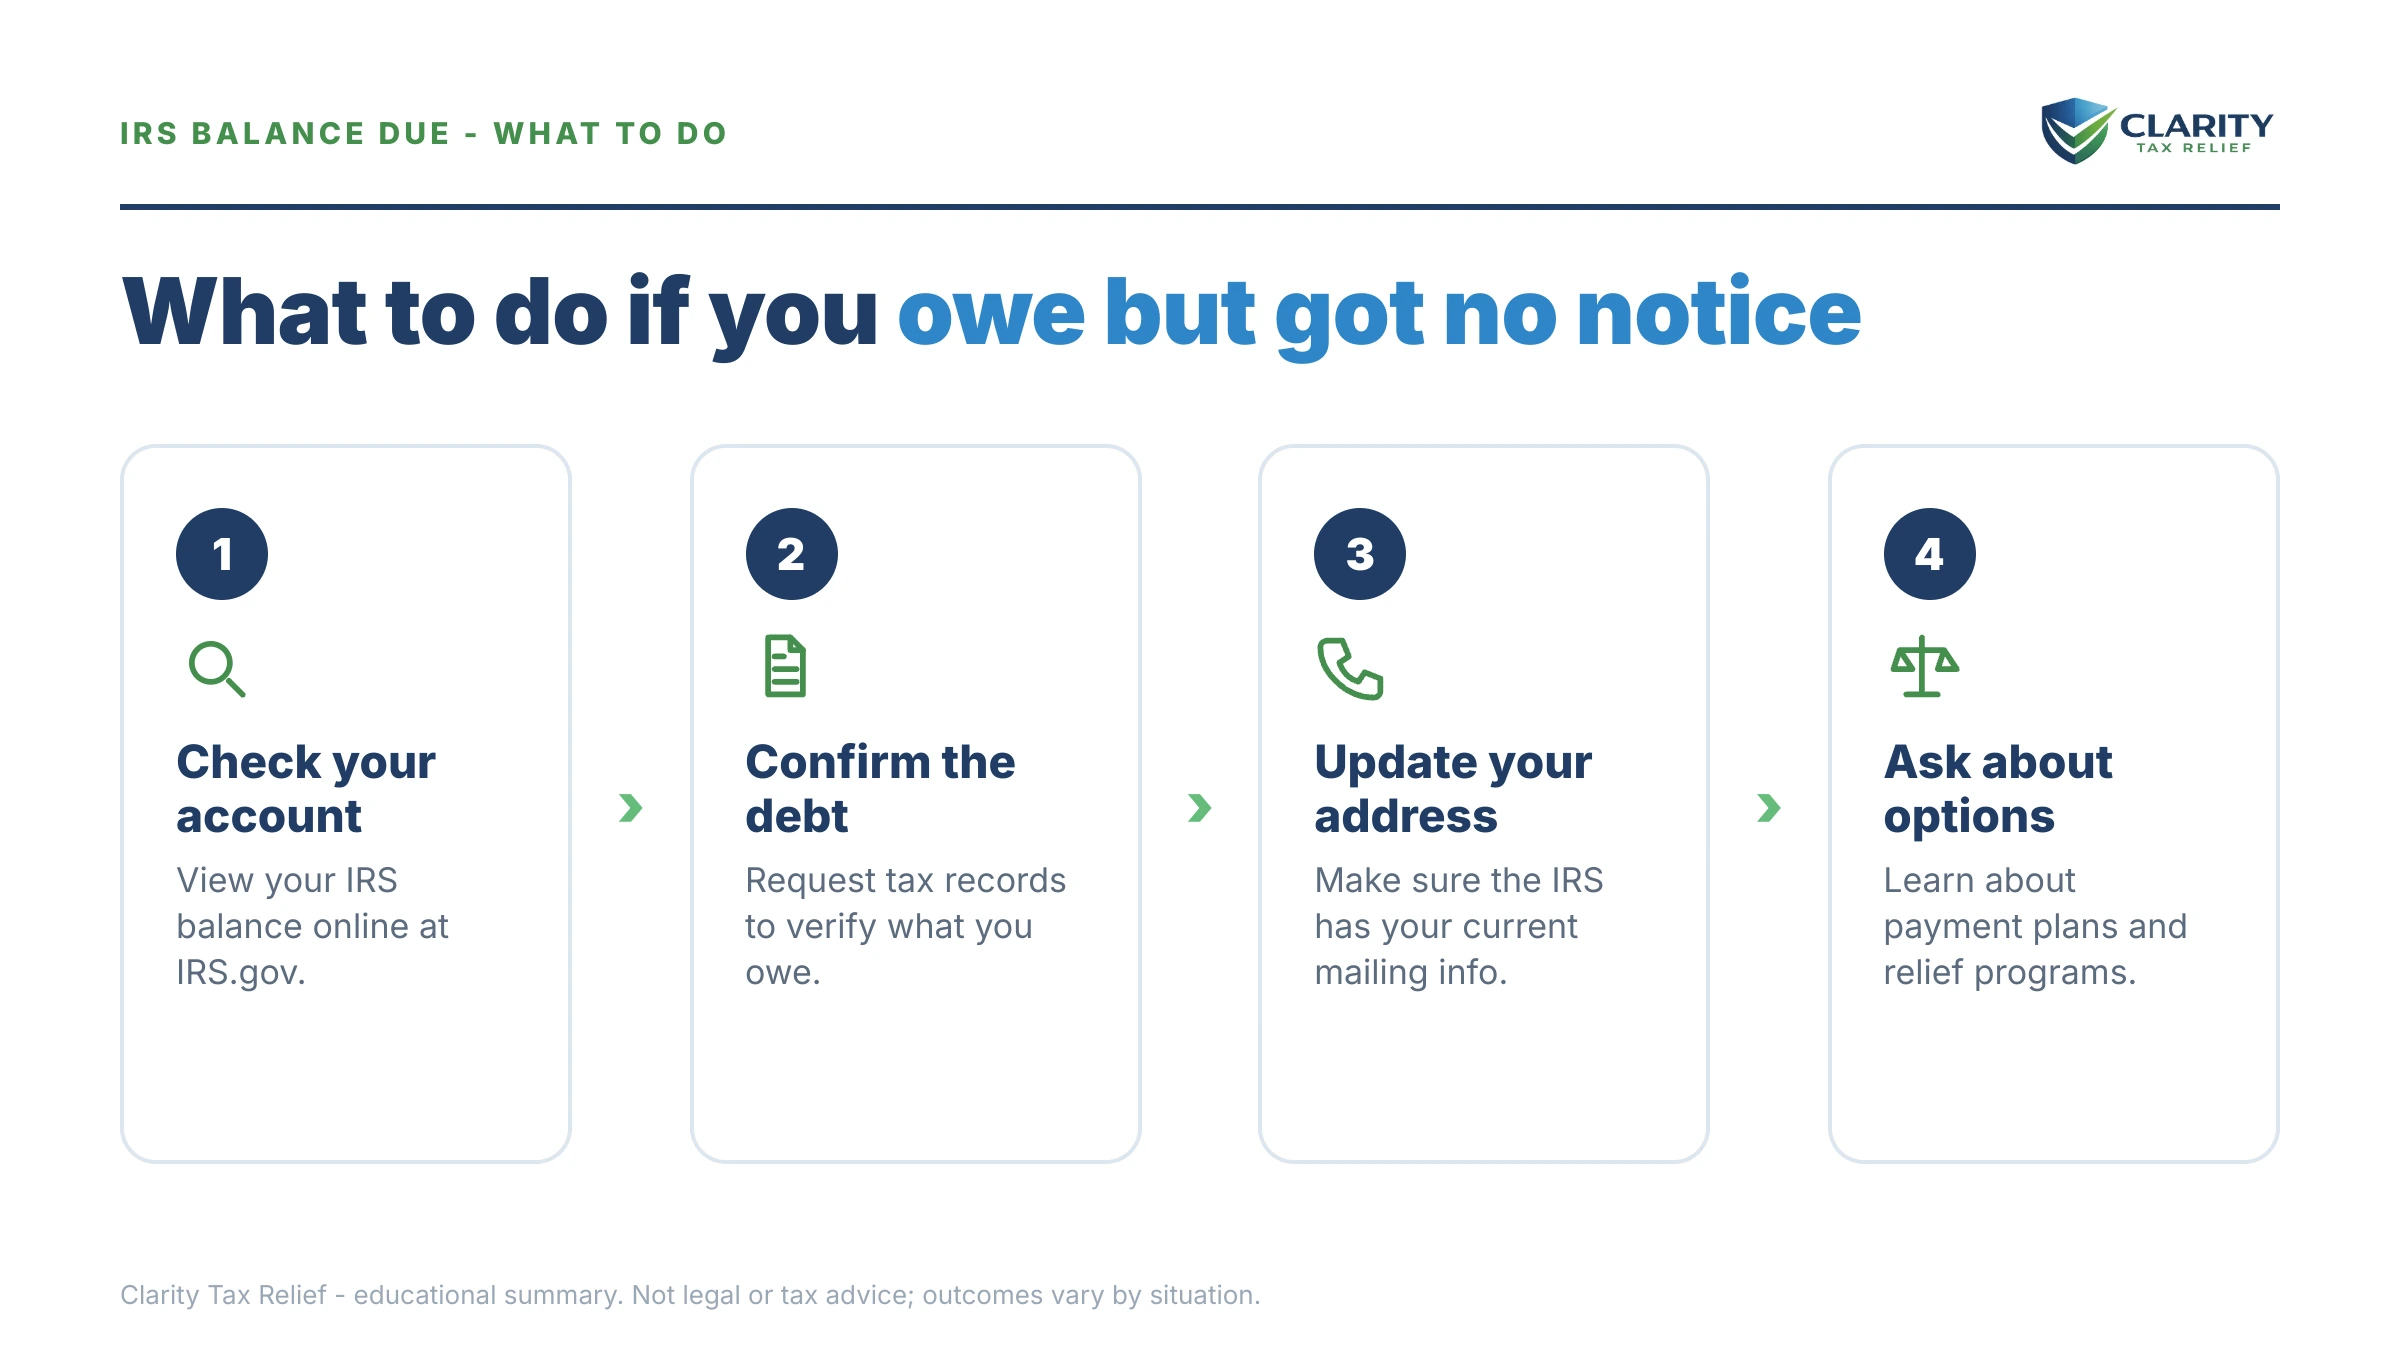
- Check your account. Log into your IRS online account and note the balance for every year shown.
- Pull your transcripts. Get the account transcript for each balance year to see the assessment date and how penalties and interest were built.
- Update your address. File Form 8822 so future notices reach you. This removes the surprise-levy risk going forward.
- File any missing returns. A year you never filed may carry an inflated SFR balance; your own return usually lowers it.
- Pick a resolution and set it up. Pay in full, start a payment plan, request hardship status, or explore an offer, before penalties and interest grow further.
- If it is multiple years, a large balance, or a levy is in motion, get a professional review so the fix happens in the right order.
When can you handle this yourself, and when does help change the outcome?
Plenty of people can clear this alone. If you log in, find a single year with a small balance you agree with, and can pay it or set up a plan within 180 days, do it yourself at IRS.gov. No one needs to be hired for that. A first balance you agree with is the simplest case there is.
Experienced help changes the result in a different set of cases: a levy or garnishment already in motion because notices went to an old address, several unfiled years, a substitute return inflating the number, a business or payroll balance, or a debt large enough that an Offer in Compromise or hardship status is on the table. In those situations the sequencing and the financial math decide how the case comes out.
One more point, because scammers work this exact fear: the IRS does not call, text, or email demanding immediate payment, and never asks for gift cards or wire transfers. If someone contacts you about a "debt you never heard about" and pressures you to pay right now, verify it yourself in your IRS account first.
What do the terms on your account mean?
- Assessment. The moment the IRS officially records that you owe. The debt and the 10-year clock both begin here.
- Last known address. The address on your most recent filed return. The IRS may legally mail notices there, and delivery counts even if you moved.
- Substitute for return (SFR). A return the IRS files for you using only reported income, with no deductions. It usually produces a higher balance than a real return.
- CSED. Collection Statute Expiration Date; generally 10 years from assessment, but pausable by appeals, an Offer, or bankruptcy.
- Levy. The seizure of money (bank account, wages, refunds), as opposed to a lien, which is a claim against property.
Bottom line
A missing letter does not mean a missing debt. The balance exists from assessment, the penalty and interest run from the original due date, and mailing to your last known address counts as notice whether you read it or not.
Your IRS online account and your account transcript will tell you in minutes whether anything is owed and for which years. Check, update your address with Form 8822, file anything missing, and choose a resolution while the number is still as small as it is going to get.
Owe the IRS but never got a notice? Common questions
Can I owe the IRS if I never got a notice?
Yes. A tax debt exists the moment the IRS assesses it, not when a letter reaches your mailbox. Notices are how the IRS tells you about the debt. But the balance, the interest. The penalties all keep building whether or not the mail ever arrived. The fastest way to know for sure is to log into your IRS online account and check the balance for each tax year.
How do I find out if I owe the IRS?
The most reliable way is your IRS online account at IRS.gov, which shows your current balance by year, plus payment history and any notices issued. If you can't verify your identity online, order an account transcript by mail or call the IRS. Your account transcript lists the assessment and every penalty and interest charge, so you can see exactly how the number was built.
Why didn't I get an IRS notice?
The most common reason is a stale address — the IRS mails to your last known address, which is the one on your most recent filed return. If you moved and didn't file since, or didn't submit Form 8822, the notices went to your old home. Mail delays, a return the IRS filed for you, and identity theft can all put a balance on your account without a letter you ever saw.
Can the IRS levy me if I never got the notice?
Legally, yes, if the IRS mailed a final notice to your last known address, the levy can be valid even if you never opened it. Under the last known address rule, proper mailing counts as proper notice. That is why an unmonitored old address is dangerous: a bank or wage levy can arrive with no warning you ever received.
Does the 10-year collection clock run if I never got a notice?
Yes. The 10-year collection statute (the CSED) starts when the tax is assessed, not when you learn about it. But the clock can be paused by events like a pending Offer in Compromise, bankruptcy, or a collection appeal, so debt does not simply vanish on a fixed date. Pull your account transcript to see the assessment date each year's clock runs from.
Do penalties and interest still add up if I never got a bill?
Yes, and this is the expensive part of never seeing the notice. The failure-to-pay penalty runs at 0.5% of the unpaid tax per month up to 25%, and interest compounds daily on top of the tax and penalties. None of it waits for you to open an envelope, so a balance you never knew about can grow by thousands before you find it.
What if I owe from a year I never filed a return?
The IRS can file a substitute for return (SFR) on your behalf using only the income reported to it, with no deductions or credits, which usually inflates the balance. That assessed amount then generates notices to your last known address. Filing your own accurate return for that year almost always lowers the balance, even after the SFR has posted.
Your next 24 hours
- Find your balance. Log into your IRS online account and write down the amount owed for every year listed. That's the number that actually matters, not the mail you did or didn't get.
- Gather the basics. Pull your last filed return, an account transcript for any balance year, and confirm the address the IRS has on file so future notices reach you.
- Get a free case review. If a balance surprises you, or you fear a levy already went to an old address. Use the 2-minute form or call (888) 825-7779. Interest and penalties keep accruing, so confirming today costs you the least.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.