California FTB
FTB Form 3561: How to Fill Out California's Financial Statement (2026)
The short answer: FTB Form 3561 is the California Franchise Tax Board's financial statement (the state's Form 433-F). The FTB asks for it when a payment plan falls outside its self-service rules ($25,000 or less, 60 months, all returns filed) or you request a hardship delay. Your numbers set your monthly payment. In Clarity Tax Relief's experience, the expense entries are where the FTB pushes back most.
This guide covers what FTB Form 3561 is, when the Franchise Tax Board requires it, what happens if you ignore the request, what each of its nine sections asks for, the IRS expense standards the FTB applies to your numbers, how to complete and submit it, and how it differs from the IRS's Form 433-F.
You asked the FTB for a payment plan, or for breathing room, and instead of a yes, you got a letter demanding a "completed financial statement" listing every dollar you earn, spend, and own. That is not a rejection. It is the FTB saying your balance or your request is outside the checkbox rules, so the numbers will decide what happens next, and you control what those numbers show.
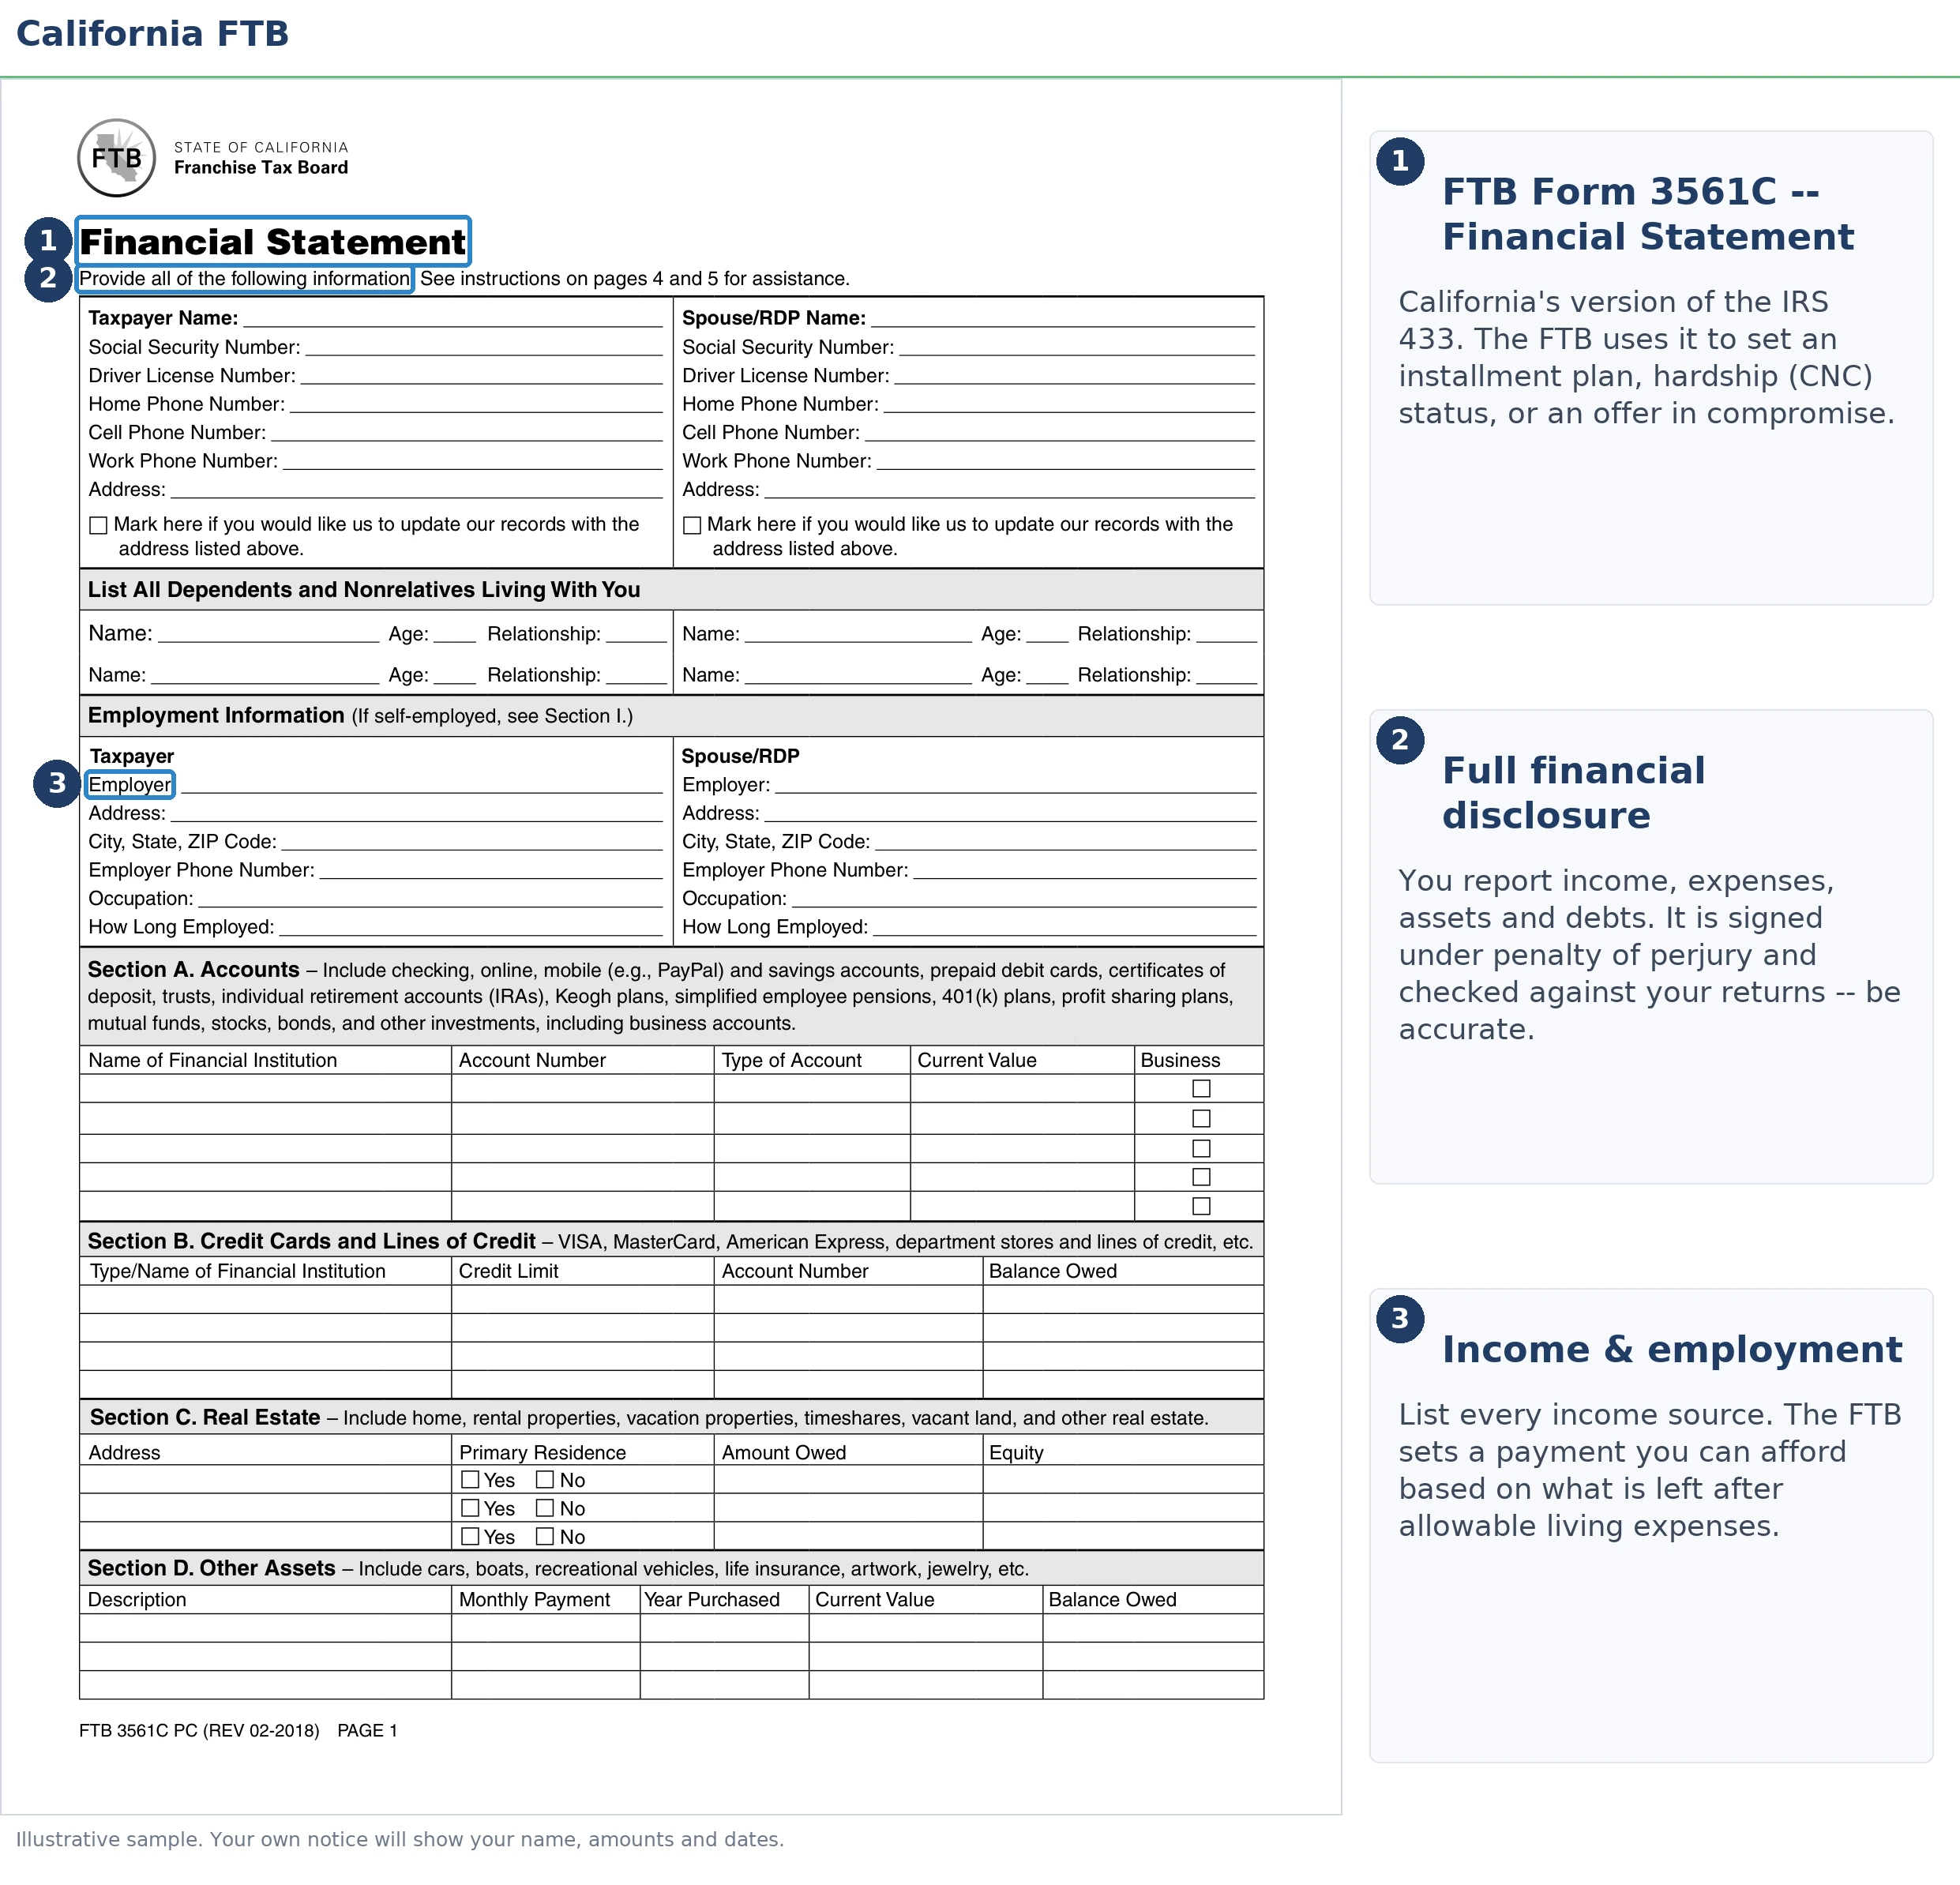
Filled out carelessly, FTB Form 3561 locks you into a payment you cannot sustain. Filled out completely and with the expense rules in mind, it is the document that turns a five-figure California balance into a manageable arrangement. Farther down, the image shows exactly what Form 3561 looks like and which sections deserve the most care before you sign it.
⏱ Your deadline: the response date printed on the FTB letter that requested your Form 3561. There is no single statutory window. While the form sits unreturned, interest keeps accruing, a collection cost recovery fee can be added, and involuntary collection can resume. The date on your letter is the clock that matters.
What is FTB Form 3561, and why does the FTB want yours?
Clarity Tax Relief describes Form 3561 as California's version of the IRS collection financial statement. Form 3561 is the Franchise Tax Board's Financial Statement. The current printing is FTB 3561C PC, three pages of questions plus two pages of instructions, and its stated purpose is "to provide current financial information necessary to help us determine how you can satisfy an outstanding tax liability." It covers your income from every source, your monthly living expenses, your bank accounts, credit lines, vehicles, real estate and other assets, plus your other debts and any business you own.
The FTB does not send this form as a formality. It appears in three situations: you requested a payment arrangement that falls outside the self-service rules, you asked the state to delay collection for financial hardship, or an FTB collector wants updated financials on an account already in collection. In every case, the same rule applies: the numbers on this form become the FTB's baseline for what it will demand from you.
One thing Form 3561 is not: an IRS document. It resolves nothing on your federal account. If you owe both agencies, common for self-employed Californians, the federal side runs on its own financial statement, covered in our Form 433-F walkthrough. The one courtesy the FTB extends is this, from the 3561 instructions: if you submitted an IRS Form 433-A or 433-F dated within the previous 12 months, you may send the FTB that form instead. The general playbook for negotiating a tax debt on your own lives in our guide to how to settle tax debt yourself, and which agency to resolve first is its own decision.
“If you are unable to make the minimum required payment amount, you will receive directions for completing either Form 9465, Installment Agreement Request PDF and Form 433-F, Collection Information Statement PDF”
— Online payment agreement application (IRS.gov)
When does the FTB require Form 3561?
Clarity Tax Relief checks a balance against the FTB's self-service limits before anything else. The FTB asks for Form 3561 when your request falls outside its self-service rules or when it wants proof before it agrees to anything. The FTB's payment plan page lists three conditions for a self-service installment agreement: the amount due does not exceed $25,000, you can pay it in 60 months or less, and you have filed all your income tax returns for the past five years. The same page adds that you cannot apply online if you already have an agreement, a wage garnishment, or a bank levy, and that in those cases "you may have to submit a financial statement for approval" and "a tax lien may be a condition of your arrangement." Inside the rules, most individuals can set up an FTB payment plan online for a $34 fee without disclosing their finances at all.
The form is also the gateway to a collection delay for hardship, the FTB's rough equivalent of currently-not-collectible, where collection is paused because your income cannot cover basic living costs. You cannot get that by asking; you get it by demonstrating it, line by line, on this form. Our guide to FTB currently not collectible covers what happens after the FTB says yes.
| Option | Typical eligibility | Form 3561 required? |
|---|---|---|
| Pay in full | Anyone; stops interest immediately | No |
| Self-service payment plan ($34 fee) | $25,000 or less, paid within 60 months, all returns filed for the past 5 years, no existing agreement, garnishment or levy | No |
| Payment arrangement outside those rules | Balance over $25,000, payoff longer than 60 months, or collection already under way | Usually. The FTB says it "may" require one, and in practice it does |
| Collection delay for financial hardship | Income cannot cover necessary living expenses; reviewed periodically | Yes. It proves the hardship |
| FTB Offer in Compromise | You cannot pay in full now or in the foreseeable future | Uses its own application package with similar financial disclosure |
What happens if you ignore the FTB's request?
An unreturned Form 3561 usually gets your payment-plan or hardship request denied, and puts your account back on the FTB's enforcement track. California's collection machine is more aggressive than the IRS's, and it moves through these stages:
“Treat the response date on the FTB letter as real. A late financial statement can put your account back in collection while your request sits unanswered,” says Angeline Balsitis, EA, an IRS Enrolled Agent at Clarity Tax Relief.
- Your request is closed. The arrangement or hardship review that triggered the form is denied for non-response, and the full balance is due.
- Costs stack onto the balance. Interest keeps compounding. The FTB can add its collection cost recovery fee; see FTB collection fees for how these charges pile up.
- Involuntary collection resumes. The FTB can issue an Order to Withhold against your bank account and an Earnings Withholding Order for Taxes against your paycheck. How much can FTB garnish breaks down the paycheck math.
- A Notice of State Tax Lien is recorded. The FTB says the lien attaches to any California real or personal property you own or later acquire, becomes public record, and is effective for at least 10 years. Our FTB tax lien guide covers release and withdrawal.
- The largest balances face the harshest tools. The FTB is required by law to publish a list of the 500 largest delinquencies over $100,000 twice a year, after a 30-day warning letter (FTB 4192), and placement carries FTB license suspension exposure for professional and driver's licenses.
The stage that hurts most is the third one, because it is silent: the first sign of an FTB bank levy is often money already frozen. And unlike the IRS's 10-year clock, the FTB has 20 years to collect under R&TC §19255. Waiting it out is not a realistic strategy in California. See California's 20-year collection statute for why that changes everything.
FTB letter asking for a financial statement?
Send us a copy before the response date on your letter passes. An experienced tax professional will review your Form 3561 numbers, flag the expense entries the FTB is most likely to challenge, and map your realistic options, free and confidential.
What are your realistic options at each balance level?
What Form 3561 gets you depends heavily on how much you owe the FTB. The same form supports very different outcomes at different balance levels:
| FTB balance | Realistic path | Financial statement? |
|---|---|---|
| Under $10,000 | Self-service payment plan; even modest monthly payments clear it within 60 months | Usually not needed |
| $10,000 to $25,000 | Self-service plan still available if you can pay it off within 60 months (roughly $167 to $417 a month before interest) | Usually not needed |
| $25,001 to $100,000 | Arrangement built on Form 3561; hardship delay or an FTB OIC if the numbers show you cannot pay | Yes. Form 3561 territory |
| Over $100,000 | Heightened scrutiny, likely lien, Top 500 and license exposure; professional representation strongly advisable | Yes, plus deeper asset review |
A worked example: $61,200 with three years unfiled
Say you are a gig worker who did not file California returns for three years, and the FTB's filing-enforcement assessments now total $61,200. Those assessments were built from gross 1099 data: no mileage, no platform fees, no expenses. Step one is not the payment plan. It is filing the real returns, which we cover under FTB demand to file, because actual returns frequently shrink an estimated balance before you negotiate a dime of it.
Now run the payment math on $61,200. Spread over 60 months, that is $1,020 a month before interest, and because the balance tops $25,000, Form 3561 is coming either way. Suppose your form shows $5,900 in average monthly gig income and $5,150 in documented, necessary expenses. That leaves $750 a month of capacity, $270 short of a 60-month payoff.
That gap is exactly what the financial statement exists to resolve. Honest, documented numbers give the FTB grounds to accept a longer term at $750, and if your expenses legitimately consume your income, the same form supports a hardship delay instead. Inflate your income or skip expenses you pay, and you have volunteered for a $1,020 payment that will default by winter.
What does Form 3561 ask for, section by section?
The current FTB 3561C PC runs nine lettered sections after the identification block, and each one has a trap for the unprepared. The image below shows what the form looks like and where each section sits, so you can follow along with your own copy.
| Section | What it asks for | The trap |
|---|---|---|
| Header | Names, SSNs, driver license numbers, phones, address, dependents, employer details for you and your spouse or RDP | Leaving the employer block blank when you are self-employed instead of pointing to Section I |
| A. Accounts | Every checking, savings, online and mobile account (PayPal is named), prepaid cards, CDs, IRAs, 401(k)s, brokerage and business accounts | Omitting an account with a zero balance; the instructions say list all accounts even if empty |
| B. Credit cards and lines of credit | Limit, account number and balance owed on every card and line | Same rule: list them even with no balance |
| C. Real estate | Each property, whether it is your primary residence, amount owed and equity | Equity is market value minus what you owe; the FTB checks county rolls |
| D. Other assets | Cars, boats, RVs, life insurance, artwork, jewelry, business tools and intangibles, with year, value and balance owed | Forgetting a leased vehicle; write "lease" in the year column |
| E. Monthly income | Net pay for you and your spouse, rental, retirement, benefits, commissions, other income, and contributions from others in the home | Reporting gross instead of net; for gig income, net after business expenses with a Schedule C or P&L attached |
| F. Local standards | Housing and utilities, and vehicle ownership and operating costs, each with a box to mark if the IRS standard is used | Claiming actual costs above the IRS standard; the FTB allows whichever is less |
| G. National standards | Food, housekeeping, clothing, personal care, miscellaneous, and out-of-pocket health care | Under-claiming; the FTB allows the full IRS standard for your family size without proof |
| H. Other | Child care, estimated tax payments, term life, retirement contributions, your federal installment agreement, student loans, court-ordered support, health insurance | Leaving out an approved IRS payment plan, which the FTB allows as an expense |
| I. Business information | Business name, FEIN, type, receivables, cash available now, merchant accounts, and any bankruptcy | Listing receivables you cannot collect as if they were cash |
Three rules from the instructions decide how the FTB reads Sections F through H. First, it evaluates your ability to pay using the IRS Collection Financial Standards, the same tables the IRS publishes. Second, for housing, utilities and vehicles it allows the standard or your actual cost, whichever is less, and a single person is normally allowed one car. Third, for the national standards (food, clothing, personal care, miscellaneous) it allows the full standard for your family size without asking what you spend, and it allows no deviation at all on the miscellaneous line. Every expense goes in as a monthly figure: quarterly bills divided by 3, weekly bills times 4.3, biweekly times 2.17, semi-monthly times 2.
The verification side is where packages stall. The form is signed under penalty of perjury, and the instructions warn that after review the FTB "may ask you to send substantiation of your current assets, liabilities, income, and expenditures." Self-employed filers are told to attach a Schedule C or a current profit-and-loss statement. Have three months of bank statements and pay stubs or platform earnings reports ready before you send it, because the FTB compares your income figure against your deposits.
How to complete and submit FTB Form 3561, step by step
- File any missing California returns first. The FTB requires all returns for the past five years before it approves an arrangement, and filing-enforcement assessments are usually inflated. Filing the real returns can shrink the balance before you negotiate how to pay it.
- Download the current form. The live version is FTB 3561C PC, five pages including instructions, from ftb.ca.gov. If you gave the IRS a Form 433-A or 433-F within the last 12 months, the FTB will accept a copy of that instead.
- Gather three months of financial proof. Pull bank statements for every account in Section A, pay stubs or gig-platform earnings reports, and bills for every expense you plan to claim above the IRS standard amount.
- Convert every expense to a monthly figure. The instructions give the math: quarterly bills divided by 3, weekly bills times 4.3, biweekly times 2.17, semi-monthly times 2.
- Complete every line of the form. Blank sections cause rejections and delays. Write "none" or "0" instead of leaving a field empty, and sign it; the declaration is under penalty of perjury.
- Propose a monthly payment your budget can sustain, then submit and confirm receipt. Send it the way the FTB's letter directs, or mail it with Form 3567 to the Sacramento address on that form. Keep a complete copy and calendar a follow-up call to 800-689-4776 if you hear nothing in 30 days.
One California-specific wrinkle on the payment side: if you have previously triggered the state's electronic-payment requirement, your installment payments must be made electronically or you will face an additional 1% penalty. Details in our guide to FTB mandatory e-pay.
How does FTB Form 3561 differ from IRS Form 433-F?
When a client owes both governments, Clarity Tax Relief prepares the two forms from one set of numbers. Form 3561 and IRS Form 433-F do the same job for two different governments, and only one of them accepts the other. If you owe both, the usual pattern when unfiled self-employment years catch up at once, you are looking at two negotiations and two sets of rules, though the FTB will take a 433-A or 433-F dated within the last 12 months in place of its own form.
The differences matter. Both agencies use the IRS Collection Financial Standards, but the FTB runs its own reasonableness review on top. The IRS generally has 10 years to collect; the FTB has 20. IRS hardship status can realistically outlast the federal collection window. The FTB's longer statute means a hardship delay in California is usually a pause, not an endgame. And the agencies do not coordinate: a payment plan with one does nothing to stop levies from the other, so sequencing which agency to resolve first is a real strategic decision.
Common FTB Form 3561 mistakes
- Negotiating before filing the missing returns. The FTB requires five years of filed returns, and filing-enforcement assessments are built from gross 1099 data. Real returns frequently shrink the balance first.
- Leaving lines blank. Blanks cause rejections and delays. Write "none" or "0."
- Cherry-picking a gig income month. Average several recent months; the FTB compares your figure to your bank deposits.
- Claiming housing or car costs above the IRS standard without a reason. The FTB allows the lesser of the standard or actual cost. If a higher cost is necessary for health or for producing income, say so in the Notes block.
- Under-claiming the national standards. Food, clothing and miscellaneous are allowed in full for your family size with no proof required. Leaving money on that line raises your payment for nothing.
- Understating assets. The FTB cross-checks DMV records, county property rolls, and bank data it already holds, and the form is signed under penalty of perjury.
- Proposing a payment you cannot sustain. A defaulted arrangement leaves you worse off than a slower one that holds.
Can you handle Form 3561 yourself, or does help change the outcome?
Plenty of people complete this form without help, and you may be one of them. If your returns are all filed, your income is a straightforward W-2, your expenses sit inside the IRS standards, and you are documenting an arrangement you can clearly afford, Form 3561 is tedious but manageable on your own.
Experienced help changes the outcome in the harder fact patterns: multiple unfiled years sitting on inflated estimated assessments, gig or business income the FTB will scrutinize deposit by deposit, a garnishment or bank levy already in motion, balances near the $100,000 Top 500 tier, or a case where the honest numbers point toward hardship or an Offer in Compromise rather than a payment plan. In those situations, how the financial statement is built, which returns get filed first, how variable income is averaged, how necessary expenses above the standards are documented, directly determines the payment you live with for years. Clarity Tax Relief reviews FTB financial statements before they go out, and the review is free.
Terms on your FTB paperwork, decoded
- Financial statement: the sworn snapshot of your income, expenses, and assets that Form 3561 provides. The FTB's basis for deciding what you can pay.
- Installment agreement: the FTB's formal monthly payment arrangement, requested with Form 3567; interest continues while you pay and the setup fee is $34.
- Collection Financial Standards: the IRS's published allowances for food, housing, transportation and health care that the FTB applies to Sections F and G of the form.
- Financial hardship: the FTB's delay on collection when your income cannot cover necessary living expenses; the debt and interest remain.
- Collection cost recovery fee: a fee the FTB adds to delinquent accounts to cover its collection costs, on top of tax, penalties, and interest.
- Earnings Withholding Order for Taxes (EWOT): the FTB's wage garnishment, sent to your employer and continuous until released.
- Order to Withhold (OTW): the FTB's one-time grab of funds from a bank account; the topic of our FTB bank levy guide.
- Taxpayers' Rights Advocate: the FTB office you can contact when a state tax problem is stuck in normal channels. You also have 30 days from a Final Notice Before Levy to request an independent review.
Sources: the form itself and its instructions are at the FTB's FTB 3561C PC; the eligibility rules, $34 fee and 90-day processing note are on the FTB's payment plans page; the 20-year collection period is explained on the FTB's statute of limitations page; the IRS expense tables the FTB applies are the IRS Collection Financial Standards; and if you are juggling a federal balance alongside the state one, the IRS's payment options live at IRS.gov/payments.
FTB Form 3561 questions, answered
What is FTB Form 3561 used for?
FTB Form 3561 is the Franchise Tax Board's financial statement, used to document your income, expenses, assets, and debts when you ask for a payment arrangement or a collection delay on a California tax balance. The form's own instructions say the FTB uses it "to help us determine how you can satisfy an outstanding tax liability." It is roughly California's equivalent of IRS Form 433-F, but it only covers your state account.
When does the FTB require Form 3561?
When your request falls outside the FTB's self-service rules, which are a balance of $25,000 or less, payoff within 60 months, and all returns filed for the past five years, or when you ask the FTB to delay collection for hardship, or when a collector wants updated financials on an existing account. The FTB's payment plan page puts it plainly: "You may have to submit a financial statement for approval."
What documents do I attach to FTB Form 3561?
The instructions say the FTB may ask for substantiation of your assets, liabilities, income, and expenditures after it reviews the form, and they specifically ask self-employed filers to attach a Schedule C or a current profit-and-loss statement. In practice, send recent pay stubs or platform earnings statements, bank statements for the accounts in Section A, and bills for any expense above the IRS standard amount. Unsupported figures are the most common reason the FTB pushes back on a proposed payment.
Is FTB Form 3561 the same as IRS Form 433-F?
No, but they are close enough that the FTB will accept one for the other in one direction. The Form 3561 instructions say that if you submitted an IRS Form 433-A or 433-F dated within the previous 12 months, you may send that form instead of the 3561. The IRS does not reciprocate. The two agencies also run very different collection timelines: generally 10 years for the IRS versus 20 years for the FTB under R&TC 19255.
What happens if I don't return Form 3561?
The FTB will usually deny the payment arrangement or hardship request that triggered it, and involuntary collection can resume: an Order to Withhold on your bank account, an Earnings Withholding Order on your paycheck, and a Notice of State Tax Lien that stays effective for at least 10 years. Interest keeps accruing the entire time, and California's collection window runs 20 years, so the balance does not quietly age out. Returning the form, even late, is almost always better than silence.
Can the FTB reject expenses I list on Form 3561?
Yes. The instructions say the FTB applies the IRS Collection Financial Standards. For housing, utilities, and vehicles it allows the standard amount or what you spend, whichever is less. For food, clothing, and miscellaneous items it allows the national standard for your family size without asking for proof, and it does not allow any deviation on the miscellaneous line. Every dollar it disallows becomes a dollar it expects in your monthly payment.
Do I have to file missing returns before the FTB approves a payment plan?
Yes. The FTB's eligibility list requires that you have filed all your income tax returns for the past five years. More importantly, unfiled years often carry inflated filing-enforcement assessments built from gross 1099 data with no deductions. Filing the real returns first frequently lowers the balance you are arranging to pay, which changes the entire Form 3561 calculation in your favor.
Does submitting Form 3561 stop FTB collection?
Not automatically. The FTB says a payment plan request can take up to 90 days to process and tells you to keep making payments while you wait to avoid more interest and to keep the balance out of collections. Existing garnishments or levies do not release on their own. If a levy or garnishment is already in motion, call the FTB at 800-689-4776 and ask for a hold or release, and get help fast, because at that stage timing matters more than paperwork order.
The bottom line on FTB Form 3561
Form 3561 is the FTB's financial statement, requested when your payment plan falls outside the self-service rules ($25,000 or less, 60 months, five years of returns filed) or you ask for a hardship delay, and the numbers you put on it become the state's baseline for what it demands. Your deadline is the response date on the letter. File any missing California returns first, claim the full IRS standards where they apply, document every expense above them, average variable income honestly, and propose a payment your budget can hold. The FTB can collect for 20 years, so a complete, well-supported form is the lever you have.
Your next 24 hours
- Find the response date on the FTB letter that came with or requested your Form 3561. That date, not a statutory clock, is your real deadline.
- Gather your last filed return, three months of bank statements, and your income records. For gig work, that is your platform earnings summaries and mileage or expense records.
- Get a free case review before you sign anything. Call (888) 825-7779 or use the 2-minute form. Interest and FTB fees accrue while the form sits unreturned, and the numbers you submit set your payment for years.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed. The same is true of California Franchise Tax Board programs.
Read the transcript
Host: So you asked California for a payment plan, and what came back wasn't a yes or a no. It was a letter demanding a completed financial statement. Every dollar you earn, spend, and own.
Tax specialist: Right. That's FTB Form 3561. And the first thing I'd want a listener to hear is that it's not a rejection. It's the Franchise Tax Board saying your balance is big enough that a checkbox won't decide this. The numbers will.
Host: Big enough meaning what?
Tax specialist: Generally over $25,000. Or you need more than 60 months to pay it off. Or you're asking the state to pause collection for hardship. Under those thresholds most individuals can typically set up an FTB plan online without disclosing finances at all.
Host: Over $25,000, more than 60 months. Okay. And this is the state version of the federal form?
Tax specialist: It's roughly California's equivalent of IRS Form 433-F, yes. But, and this matters. It resolves nothing on your federal account. Neither form satisfies the other agency.
Host: Wait. So somebody who owes both is filling out two of these?
Tax specialist: Two financial statements, two negotiations, two sets of rules. Which is the common pattern, honestly, when unfiled self-employment years catch up all at once. And the agencies don't coordinate. A plan with one does nothing to stop a levy from the other.
Host: Hm. Let's talk deadline, because that's what people panic about. How long do they have?
Tax specialist: There's no single statutory window. Your deadline is the response date printed on the FTB letter that asked for the form. That date, not some general rule.
Host: So go find the letter.
Tax specialist: Go find the letter. Because while the form sits unreturned, three things are happening. Interest keeps accruing. The FTB can add its collection cost recovery fee on top of tax, penalties, and interest. And involuntary collection can resume.
Host: Spell out that last part. What does resume mean in California?
Tax specialist: It moves through stages. First, the request that triggered the form gets closed — denied for non-response, full balance due. Then costs stack onto the balance. Then involuntary collection: the FTB can issue an Order to Withhold against your bank account, or an Earnings Withholding Order against your paycheck. And a state tax lien can be filed, which attaches to your property and becomes public record.
Host: Which of those does the most damage?
Tax specialist: The bank one, I'd say, because it's silent. The first sign of an FTB bank levy is often money that's already frozen. Nobody calls you first.
Host: Okay, and the thing I keep hearing about California is the clock is longer.
Tax specialist: Way longer. The IRS generally has 10 years to collect. The FTB has up to 20 years, under R&TC 19255. So waiting out a California balance isn't a realistic strategy. It doesn't quietly age out.
Host: Twenty years. Alright, let's get into the form itself. Where do people hurt themselves?
Tax specialist: Expenses. The FTB tests what you claim for reasonableness. It can disallow amounts it considers excessive. A high car payment, discretionary spending, those are common targets. And here's the mechanic that matters: every dollar it disallows becomes a dollar it expects in your monthly payment.
Host: Oh, that's the part people miss. It's not that they cross out the line. It's that the money reappears as payment capacity.
Tax specialist: Exactly. So if an expense is unusual but genuinely necessary — a medical condition, tools or a vehicle your work requires — you document why. That's the defense. Not arguing, documenting.
Host: What about the income side?
Tax specialist: Gig income is the hard part, because it swings month to month. Average several recent months instead of cherry-picking your best or your worst. And know that the FTB compares your figure against your bank deposits, so the two have to reconcile.
Host: And assets, I assume, they already know a lot?
Tax specialist: Understate nothing. They cross-check DMV records, county property rolls, and bank information they already hold from employer and financial-institution reporting. Plus the form is signed under penalty of perjury.
Host: Can you walk me through what the numbers actually do? Like an example.
Tax specialist: Sure. Take the one from the article. Gig worker, didn't file California returns for three years, and the FTB's filing-enforcement assessments now total $61,200.
Host: $61,200. And step one is the payment plan?
Tax specialist: No — step one is filing the real returns. Those assessments were built from gross 1099 data. No mileage, no platform fees, no expenses at all. Real returns frequently shrink the balance before you negotiate a dime of it.
Host: Okay, so file first, then the math.
Tax specialist: Then the math. $61,200 spread over 60 months is $1,020 a month before interest. Now say the form shows $5,900 in average monthly gig income and $5,150 in documented, necessary expenses. That's $750 of capacity.
Host: So they're short.
Tax specialist: $270 short. And that gap is exactly what the financial statement exists to resolve. Honest, documented numbers give the FTB something to evaluate for a longer term at $750. If the expenses legitimately consume the income, the same form is what supports a hardship request instead. What you don't want to do is inflate income or skip expenses you actually pay, because then you've volunteered for a $1,020 payment that defaults by winter.
Host: And a defaulted plan is worse than a slow one.
Tax specialist: Much worse. Propose something your budget can sustain.
Host: Say the verification piece again, simply. What's in the envelope?
Tax specialist: Recent bank statements, typically three months. Pay stubs, or platform earnings reports if you're gig. Proof of the major expenses. And if you're self-employed, a simple profit-and-loss summary. Incomplete backup is the number-one reason these packages stall.
Host: Also — fill every line?
Tax specialist: Every line. Write "none" or "0" rather than leaving a field blank. Blanks cause rejections and delays.
Host: Who can do this alone?
Tax specialist: Plenty of people can. If all your returns are filed, your income is straightforward W-2, your expenses are ordinary, and you're just documenting an arrangement you can clearly afford — it's tedious, not mysterious.
Host: And when it isn't?
Tax specialist: Multiple unfiled years sitting on inflated estimated assessments. Gig or business income the FTB will scrutinize deposit by deposit. A garnishment or levy already in motion. Balances near that $100,000 tier, where you're also looking at Top 500 list and license suspension exposure. Or a case where the honest numbers point toward hardship or an Offer in Compromise instead of a plan.
Host: One more — does sending the form in stop collection?
Tax specialist: Not automatically. A pending request can lead the FTB to hold new enforcement while it reviews, but interest continues, and existing garnishments or levies don't release on their own. If something's already running, you ask the FTB directly for a hold or a release.
Host: So, next 24 hours. Find the response date on that FTB letter — that's the real deadline, not a statutory clock. Pull your last filed return, three months of bank statements, and your income records. For gig work that's platform earnings summaries and your mileage or expense records.
Tax specialist: And before you sign anything, get a review of the numbers. Someone can flag the expense entries the FTB is most likely to challenge and map what's actually on the table. That's (888) 825-7779, free and confidential.
Host: (888) 825-7779. Send us a copy of the letter before that response date passes.