Truck Drivers & 1099 Income
Owner Operator Tax Penalties: What the IRS Charges Truck Drivers and How to Cut Them (2026)
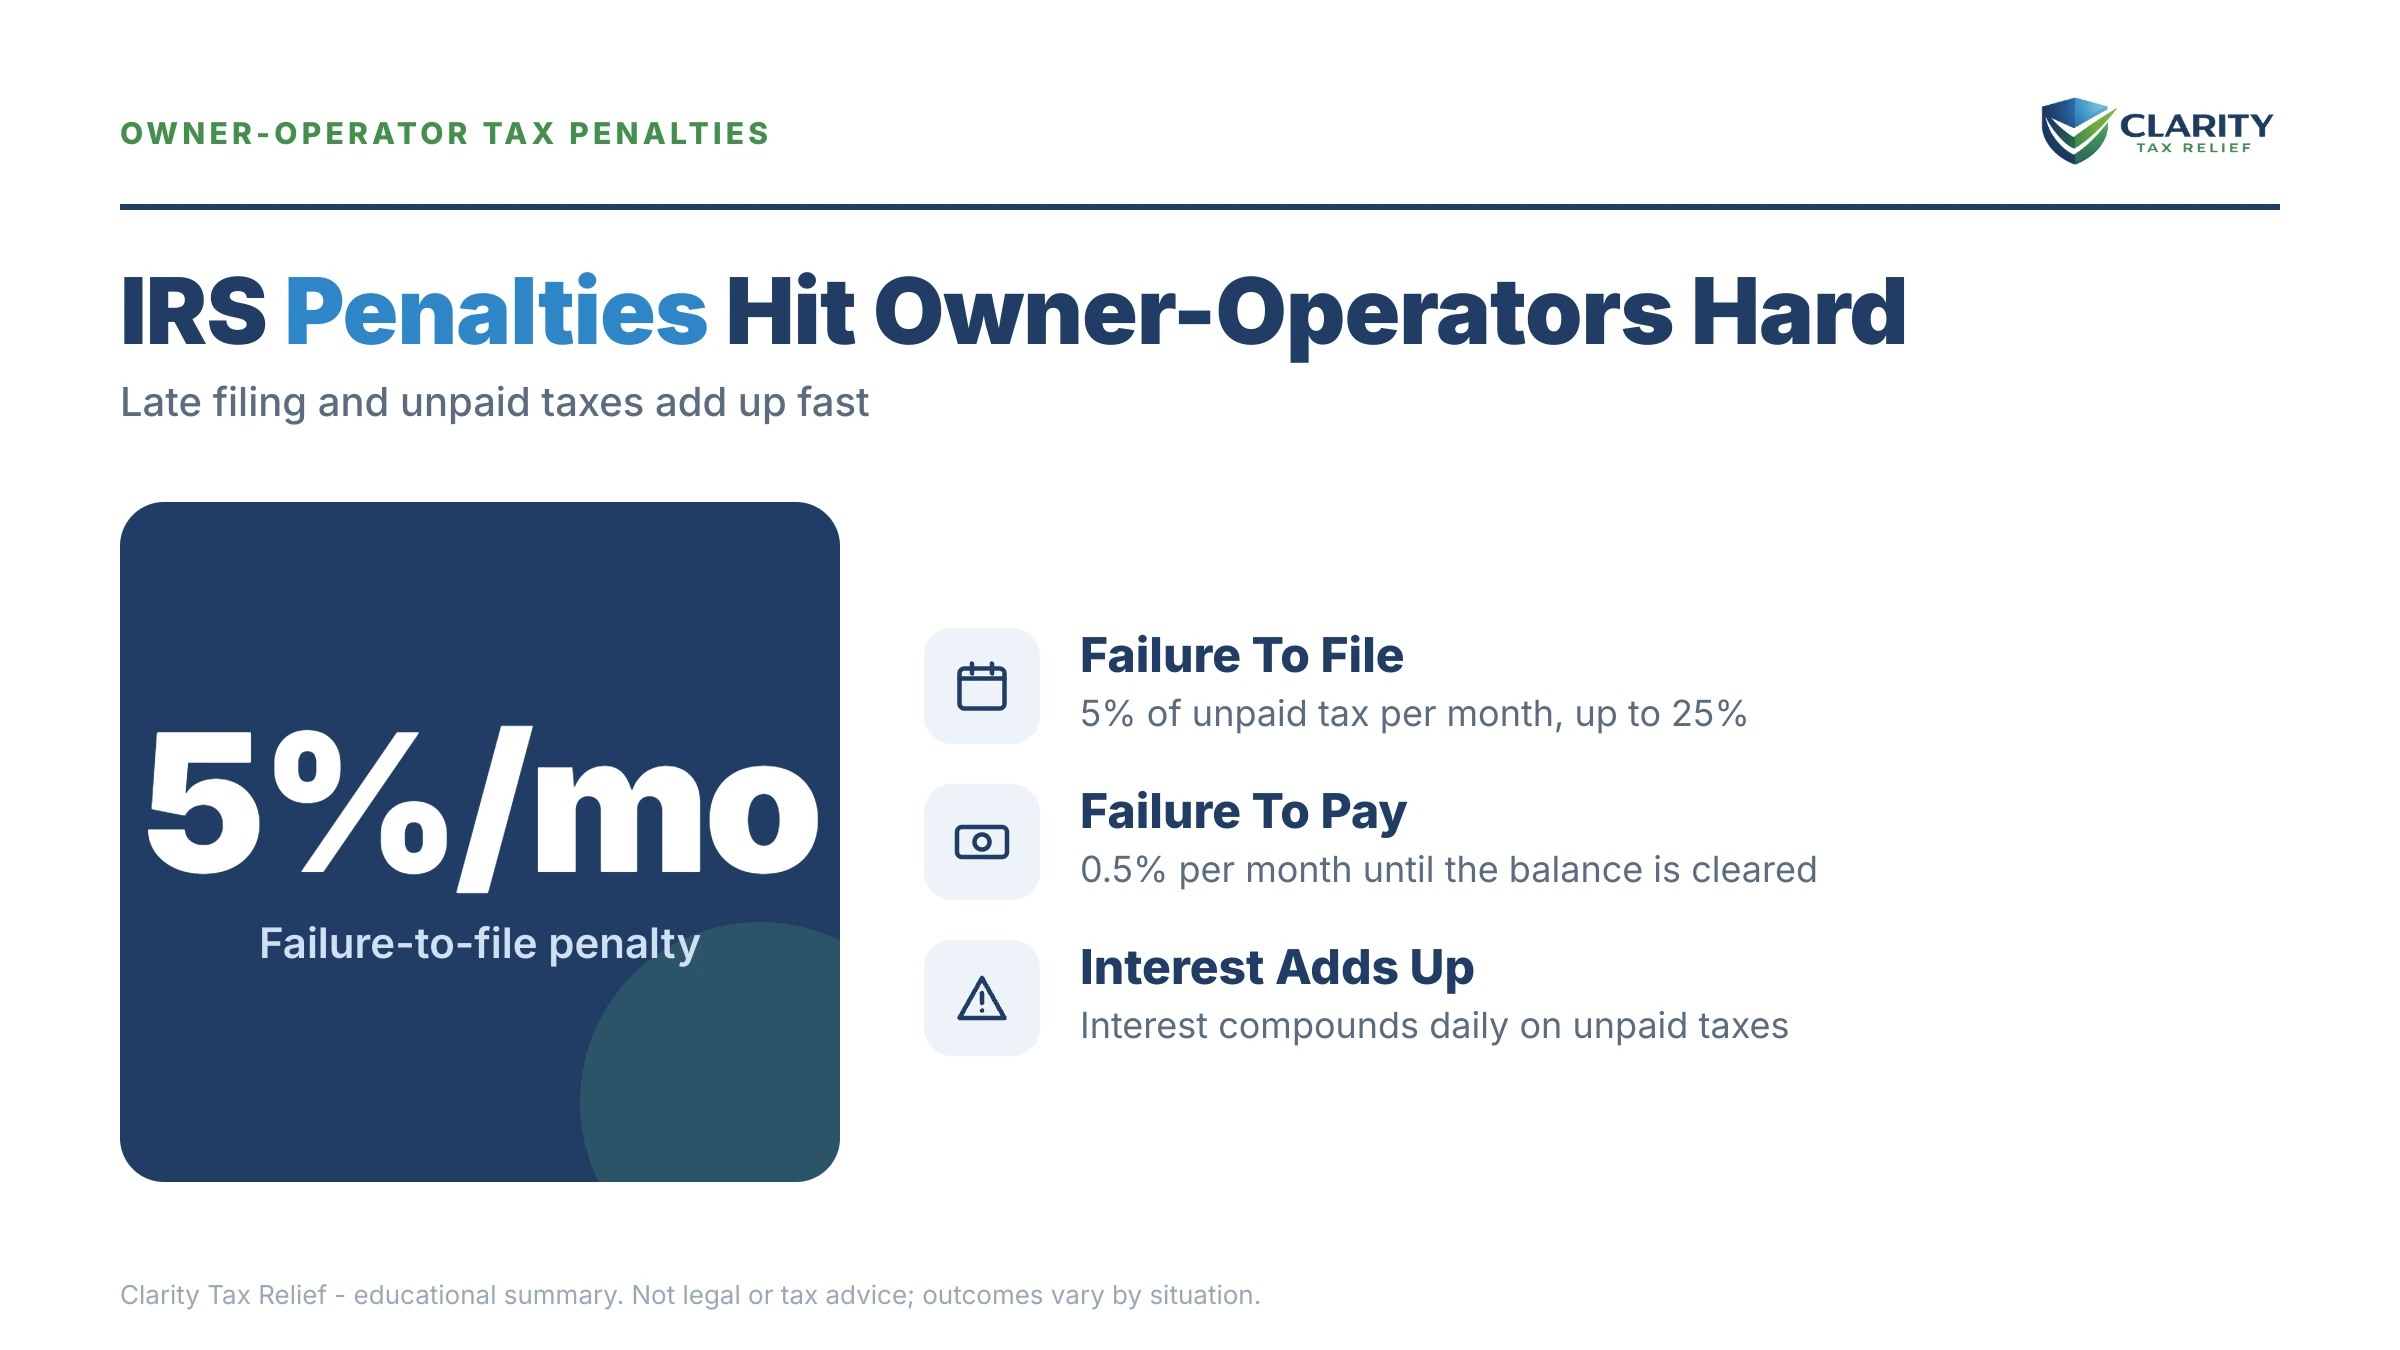
The short answer: owner operator tax penalties come from four IRS charges: failure to file (5% of unpaid tax per month, capped at 25%), failure to pay (0.5% per month), the estimated-tax underpayment penalty on skipped quarterlies, and Form 2290 late-filing and late-payment penalties. Interest compounds daily on all of it.
You drive the miles, the settlement lands in your account, and nobody takes a dime out for taxes. That works right up until a return goes unfiled or a quarterly gets skipped, and the IRS bills the whole year at once with penalties stacked on top. For an owner-operator the bill is rarely just income tax. It is income tax, plus 15.3% self-employment tax, plus three or four separate penalties that grow every month.
Nearly every one of those penalties can be reduced, and the tax underneath them usually shrinks once you file real returns with your truck deductions. This guide gives the exact rates the IRS publishes, a worked example on a $58,000 net year, the safe-harbor rules that stop the quarterly penalty, and the order to fix things in. The image below breaks down how the penalties stack on an owner-operator balance and how fast they grow.
⏱ Your real clock: there is no single deadline here. There is a meter. The failure-to-file penalty adds 5% of the unpaid tax every month it runs, up to 25%, which is ten times the 0.5% failure-to-pay penalty. Filing every missing year, even before you can pay, is the fastest way to stop the biggest charge. Interest on individuals runs 7% per year, compounded daily, for the quarter that began October 1, 2026.
Why owner operator tax penalties pile up faster than a W-2 driver's
A company driver has taxes withheld from every paycheck, so a filing slip costs a few hundred dollars. An owner-operator owes the tax the moment the money is earned, and nothing is withheld, so the whole year's liability sits unpaid until you send it in yourself. That one structural difference is what turns an ordinary tax bill into a penalty pile.
Three things drive it. First, self-employment tax of 15.3% (12.4% Social Security plus 2.9% Medicare) lands on your net profit before any income tax is calculated, and it applies once net earnings reach $400 for the year. That is the piece that shocks most drivers in their first year self-employed. Second, the IRS expects four estimated payments a year from anyone who will owe $1,000 or more at filing time, and skipping them triggers a penalty on the shortfall. Third, if the return itself goes unfiled, the 5%-per-month failure-to-file penalty piles on top of everything else.
The self-employment piece alone is often why the number feels impossible. We walk through that math in the self-employment-tax shock, explained. This page covers the individual owner-operator who files a Schedule C. If you run a fleet with drivers on payroll, the exposure is different and harsher, because unpaid payroll deposits bring the trust fund recovery penalty into play.
One penalty is unique to trucks. If your rig has a taxable gross weight of 55,000 pounds or more, you must file Form 2290 and pay the Heavy Highway Vehicle Use Tax each year. Miss it and the IRS adds a late-filing penalty, a late-payment penalty and interest, and your state will not renew the registration without the stamped Schedule 1.
How much are owner operator tax penalties? The exact IRS rates
Every one of these penalties is a percentage of the unpaid tax, so a bigger balance means bigger penalties, and cutting the tax with real deductions cuts all of them at once. Here is how each is calculated, with the figures as published on IRS.gov in November 2026.
| Penalty | Rate | Cap / notes |
|---|---|---|
| Failure to file (Form 1040) | 5% of unpaid tax per month or part of a month | Max 25%. If the return is over 60 days late, the minimum is $525 or 100% of the tax due, whichever is less, for returns due after December 31, 2025 |
| Failure to pay (Form 1040) | 0.5% of unpaid tax per month or part of a month | Max 25%. Drops to 0.25% during an approved payment plan if you filed on time; rises to 1% if you do not pay within 10 days of a notice of intent to levy |
| Estimated-tax underpayment | The IRS underpayment interest rate applied to each quarter's shortfall for the days it was late | No cap, no minimum; figured on Form 2210; applies even if you pay in full on April 15 |
| Form 2290 late filing and late payment | A late-filing penalty plus a late-payment penalty | Plus interest; the Form 2290 instructions let you request relief for reasonable cause |
| Interest | 7% per year for individuals in the quarter beginning October 1, 2026, compounded daily | Charged on the tax and on the penalties; interest is not abated for hardship |
Two rules decide most of the math. When the file and pay penalties run in the same month, the IRS reduces the 5% failure-to-file penalty by the 0.5% failure-to-pay amount, so the combined charge is 5% a month, and the failure-to-file piece hits its 25% ceiling after five months. The failure-to-pay penalty keeps running after that, month after month, until it reaches its own 25% cap or the balance is paid. Interest compounds daily on the whole thing, penalties included. For the full mechanics, see how big IRS penalties get and the difference between failure-to-file vs. failure-to-pay penalties. You can estimate your own running total with our IRS penalty & interest calculator.
What is the penalty for not paying quarterly taxes as an owner operator?
There is no flat fee. The underpayment penalty works like interest: the IRS takes each quarter's shortfall, applies its underpayment rate for the days that quarter went unpaid, and adds the four results together. Because it runs from each quarterly due date rather than from April, paying the whole year on April 15 does not erase it. It is figured on Form 2210, and the IRS computes it for you if you leave the form blank.
You avoid the penalty entirely by meeting one of three safe harbors. The IRS applies them to the tax shown on your return, meaning total tax minus refundable credits.
| Safe harbor | What you must have paid in during the year | Who it fits |
|---|---|---|
| Small balance | Enough that the return shows you owe less than $1,000 | Drivers with a W-2 spouse whose withholding covers most of the trucking tax |
| 90% of this year | At least 90% of the tax shown on this year's return | A down year, when last year's number would overpay |
| 100% of last year | 100% of the tax shown on last year's return (110% if last year's AGI was over $150,000) | The easiest target: pay a quarter of last year's total tax each quarter and the penalty is off the table |
The last row is the one most owner-operators should aim at. You know last year's total tax the day you file, so dividing it by four gives you a quarterly number that protects you no matter how the current year turns out. Our guide to how quarterly estimated taxes work covers the Form 1040-ES mechanics, and didn't pay quarterlies: the penalty math shows what a skipped year costs.
A worked example: what the penalties add up to on a $58,000 year
Say you are an owner-operator who grossed $118,000 in settlements last year and, after fuel, tires, insurance, truck depreciation and per diem, netted $58,000 on Schedule C. You did not file and did not pay, and the return is now six months late. Everything below is hypothetical and rounded.
- Self-employment tax: 15.3% applied to 92.35% of the $58,000 net, about $8,200. Half of it is deductible against income tax.
- Income tax: roughly $5,000 for a single filer after the standard deduction.
- Total tax: about $13,200.
- Failure-to-file penalty: the 5% combined rate for five months, 25% of $13,200, is $3,300. Month six adds another 0.5% in failure-to-pay, about $66.
- Estimated-tax penalty: roughly $450 for skipping all four quarters at a 7% underpayment rate.
- Interest: about $500 so far, compounding daily on the tax and the penalties.
A $13,200 tax has turned into roughly $17,500 in six months, and the meter is still running. Now flip it. If you had never filed and the IRS had prepared a Substitute for Return instead, it would have counted the full $118,000 of 1099 income with no fuel, no depreciation and no per diem, and taxed you as if you had netted six figures. The lesson is blunt. An accurate Schedule C with your truck deductions is the single biggest lever on the number, and every percentage-based penalty shrinks with it.
Which deductions shrink the tax and every penalty with it?
Because each penalty is a percentage of the tax, a deduction you forgot is worth more to you than it is to a W-2 employee. The ones owner-operators most often leave on the table, and that the IRS's substitute return never includes:
- Meals under the transportation-worker rules. Drivers subject to the Department of Transportation hours-of-service limits deduct 80% of their meal costs instead of the usual 50%, and IRS Publication 463 lets transportation workers use a flat standard meal allowance of $80 per day ($86 outside the continental United States) for 2025 instead of keeping receipts. Days on the road come straight off your ELD logs.
- The truck itself. Depreciation or lease payments, repairs, tires, and the interest on the truck loan.
- Operating costs. Fuel, tolls, scales, permits, the Heavy Highway Vehicle Use Tax you paid on Form 2290, insurance, ELD and load-board subscriptions, and the business share of your phone.
- Half of your self-employment tax, which the IRS lets you deduct in figuring adjusted gross income.
Even without perfect receipts, most of this can be rebuilt from settlement statements, fuel-card reports and ELD data. Our owner-operator trucker back taxes guide covers the reconstruction step by step.
What happens if you ignore owner operator tax penalties
Unpaid owner-operator taxes do not sit quietly. They move through an automated collection sequence that ends in levies, and ignoring the mail removes your options one at a time. The order runs like this:
- CP14: the first bill for a balance due. Penalties and interest are already accruing, and the due date printed on the notice controls.
- CP501 / CP503: reminder notices while the balance grows every month.
- CP504: Notice of Intent to Levy. The IRS can seize your state tax refund, and if the balance is not paid within 10 days of a levy notice the failure-to-pay penalty rate doubles to 1% a month. A federal tax lien becomes realistic at this stage.
- LT11 / Letter 1058: the final notice, with Collection Due Process appeal rights on Form 12153. Once its 30-day window runs, the IRS can levy your bank account (the bank holds the funds for 21 days, then sends them to the IRS) and can serve a levy on anyone who holds money owed to you, which for a driver means a broker, a factoring company or a carrier.
For an owner-operator the bank levy and the receivables levy hurt most. A frozen operating account can park the truck mid-route. These notices and levies are generated by automated systems, so the sequence advances whether or not a human ever reviews your file, and that is exactly why acting before the LT11 stage matters. One more number to know: if your combined assessed balance ever passes $66,000 (the 2026 figure, adjusted yearly for inflation), the IRS can certify the debt to the State Department and your passport can be denied or revoked. For a driver who runs into Canada or Mexico, that is a working problem, not a travel problem.
Behind on returns or watching penalties grow?
The failure-to-file penalty adds 5% every month a return stays unfiled, so get an owner-operator tax review before the next month rolls over. An experienced tax professional will map which years to file, which penalties can come off, and what your realistic monthly number is. Free and confidential.
Your options to reduce or resolve the debt
The most important move for an owner-operator is almost always to file every missing year first. That stops the file penalty and usually lowers the tax. After that, these are the paths, and which one fits depends on the balance and your cash flow.
| Option | Who it fits | Cost / catch |
|---|---|---|
| Short-term plan (180 days or less) | Owe under $100,000 and can pay in full after a good season | $0 setup fee; interest and the 0.5% penalty keep running |
| Long-term payment plan (the IRS now calls it a Simple payment plan) | Owe $50,000 or less in combined tax, penalties and interest, all returns filed | $29 setup online with direct debit ($69 other methods; waived for low income on direct debit); no financial disclosure |
| Non-streamlined or partial-pay agreement | Owe more than $50,000, or cannot afford the full-pay monthly amount | Form 433-series financials required |
| Currently Not Collectible | A bad-freight stretch; cannot cover basic living costs plus the IRS | Debt stays and grows; levies pause; the IRS reviews it periodically |
| Offer in Compromise | Assets plus future income cannot cover the debt | $205 application fee plus 20% of a lump-sum offer up front, both waived with low-income certification; the IRS accepted 5,464 of 38,797 offers in FY 2025 |
| Penalty relief | Clean prior three years, or a documented reasonable cause | Free to request; removes penalties, not the underlying tax |
For most owner-operators under $50,000, the streamlined installment agreement is the workhorse, and the setup fee is lowest when you apply online with direct debit. If a season went bad and you cannot cover living costs plus the IRS, Currently Not Collectible status pauses enforcement. Settling for less through an offer is real but means-tested. Read how an offer in compromise actually works before anyone sells you one: the IRS Data Book shows it accepted roughly one offer in seven in fiscal 2025, and the ones it accepts are the ones where the math shows it could never collect the full balance.
On penalties specifically: if your prior three years were clean, first-time penalty abatement can remove a year's failure-to-file and failure-to-pay penalties, and you still have to ask for it on 2024 returns and on 2025 returns processed before the IRS switched over. The replacement, Automatic Exemption from Penalty (AEP), began phasing in during the summer of 2026. It applies the same three-year clean-history test during return processing, with no request, and sends you a notice saying the penalty was never assessed. For original returns due on or after January 1, 2027, first-time abatement is gone and AEP is the only version. If a truck fire, a serious accident, a hospitalization or theft of your records is the reason you fell behind, reasonable-cause penalty abatement may apply on top of either.
Form 2290 and the HVUT: the penalty only truckers get
The Heavy Highway Vehicle Use Tax runs on its own calendar. The tax period is July 1 through June 30, and Form 2290 is due by the last day of the month after the month the truck first hits a public highway in that period, so a truck in use in July is due August 31. If a due date lands on a weekend or holiday, the next business day counts. The IRS stamps and returns the second copy of Schedule 1 as your proof of payment, and that stamped copy is what your state DMV wants at registration. E-filing is required when a single return reports 25 or more taxed vehicles, and the IRS says a mailed return takes about six weeks to come back with the stamped Schedule 1, which is reason enough to e-file even one truck.
File it late and the IRS adds a late-filing penalty, a late-payment penalty and interest. The instructions do not publish a rate on the form itself, and the Form 2290 instructions say to request relief afterward with a reasonable-cause letter or through the penalty-relief process rather than attaching an explanation to the return. The practical cost is usually the registration you cannot renew until the Schedule 1 is in hand.
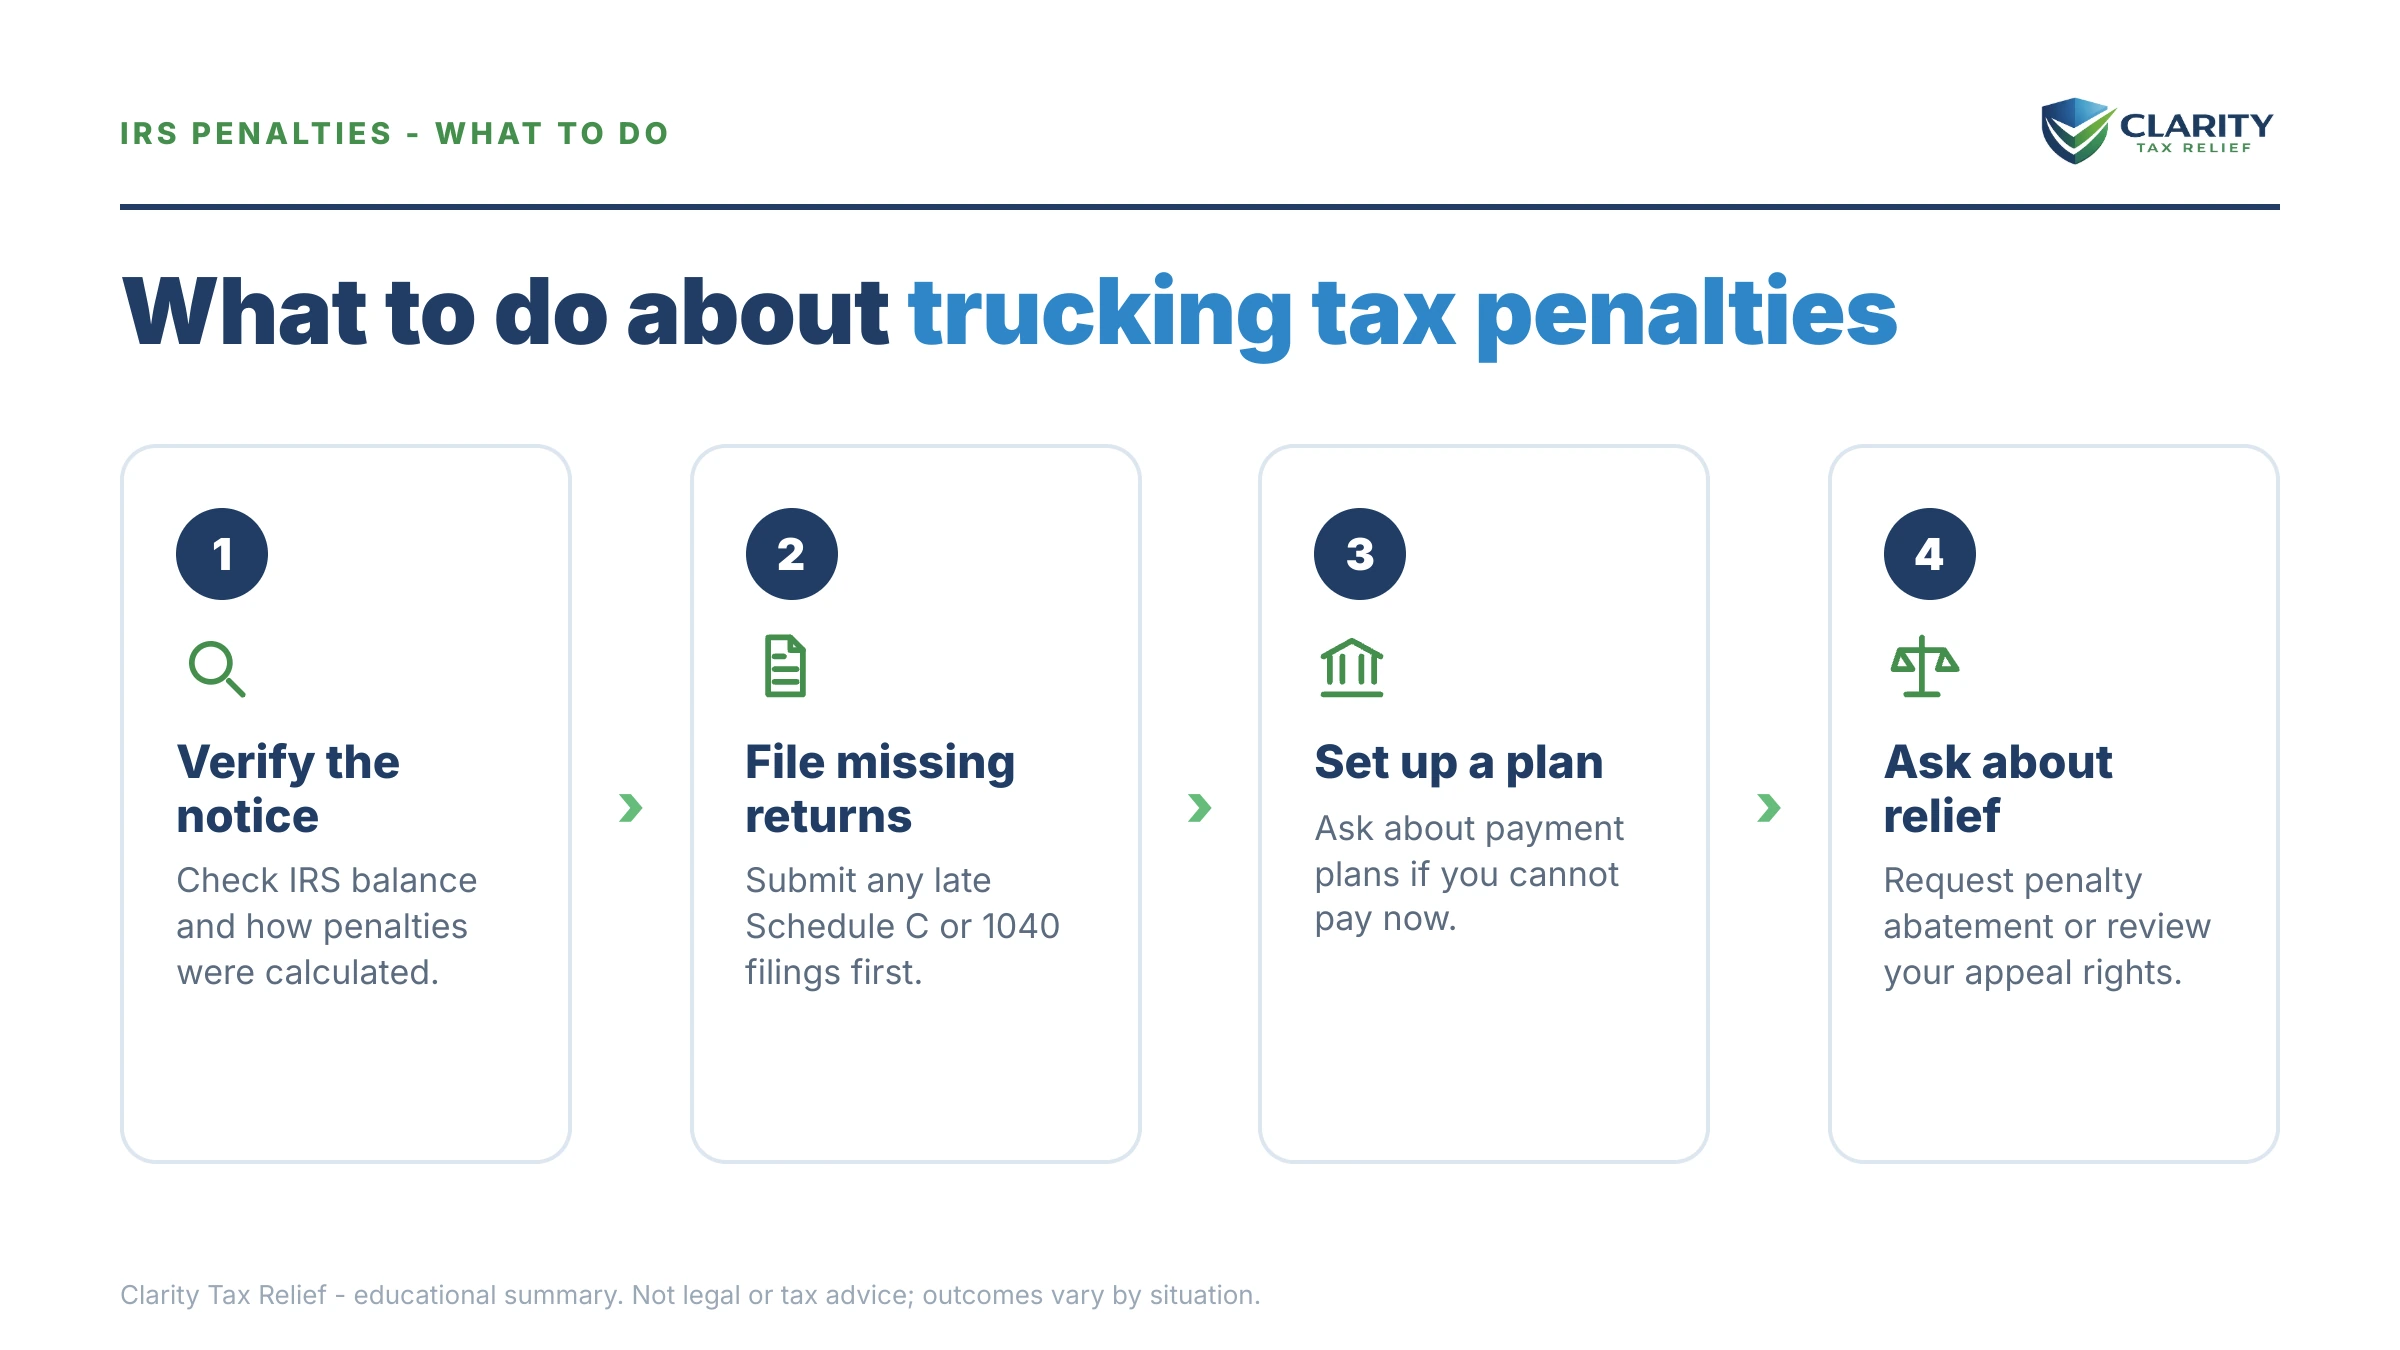
How to respond, step by step
- Pull your records. Settlement statements, fuel-card reports, 1099-NEC forms, and your IRS wage and income transcript for each year, so you see what the IRS already has on file.
- File every missing return with a full Schedule C claiming fuel, repairs, tires, insurance, depreciation and the transportation-worker per diem. This stops the 5%-a-month file penalty and usually cuts the tax.
- File any late Form 2290 if your truck is 55,000 pounds or more, so you get the stamped Schedule 1 and that penalty stops growing.
- Request penalty relief. First-time abatement for a clean year that is still under the old rules, or reasonable cause with documentation.
- Set up the right payment path before the IRS reaches the final-notice stage: a plan, Currently Not Collectible, or an offer if the numbers support one.
- Fix the current year. Start quarterly payments at 100% of last year's tax, divided by four, so you never rebuild the same debt.
When you can handle this yourself, and when to get help
You can do this alone if you missed one year, the number is small and your books are clean. Filing the return, requesting first-time penalty abatement and setting up an online payment plan for a balance under $50,000 is a manageable afternoon. Start with quarterly estimated taxes 101 so the problem does not repeat.
Experienced help changes the outcome when you have several unfiled years, the IRS has already filed a Substitute for Return, your records are gone, you owe well into five figures, a levy has already hit your operating account, or an Offer in Compromise is a real possibility on the numbers. In those cases the order you fix things, returns first, then penalties, then the balance, decides what you end up paying. Clarity Tax Relief reviews owner-operator cases for free and tells you which of those situations you are in before you spend anything.
Terms on your notice, decoded
Self-employment (SE) tax: the 15.3% Social Security and Medicare tax on your net profit, the part an employer would normally split with you.
Estimated tax: the four payments a year (Form 1040-ES) a 1099 owner-operator makes in place of withholding; skipping them triggers the underpayment penalty.
Safe harbor: the paid-in amount (90% of this year's tax, or 100% of last year's, 110% for higher incomes) that makes the underpayment penalty zero.
Form 2290 / HVUT: the Heavy Highway Vehicle Use Tax you file and pay yearly on a truck with a taxable gross weight of 55,000 pounds or more; the stamped Schedule 1 is your proof for registration.
Substitute for Return (SFR): a return the IRS files for you using only reported income and no deductions, which almost always overstates your tax.
Failure-to-file vs. failure-to-pay: two separate penalties. Filing late costs 5% a month; paying late costs 0.5% a month.
AEP: Automatic Exemption from Penalty, the IRS program, starting summer 2026, that waives the penalty during processing for filers with three clean prior years and is phasing out request-based first-time abatement.
Owner operator tax penalty questions, answered
How much are IRS penalties for an owner operator?
The two biggest penalties for owner-operators are failure to file, at 5% of the unpaid tax per month up to 25%, and failure to pay, at 0.5% per month up to 25%. Filing late costs ten times more per month than paying late, so the single worst move is not filing. On top of those, most owner-operators also pay the estimated-tax underpayment penalty for skipped quarterlies, and interest compounds daily at 7% a year as of the fourth quarter of 2026.
What is the penalty for not paying quarterly taxes as an owner operator?
There is no flat fee. The estimated-tax underpayment penalty works like interest charged on each quarter you underpaid, using the IRS underpayment rate, and it is figured on Form 2210. It applies even if you pay the full balance by April 15. You owe none of it if your return shows a balance under $1,000, or if you paid in at least 90% of this year's tax or 100% of last year's (110% if last year's AGI was over $150,000).
Do owner operators have to file Form 2290?
Yes, if the truck has a taxable gross weight of 55,000 pounds or more. The tax period runs July 1 to June 30, and the return is due by the last day of the month after the truck's first use in that period, so August 31 for a truck on the road in July. Filing late adds a late-filing penalty, a late-payment penalty and interest, and your state will not register the truck without the stamped Schedule 1 that proves the tax was paid.
Can owner operator penalties be removed?
Often, yes. If your prior three years were clean, first-time penalty abatement can remove a year's failure-to-file and failure-to-pay penalties on 2024 returns and on 2025 returns processed before the IRS switched to its new Automatic Exemption from Penalty program in the summer of 2026. Under AEP the same relief can be applied during processing with no request, for eligible returns processed after it starts in summer 2026. Reasonable-cause relief may apply if illness, a serious accident, or records lost in a truck fire or theft kept you from filing.
Why do owner operators owe so much in back taxes?
Because settlement checks and 1099s arrive with zero tax withheld, and on top of income tax you owe 15.3% self-employment tax on your net profit. A driver netting $60,000 owes roughly $8,500 in self-employment tax before a dollar of income tax, and if quarterlies were skipped the whole amount lands at once. Missed deductions such as fuel, per diem, maintenance and depreciation often mean the IRS's version of your income is far higher than reality.
Can I still deduct fuel, per diem, and repairs on back tax returns?
Yes. Filing a real Schedule C for the missing years almost always beats letting the IRS estimate your tax, because you can claim fuel, tires, repairs, insurance, truck depreciation and the transportation-worker meal allowance, which Publication 463 set at $80 a day for 2025 with 80% of it deductible for drivers under DOT hours-of-service limits. Those deductions cut the tax, and therefore every percentage-based penalty with it. Settlement statements, fuel-card reports and ELD logs can rebuild most of the record.
What happens if an owner operator never files?
The IRS can file a Substitute for Return using only the 1099 income it has, with no deductions and no per diem, then assess the tax, the full 25% failure-to-file penalty, the failure-to-pay penalty and interest. From there the notices escalate toward levies on your bank account and on money brokers or carriers owe you. Filing your own accurate return replaces the substitute figures and almost always lowers the balance.
Can the IRS take my truck for back taxes?
It is legally possible but uncommon, because seizing the equipment you earn your living with is a last resort the IRS avoids when a payment arrangement is available. The far more likely enforcement is a levy on your bank account, which freezes the funds for 21 days before they go to the IRS, or a levy served on a broker, factoring company or carrier that owes you money. A payment plan or hardship status stops that enforcement while you catch up.
Your next 24 hours
- Find the numbers. Locate your 1099s and settlement statements for each unfiled or unpaid year. That is what the IRS is measuring you against.
- Gather the deductions. Pull fuel-card reports, repair invoices, insurance, truck payment and depreciation records, and your days-on-the-road log for per diem. This is what shrinks the tax and every penalty stacked on it.
- Get a free case review. The failure-to-file penalty adds 5% every month a return stays unfiled, so use the 2-minute form or call (888) 825-7779 and we will map which years to file, which penalties can come off, and your realistic monthly number.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.
Primary sources: IRS failure to file penalty, IRS failure to pay penalty, IRS underpayment of estimated tax penalty, Instructions for Form 2290, About Form 2290, IRS Trucking Tax Center, IRS Publication 463, IRS estimated taxes, IRS payment plans, IRS: Automatic Exemption from Penalty, IRS.gov/payments