Business & Payroll Tax Debt
Personally Liable for Payroll Taxes? Who the IRS Holds Responsible in 2026
The short answer: yes — the IRS can hold you personally liable for payroll taxes. Under IRC §6672, it assesses the trust-fund portion of unpaid 941 taxes — employee withholding plus the employees' FICA share — against any "responsible person" who willfully failed to pay it over. No LLC or corporation blocks this Trust Fund Recovery Penalty.
This guide covers personal liability for a business's unpaid payroll taxes: why the IRS can reach past the company to you, the two-part legal test it has to meet, how it builds the case from the Form 4180 interview to Letter 1153, what happens if the proposal goes unanswered, your options at each stage, and the order to handle them in. The business fell behind on its payroll deposits, and now the letters have your name on them. You rent, your paycheck is the whole safety net, and someone from the IRS wants to know who signed the checks. Personal liability has a strict two-part test, a formal proposal stage, and a hard 60-day window to fight it.
One thing to know right away: the IRS cannot put a dime of this on your personal account without first sending you a specific letter, Letter 1153. The image below shows what that proposal looks like and where to look for the parts that matter.
⏱ Your deadline: you have 60 days from the date on Letter 1153 to file a written protest before the Trust Fund Recovery Penalty is assessed against you personally. If it is already assessed, the next hard clock is the 30-day window on a final notice of intent to levy. Interest accrues on the assessed amount the whole time.
Why can the IRS reach past your business for payroll taxes?
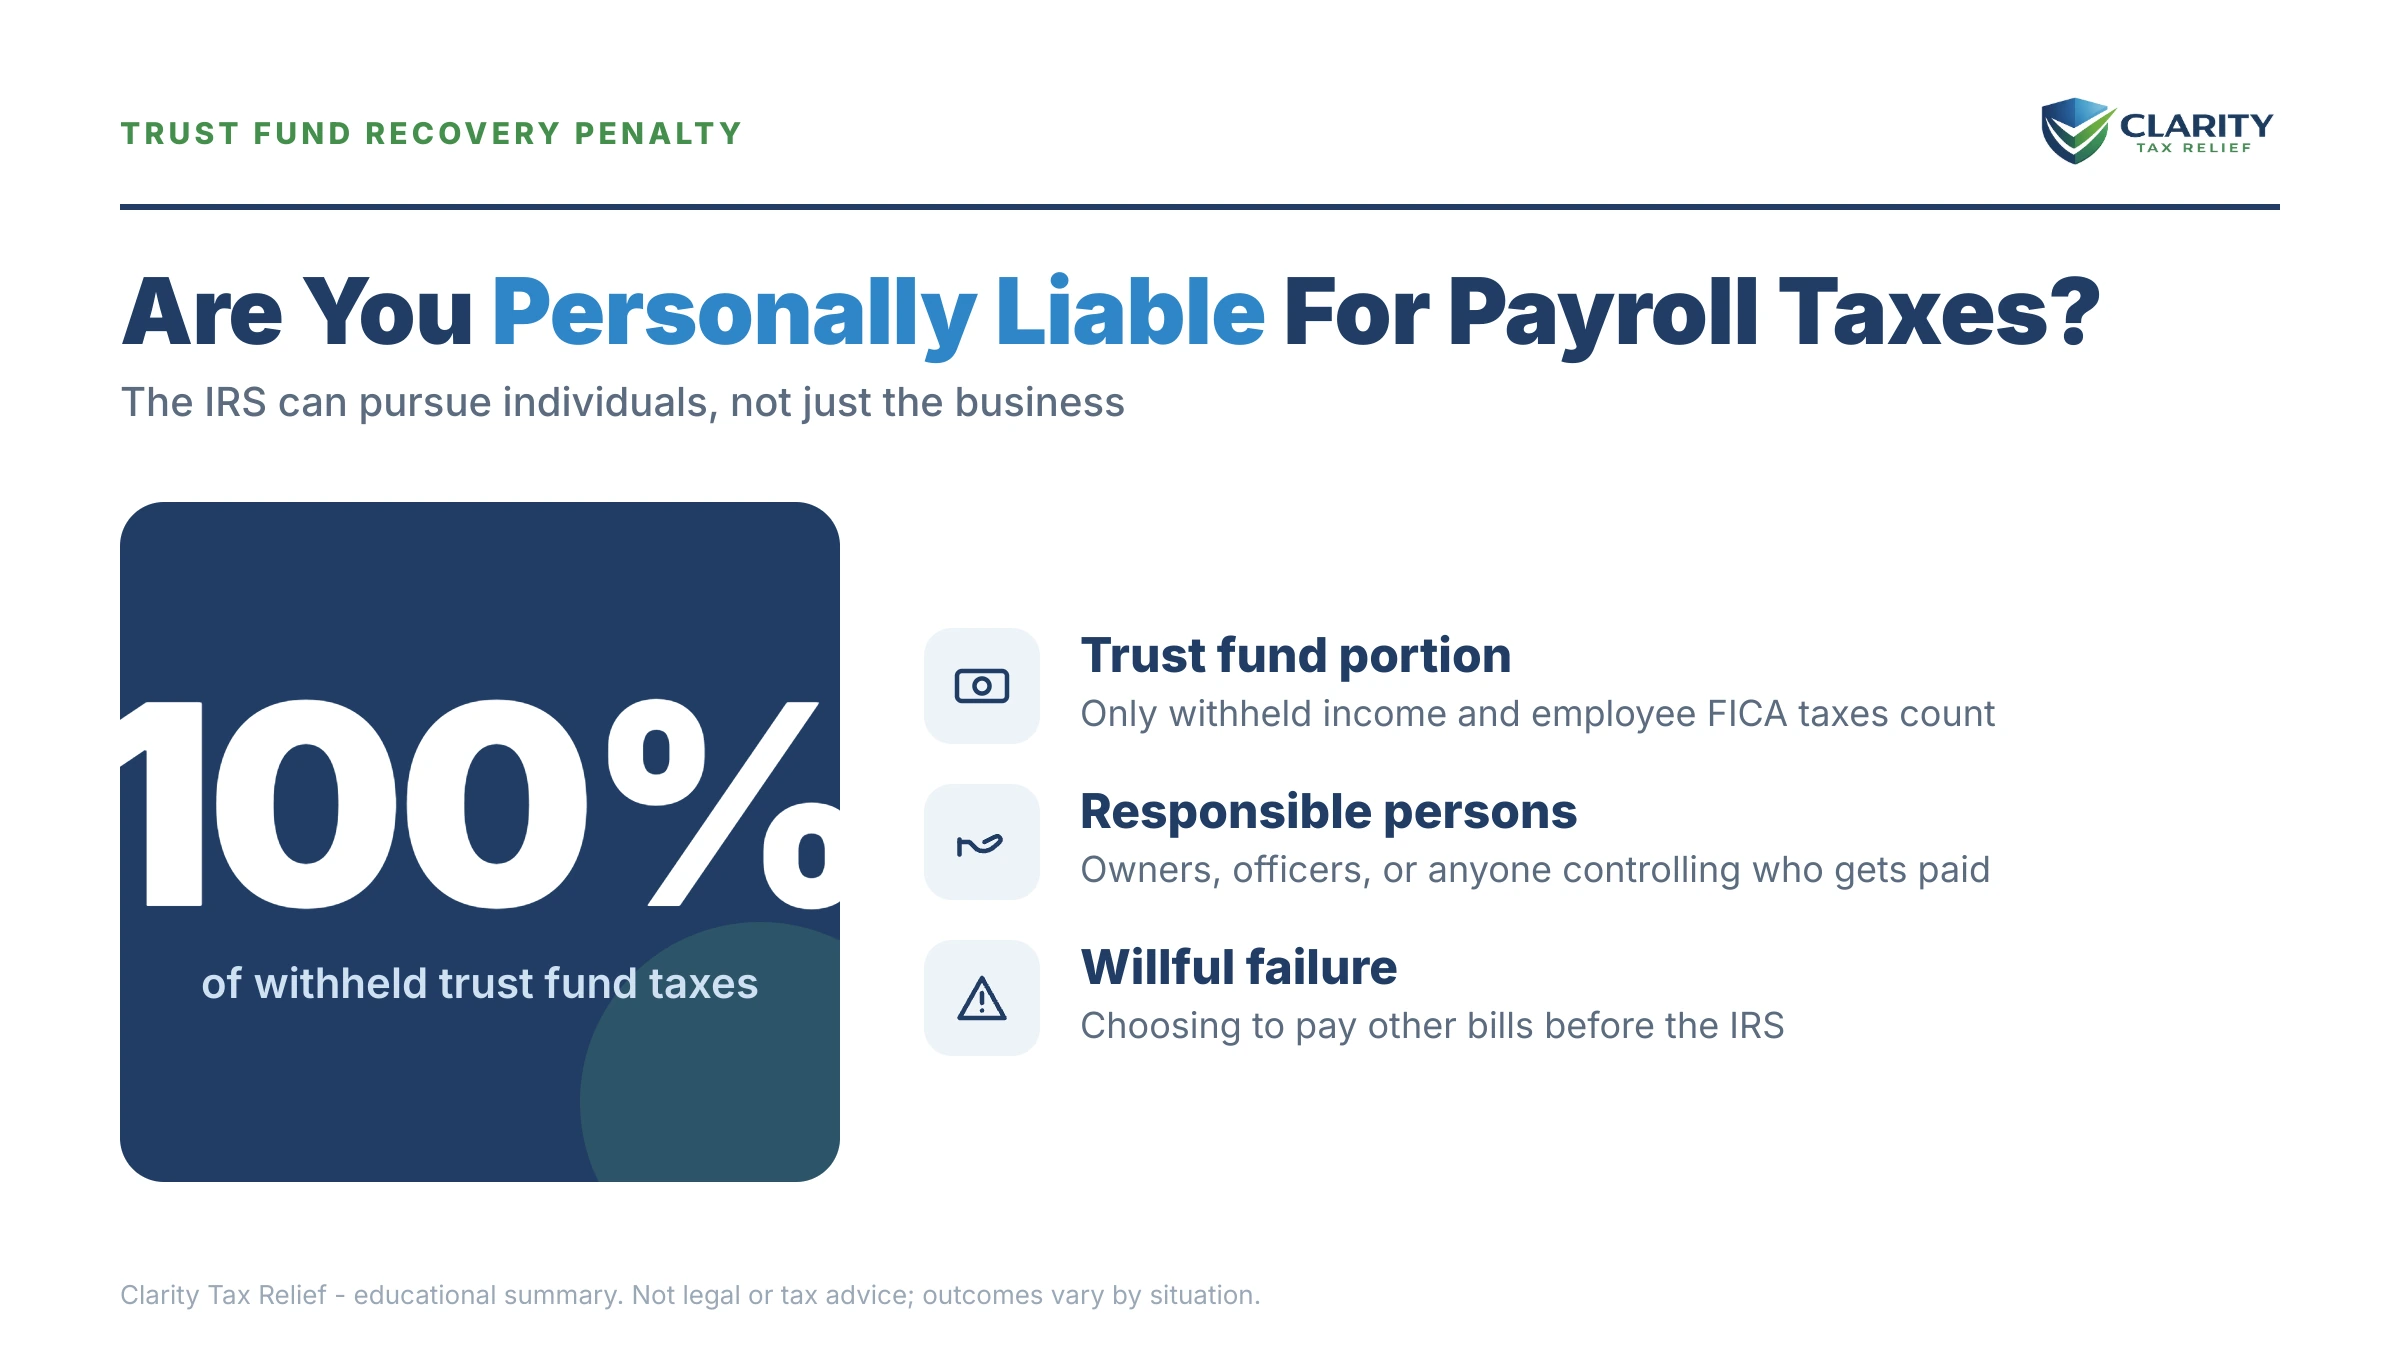
The IRS can collect the trust-fund portion of unpaid payroll taxes directly from individuals because that money was never the business's to spend. Every 941 balance splits into two very different pieces.
The first piece is money taken out of employees' paychecks: their withheld federal income tax and their 7.65% share of Social Security and Medicare. The law treats those dollars as held in trust for the United States from the moment payroll runs. When they are not deposited, the government views it less like an unpaid bill and more like spending someone else's money.
The second piece belongs to the business alone: the employer's matching FICA, failure-to-deposit penalties, and the interest that grew on the business account. It can never be assessed against you individually. If you are sorting out which tax went unpaid in the first place, our guides to 941 back taxes and 941 vs 940 back taxes cover the business side. This page covers what happens when the debt jumps to a person.
The legal tool for that jump is the Trust Fund Recovery Penalty (TFRP) under Internal Revenue Code §6672. Despite the word "penalty," it is no extra charge. It is a duplicate assessment of the trust-fund dollars against individuals, so the IRS has more than one pocket to collect from. The full anatomy of the penalty itself lives in our trust fund recovery penalty guide.
“You must deposit and report federal income tax and Additional Medicare Tax withheld and both the employer and employee social security and Medicare taxes.”
— Employment taxes (IRS.gov)
Who is personally liable for payroll taxes?
You are personally liable for payroll taxes only if you were both a "responsible person" and "willful," and the IRS must prove each prong. Titles do not decide either one. Control does.
Responsible means you had the status, duty, and authority to decide which creditors got paid. Could you sign checks? Hire and fire? Direct which bills were paid when cash was short? A minority owner who controlled the bank account can be responsible while a 50% owner who never touched the money is not.
Willful does not mean malicious. It means you knew (or recklessly ignored) that the taxes were unpaid and let other payments go out anyway. Paying rent, suppliers, or net payroll while the withholding sat unpaid is willfulness in the IRS's eyes, even if you were trying to keep the business alive. No fraud, no bad intent, no personal benefit is required.
In practice, investigators often propose the penalty against everyone with signature authority and let the protest process sort out who had control. Being named is not the same as being liable. That is exactly why the 60-day protest matters.
| Role | Typical TFRP exposure | What the IRS examines |
|---|---|---|
| Owner, officer, or member-manager | High — the default target | Bank signature cards, canceled checks, who directed payments in the shortfall quarters |
| CFO, controller, or general manager | High if they controlled cash | Authority to prioritize creditors; knowledge of the unpaid 941s |
| Bookkeeper or office manager with check authority | Real risk, often overreached | Whether they followed orders or made payment decisions — see bookkeeper personally liable IRS |
| Outside payroll company | Provider rarely assessed. You usually remain liable for the tax | Who funded the deposits; whether the provider diverted funds |
| Passive investor or silent partner | Low unless they stepped into payment decisions | Board minutes, loan guarantees, any hands-on cash control |
| Family member merely added to the bank account | Low to moderate — signature authority alone isn't enough, but it invites scrutiny | Whether any checks were actually signed and who directed them |
How does the IRS build the case, from Form 4180 to Letter 1153?
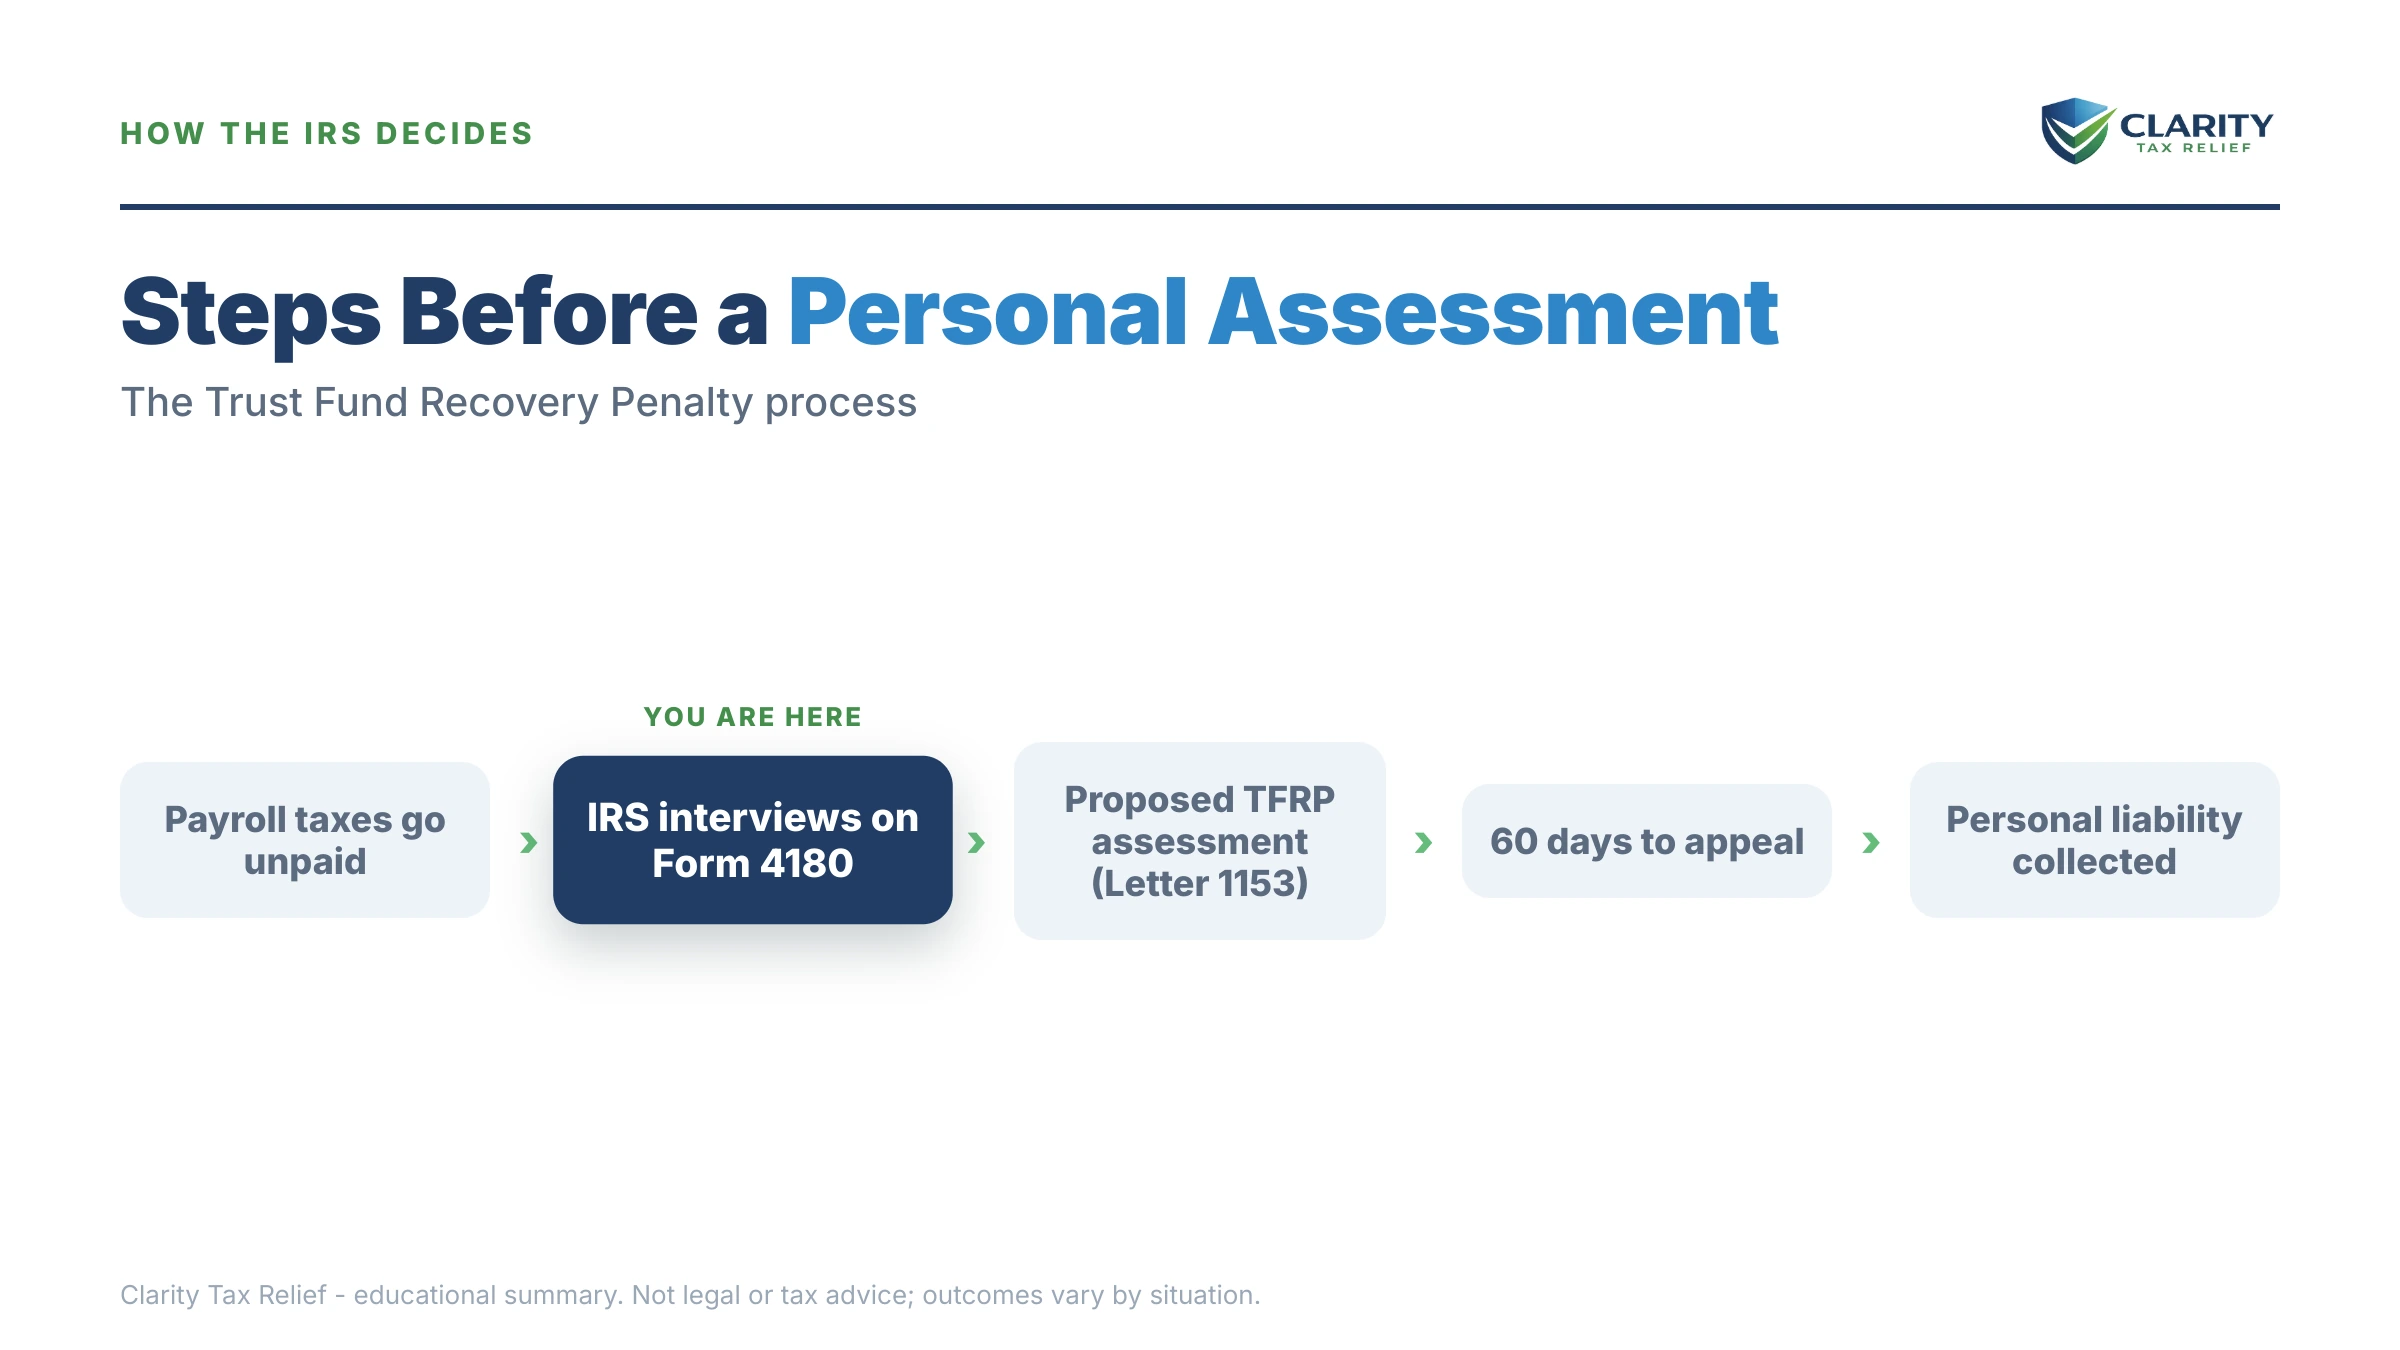
The TFRP process runs through a personal interview and a formal written proposal before anything reaches your account. Because unpaid payroll taxes are a collection priority, a human revenue officer usually drives it rather than the automated notice stream alone.
The centerpiece is the Form 4180 interview: a structured questionnaire about who signed checks, who authorized payroll, and who knew the deposits were missed. It feels like paperwork. It is the evidence file for the responsibility and willfulness findings. You are allowed representation, and you are allowed to prepare. Do both.
If the officer concludes you are liable, you receive Letter 1153 proposing the penalty, with Form 2751 attached showing the exact dollar figure. That is the document pictured below. Check the date at the top, because your 60-day protest window runs from it. Check the proposed amount too, because it should equal only the trust-fund portion, never the whole 941 balance. Protest in time and an independent Appeals officer reviews the case before assessment. Miss the window and the penalty posts to your personal account with no exam-stage appeal.
What happens if you ignore the Trust Fund Recovery Penalty?
An ignored TFRP proposal becomes a personal tax debt the IRS collects like any other: from your paycheck, your bank account, your refunds. The sequence runs in stages:
- Investigation. The revenue officer pulls bank records and requests Form 4180 interviews. Silence here does not stall the case. The officer decides on the records alone.
- Letter 1153 proposal. Your one pre-assessment chance to contest liability. The 60-day protest window starts on the letter's date.
- Assessment. The trust-fund amount posts to your personal account as a civil penalty, jointly and severally, meaning every responsible person owes 100% until it is paid once.
- Personal collection notices. Balance-due bills arrive in your name, with interest compounding on top.
- Final notice of intent to levy. An LT11 or Letter 1058 starts a 30-day clock and your Collection Due Process rights (requested on Form 12153).
- Levy. A bank levy freezes funds for 21 days before they are sent. A wage levy is continuous until released, taking most of each paycheck above a small exempt amount.
If you rent, that last stage is the whole ballgame. There is no house for a lien to sit quietly against. Your paycheck and checking account are the collectible assets, so levies arrive faster and bite harder. You can estimate what a wage levy would leave you with using our IRS wage garnishment calculator.
One more escalation to know about. If the business keeps withholding from paychecks quarter after quarter while never depositing it, the IRS calls that pyramiding payroll taxes, and that is where civil cases start drawing criminal attention. Stopping the bleeding now matters as much as fixing the past.
The IRS wants to put payroll taxes on you personally?
Get your Letter 1153, Form 4180 request, or revenue officer letter reviewed free, before the 60-day protest window closes. An experienced tax professional will tell you whether you actually meet the responsible-person test and what your strongest move is.
What are your options at each stage?
Your best option depends on whether the penalty is proposed, assessed, or already in collection, and the earlier the stage, the cheaper the fix. The general mechanics of payment plans, hardship status, and offers are covered in our guide to how to settle tax debt yourself. Here is what changes when the balance is a TFRP.
| Option | Who qualifies | Cost / key limit |
|---|---|---|
| Written protest of Letter 1153 | Anyone named — must file within 60 days of the letter date | Free; keeps the penalty off your account during Appeals review |
| Designated voluntary payments (business still open) | Business making voluntary (not levied) payments, designated in writing to the trust-fund portion | Each designated dollar shrinks what can ever be assessed against you |
| Installment agreement on the assessed penalty | Balances ≤ $50,000 can set up online for up to 72 months; the guaranteed installment agreement applies only to individuals with an income-tax balance of $10,000 or less (excluding penalties and interest) who have filed all returns, filed and paid on time for the past 5 years with no installment agreement in that period, and can pay in full within 3 years | Setup fee varies; interest keeps accruing while you pay |
| Currently Not Collectible | Paying anything would leave you unable to cover basic living costs (proven on Form 433-F) | $0; pauses levies but the debt and interest remain |
| Offer in Compromise | Assets plus future income genuinely can't cover the balance before the CSED | $205 fee (waived if AGI ≤ 250% of poverty); roughly 1 in 5 offers accepted in FY2024 |
| Post-assessment defense / abatement | You can show you weren't responsible or weren't willful | See trust fund recovery penalty defense and trust fund penalty abatement |
| Collection statute expiration | Everyone — 10 years from your personal assessment date | Clock pauses during OIC, bankruptcy, and certain appeals; not a strategy by itself |
Two of these deserve emphasis. First, the designated payment move. While the business is operating and the TFRP has not been assessed, any voluntary payment can be directed in writing to the trust-fund portion of the oldest quarter. Levied funds and required deposits cannot be designated. Voluntary ones can, and they directly reduce your personal exposure.
Second, know that the TFRP is itself a penalty, so the usual penalty-relief playbook (first-time abatement, and the Automatic Exemption from Penalty rolling out in summer 2026) does not erase it. "Abating" a TFRP means proving the liability should not attach to you at all. That is a liability argument rather than a forgiveness request.
A worked example: how $6,200 lands on you personally
Say your small business missed two quarters of 941 deposits and owes $9,860 total. During those quarters it paid $40,000 in gross wages, withholding $3,140 in federal income tax and $3,060 in the employees' 7.65% FICA share. The math splits like this:
- Trust-fund portion (can follow you personally): $3,140 withheld income tax + $3,060 employee FICA = $6,200
- Business-only portion: $3,060 employer matching FICA + roughly $600 in deposit penalties and interest ≈ $3,660. This stays with the entity, period
If the IRS assesses that $6,200 against you and you are a renter earning $4,200 a month, there is no home equity to chase. A levy targets your paycheck (continuous until released) or your checking account (funds held 21 days, then gone). The same $6,200 on a payment plan looks very different: even stretched over 72 months it is roughly $86 a month before accruing interest. The guaranteed installment agreement has strict conditions. It is available only to individuals with an income-tax balance of $10,000 or less excluding penalties and interest, with all returns filed, timely filing and payment for the past 5 years with no installment agreement in that period, and full payment within 3 years. Most people in this range resolve it in a year or two. The gap between "levied" and "$86 a month" is entirely about who moves first.
How to respond to personal payroll tax liability, step by step
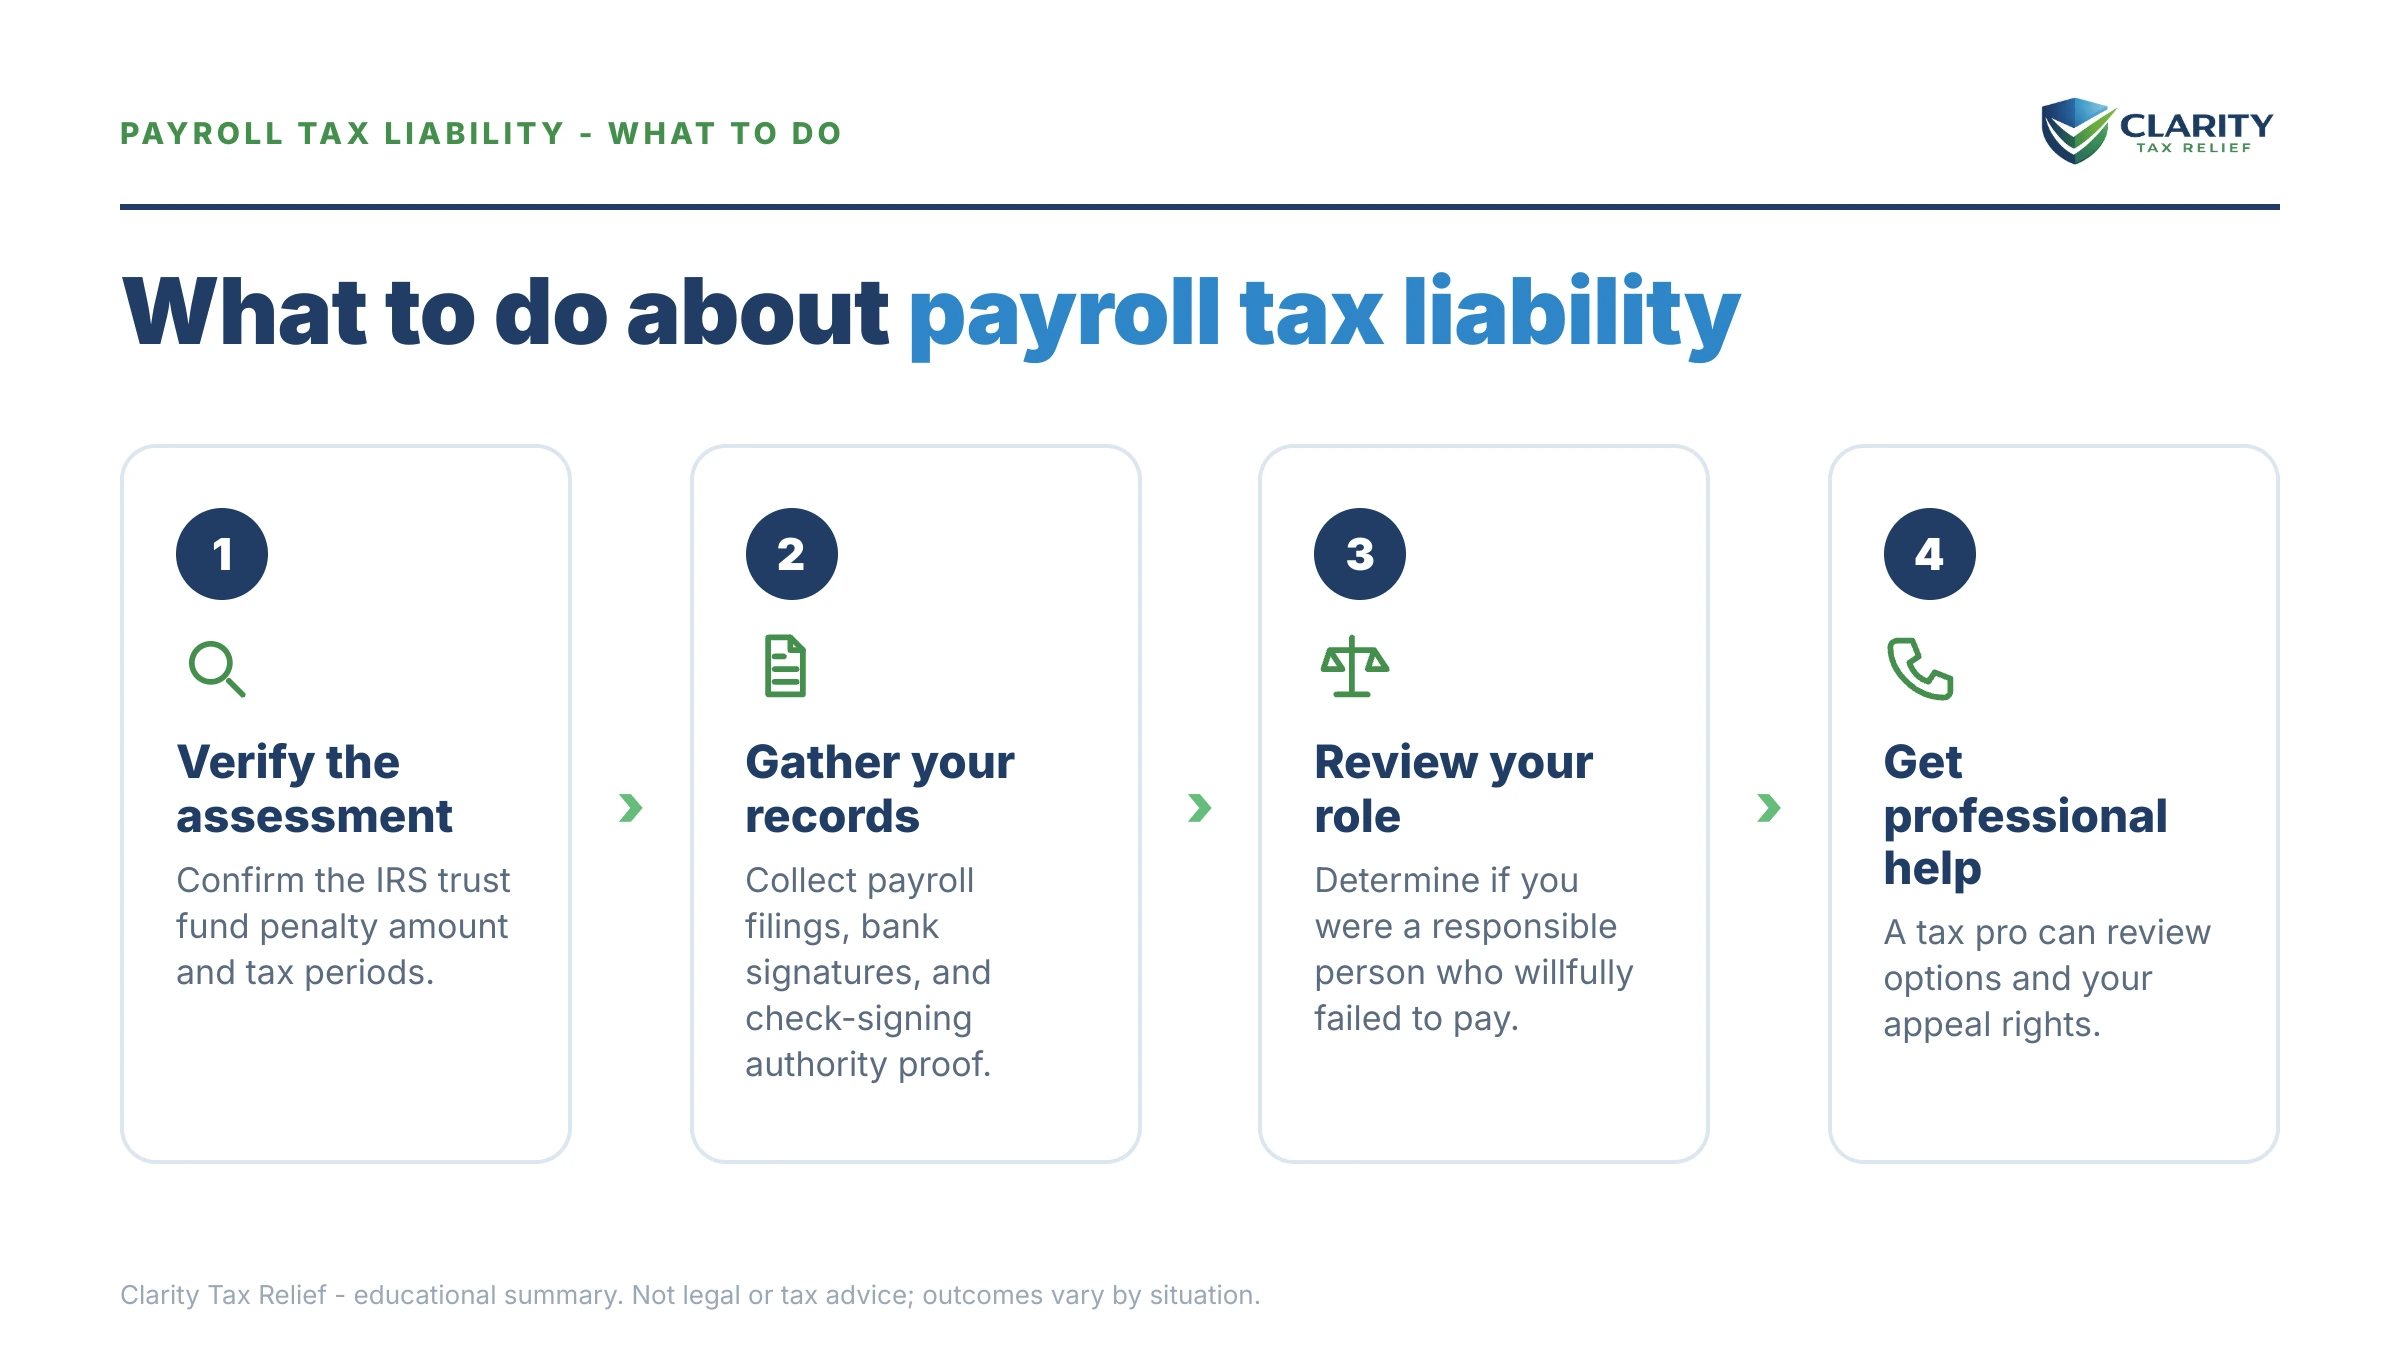
- Identify your stage. Pull your IRS account transcript and sort your mail. Questions from a revenue officer mean investigation, Letter 1153 means proposal, and a personal balance labeled civil penalty means the TFRP is already assessed.
- Do not sit for a Form 4180 interview cold. Every answer becomes evidence on responsibility and willfulness. Ask to reschedule and get experienced representation before you answer anything on the record.
- Protest Letter 1153 within 60 days. A written protest keeps the penalty off your personal account while IRS Appeals reviews whether you were responsible and willful.
- Gather control evidence. Bank signature cards, canceled checks, payroll approvals, meeting minutes, and your written job description show who decided which bills got paid, and who did not.
- Resolve any assessed balance before levy notices land. Set up a payment plan, document hardship, or test offer eligibility. The goal is a resolution in place before a final notice starts the 30-day levy clock.
Red flags in a payroll tax case
Each of these changes what you should do this week. Check your file against the list before you talk to anyone at the IRS.
- A Form 4180 interview is scheduled and you have no representative. Your answers become the evidence file. Reschedule first.
- Letter 1153 is dated and the 60 days are running. The protest is free and keeps the penalty off your account during Appeals review. Nothing after this stage is as cheap.
- Form 2751 shows the whole 941 balance. Only the trust-fund portion can be assessed against you. Employer FICA, deposit penalties, and interest stay with the business.
- You signed checks on someone else's instructions. That is a responsibility defense, and the one most often talked away in an unrepresented interview.
- The business is still withholding and still not depositing. Pyramiding draws criminal attention. Stop it now.
- An LT11 or Letter 1058 has arrived in your name. The 30-day Collection Due Process clock is running, and a wage levy is continuous until released.
- The company is closing. Dissolution pushes the IRS toward the individuals faster, because the corporate pocket is empty.
Which three situations change the answer?
You were an employee, not an owner. Signing checks on instructions is not the same as deciding which creditors got paid. Non-owners have the strongest liability defenses, and they are also the people most likely to sign a Form 4180 unrepresented and talk themselves into an assessment. The specifics live in our guide for a bookkeeper personally liable IRS situation.
Your payroll provider took the money. If a payroll service withdrew the tax money and never deposited it, the tax is still legally yours. Provider fraud is powerful evidence against willfulness, though, and penalty relief is often available. Start with 941 penalty abatement.
The business is closed or dissolving. Shutting the doors does not shut down the TFRP. Dissolution pushes the IRS toward the individuals faster, because the corporate pocket is empty. If the entity is already gone, see payroll tax debt business closed before assuming the debt died with it.
Can you handle this yourself, or does help change the outcome?
You can reasonably self-manage if the penalty is already assessed and you agree you were the responsible person (say, sole owner and sole signer), and the balance is modest. A $6,200 assessment fits online payment-plan setup at IRS.gov payment plans in under an hour. If a levy is causing real hardship and you cannot get traction, the Taxpayer Advocate Service is a free escalation path.
Experienced help changes outcomes in four spots. Before a Form 4180 interview, where prepared answers routinely narrow who gets proposed. During the 60-day Letter 1153 window, where a documented protest can keep the penalty off your account entirely. When multiple people were assessed and the allocation is being fought. And when a levy is already in motion against a paycheck you cannot lose. Those are evidence and negotiation problems rather than paperwork problems, and the record you build in week one follows the case to the end.
Terms on your notice, decoded
The official IRS overview is at Employment taxes and the Trust Fund Recovery Penalty; here is the vocabulary in plain English:
- Trust fund taxes: money withheld from employees' paychecks (income tax plus their FICA share) that the law treats as held in trust for the government.
- Responsible person: anyone with the real authority to decide which bills the business paid, regardless of job title.
- Willfulness: knowing the taxes were unpaid and paying anyone else anyway; no bad intent required.
- Letter 1153: the formal proposal to assess the TFRP against you, starting your 60-day protest window.
- Form 4180: the IRS's responsible-person interview questionnaire; your answers become the evidence file.
- Joint and several liability: every responsible person owes 100% until the trust-fund amount is collected once, from any combination of them.
- CSED: the Collection Statute Expiration Date; generally 10 years from the date the penalty was assessed against you.
The bottom line on personal liability for payroll taxes
The IRS can only put the trust-fund portion on you, and only if it shows you were both responsible and willful. Being named on a Letter 1153 is a proposal, and the 60 days after its date are the cheapest window you will ever get. Do not answer a Form 4180 cold. Protest in writing with the control evidence. If the business is still open, designate voluntary payments to the trust-fund portion. If a balance is already assessed, get a plan or hardship status in place before a final notice starts the levy clock. Nothing here predicts how your case ends; it lays out the test and what you control at each stage.
Personally liable payroll taxes: your questions answered
Can the IRS make me personally pay my company's payroll taxes?
Yes. Under IRC §6672, the IRS can assess the trust-fund portion of unpaid payroll taxes, the money withheld from employees' paychecks, against any responsible person who willfully failed to pay it over. This is the Trust Fund Recovery Penalty, and it attaches to you as an individual, collectible from your wages, bank accounts, and future refunds.
Does an LLC or corporation protect me from payroll tax liability?
No, not for the trust-fund portion. The corporate veil protects you from most business debts, but §6672 is written specifically to reach through the entity to the individuals who controlled its money. The employer's matching share of FICA and most business penalties do stay with the business; only the withheld amounts follow you personally.
Who counts as a responsible person for the Trust Fund Recovery Penalty?
Anyone with the status, duty, and authority to decide which bills got paid — regardless of title. Owners, officers, and controllers are the usual targets. But the IRS has assessed bookkeepers, office managers, and outside accountants who had check-signing authority and knew the taxes were unpaid. Signature authority alone isn't enough; actual control over payments is what matters.
How much of the payroll tax debt can the IRS assess against me personally?
Only the trust-fund portion: federal income tax withheld from employees plus the employees' 7.65% share of Social Security and Medicare. The employer's matching FICA, failure-to-deposit penalties, and interest that accrued against the business stay with the business. In the worked example in this guide, a $9,860 business balance splits into $6,200 personal and roughly $3,660 that stays corporate.
Can more than one person be assessed for the same payroll taxes?
Yes. TFRP liability is joint and several: the IRS can assess 100% of the trust-fund amount against every responsible person at once and collect from whoever pays first. It cannot keep more than the total owed — payments by the business or by another responsible person reduce everyone's balance. That is also why proving who actually controlled the money matters so much in your defense.
Does the Trust Fund Recovery Penalty ever expire?
Generally, the IRS has 10 years from the date the penalty is assessed against you to collect it — the Collection Statute Expiration Date. The clock runs from your personal assessment date, not from when the business first fell behind. It pauses during an Offer in Compromise, bankruptcy, or certain appeals. Waiting out the statute while ignoring levy notices is rarely a workable plan on its own.
Can I settle a Trust Fund Recovery Penalty for less than the full amount?
Sometimes, but the bar is high. An Offer in Compromise on an assessed TFRP uses the same math as any personal tax debt: the IRS measures your assets and future income, charges a $205 application fee (waived with low-income certification), and accepted roughly 1 in 5 offers in FY2024. If the numbers show you could pay in full over time, an offer will be rejected — a payment plan is usually the realistic path.
Can I go to jail for unpaid payroll taxes?
The Trust Fund Recovery Penalty itself is a civil penalty, not a criminal charge. Criminal exposure arises when non-payment looks deliberate and repeated, especially pyramiding, where a business keeps withholding from paychecks quarter after quarter while never depositing the money. If you're receiving the standard civil letters and engaging with the IRS, you're in the civil lane. Get experienced help early to keep it there.
Your next 24 hours
- Find the controlling date. If you have Letter 1153, the date printed at the top starts your 60-day protest window. Count it out on a calendar today. If you have a final notice of intent to levy, the clock is 30 days.
- Pull your control evidence together. Bank signature cards, a few canceled checks from the shortfall quarters, your job description, and any Form 2751 showing the proposed amount. That stack decides how strong your case is.
- Get the proposal reviewed free. Send a photo of your letter through the 2-minute form or call (888) 825-7779. An experienced tax professional will tell you whether the responsible-person test actually fits you before the 60-day window closes.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.