IRS Notices
SSA Notice 703 Explained: The Worksheet That Shows Whether Your Social Security Is Taxable (2026)
The short answer: SSA Notice 703 is an IRS worksheet mailed with your SSA-1099, not a bill. Add half your Box 5 benefits to your other income, including tax-exempt interest. Over $25,000 (single) or $32,000 (married filing jointly), part of your benefits may be taxable.
This guide covers why SSA Notice 703 came in the same envelope as your SSA-1099, how the five-line worksheet works, what counts as other income, how much of your benefits can be taxed once you cross the line, how to stop a surprise bill with Form W-4V, and what to do if earlier years went unreported. The base amounts, worksheet lines and form revision below were checked against the November 2026 revision of Notice 703 on irs.gov on November 4, 2026.
You opened the January envelope from Social Security expecting one page, the SSA-1099, and a second page slid out with "Notice 703" in the corner and the word "taxable" in the headline. The dread is normal and the page does not deserve it. Nobody is billing you, nothing is overdue, and the whole worksheet takes about as long as a cup of coffee.
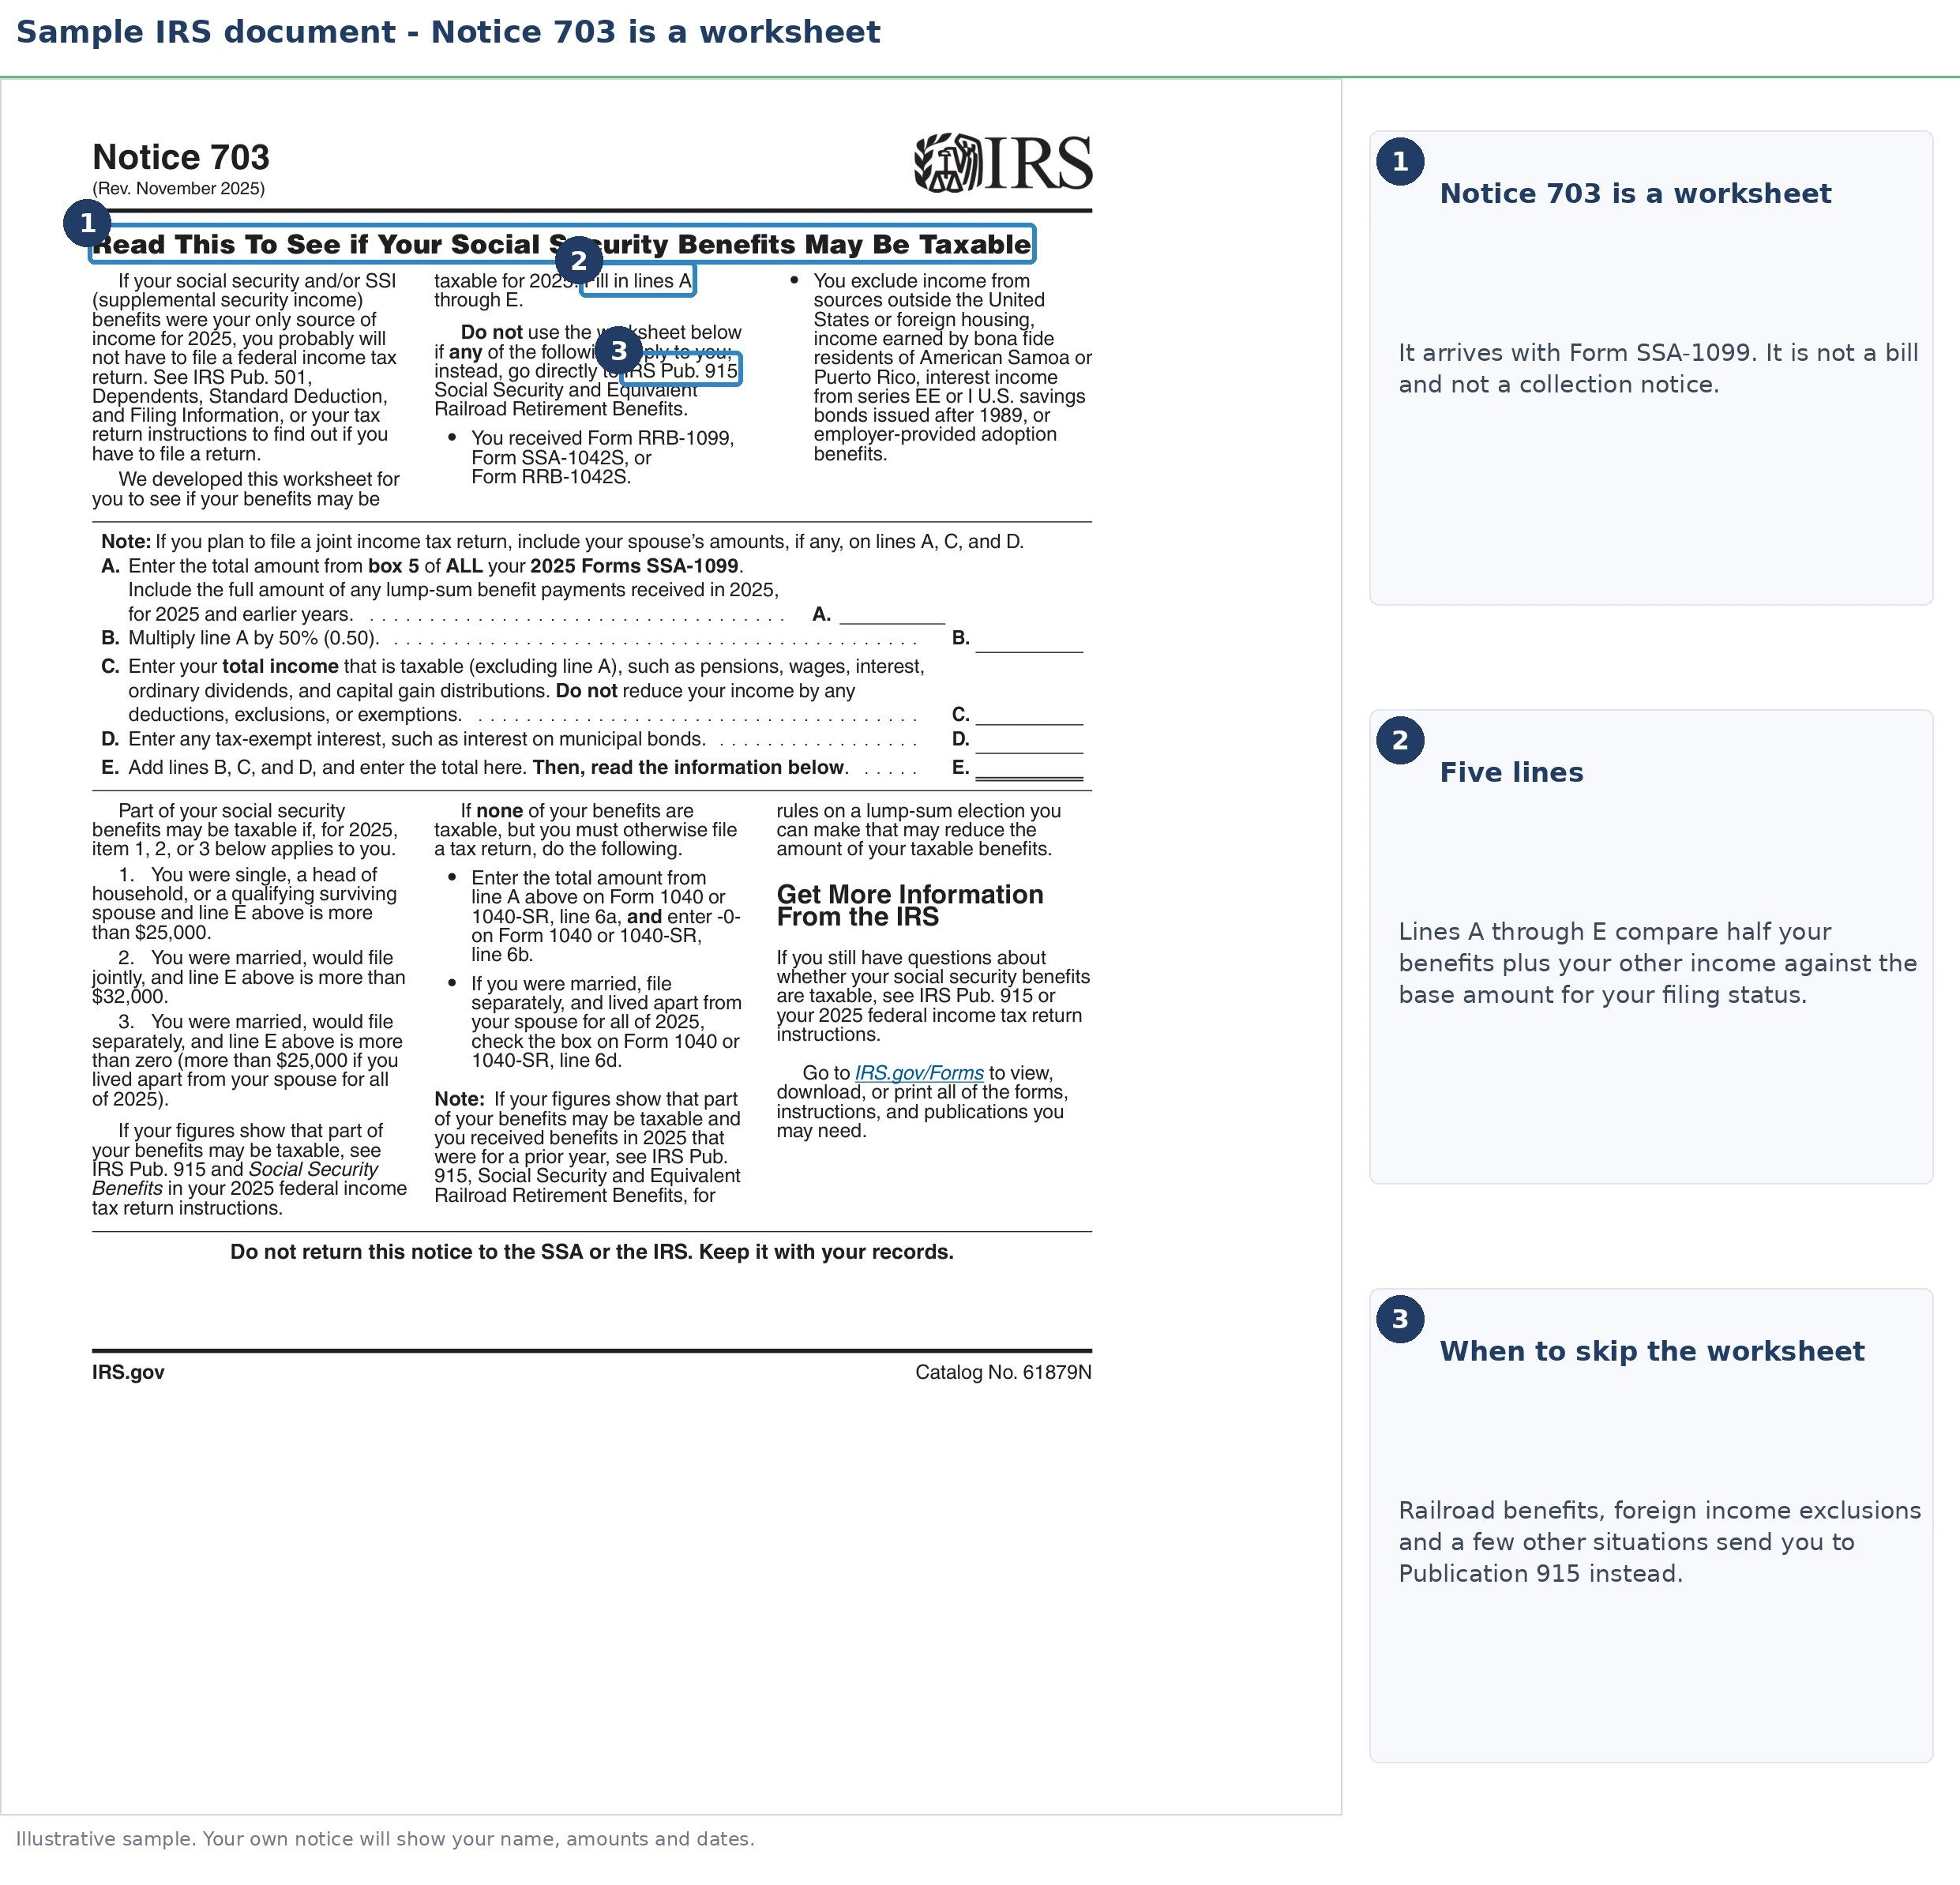
The image further down shows exactly what Notice 703 looks like, so you can match each lettered line to the one in your hand before you run the numbers.
⏱ No response deadline: Notice 703 is a worksheet, and the IRS says in print not to send it back. There is nothing to pay and no date to miss on the notice itself. The only clock that matters is the filing deadline for the year the SSA-1099 covers. If earlier years' benefits were taxable and never reported, interest on any balance the IRS later assesses is already running, month by month.
Why did SSA Notice 703 come with your SSA-1099?
Notice 703 is an IRS document, not a Social Security one, and every benefit recipient gets it. The SSA simply folds it into the January mailing with Form SSA-1099 so you can answer one question before you file: do any of my Social Security benefits need to be reported as taxable income? Receiving it says nothing about whether you owe anything, and nothing about your account has changed.
Two clarifications up front. "Social Security benefits" here means monthly retirement, survivor and disability (SSDI) benefits, the amounts in Box 5 of your SSA-1099. Supplemental Security Income (SSI) is not taxable and is not part of this calculation at all. The notice itself says that if Social Security or SSI was your only income for 2026, you probably do not need to file a return at all.
There is nothing to sign and no IRS employee waiting on your answer. The worksheet exists because the answer differs from retiree to retiree, and from year to year for the same retiree. As the worked examples below show, the same benefit check can be fully untaxed one year and partly taxable the next because of a single CD that matured or one IRA withdrawal.
How does the Notice 703 worksheet work, line by line?
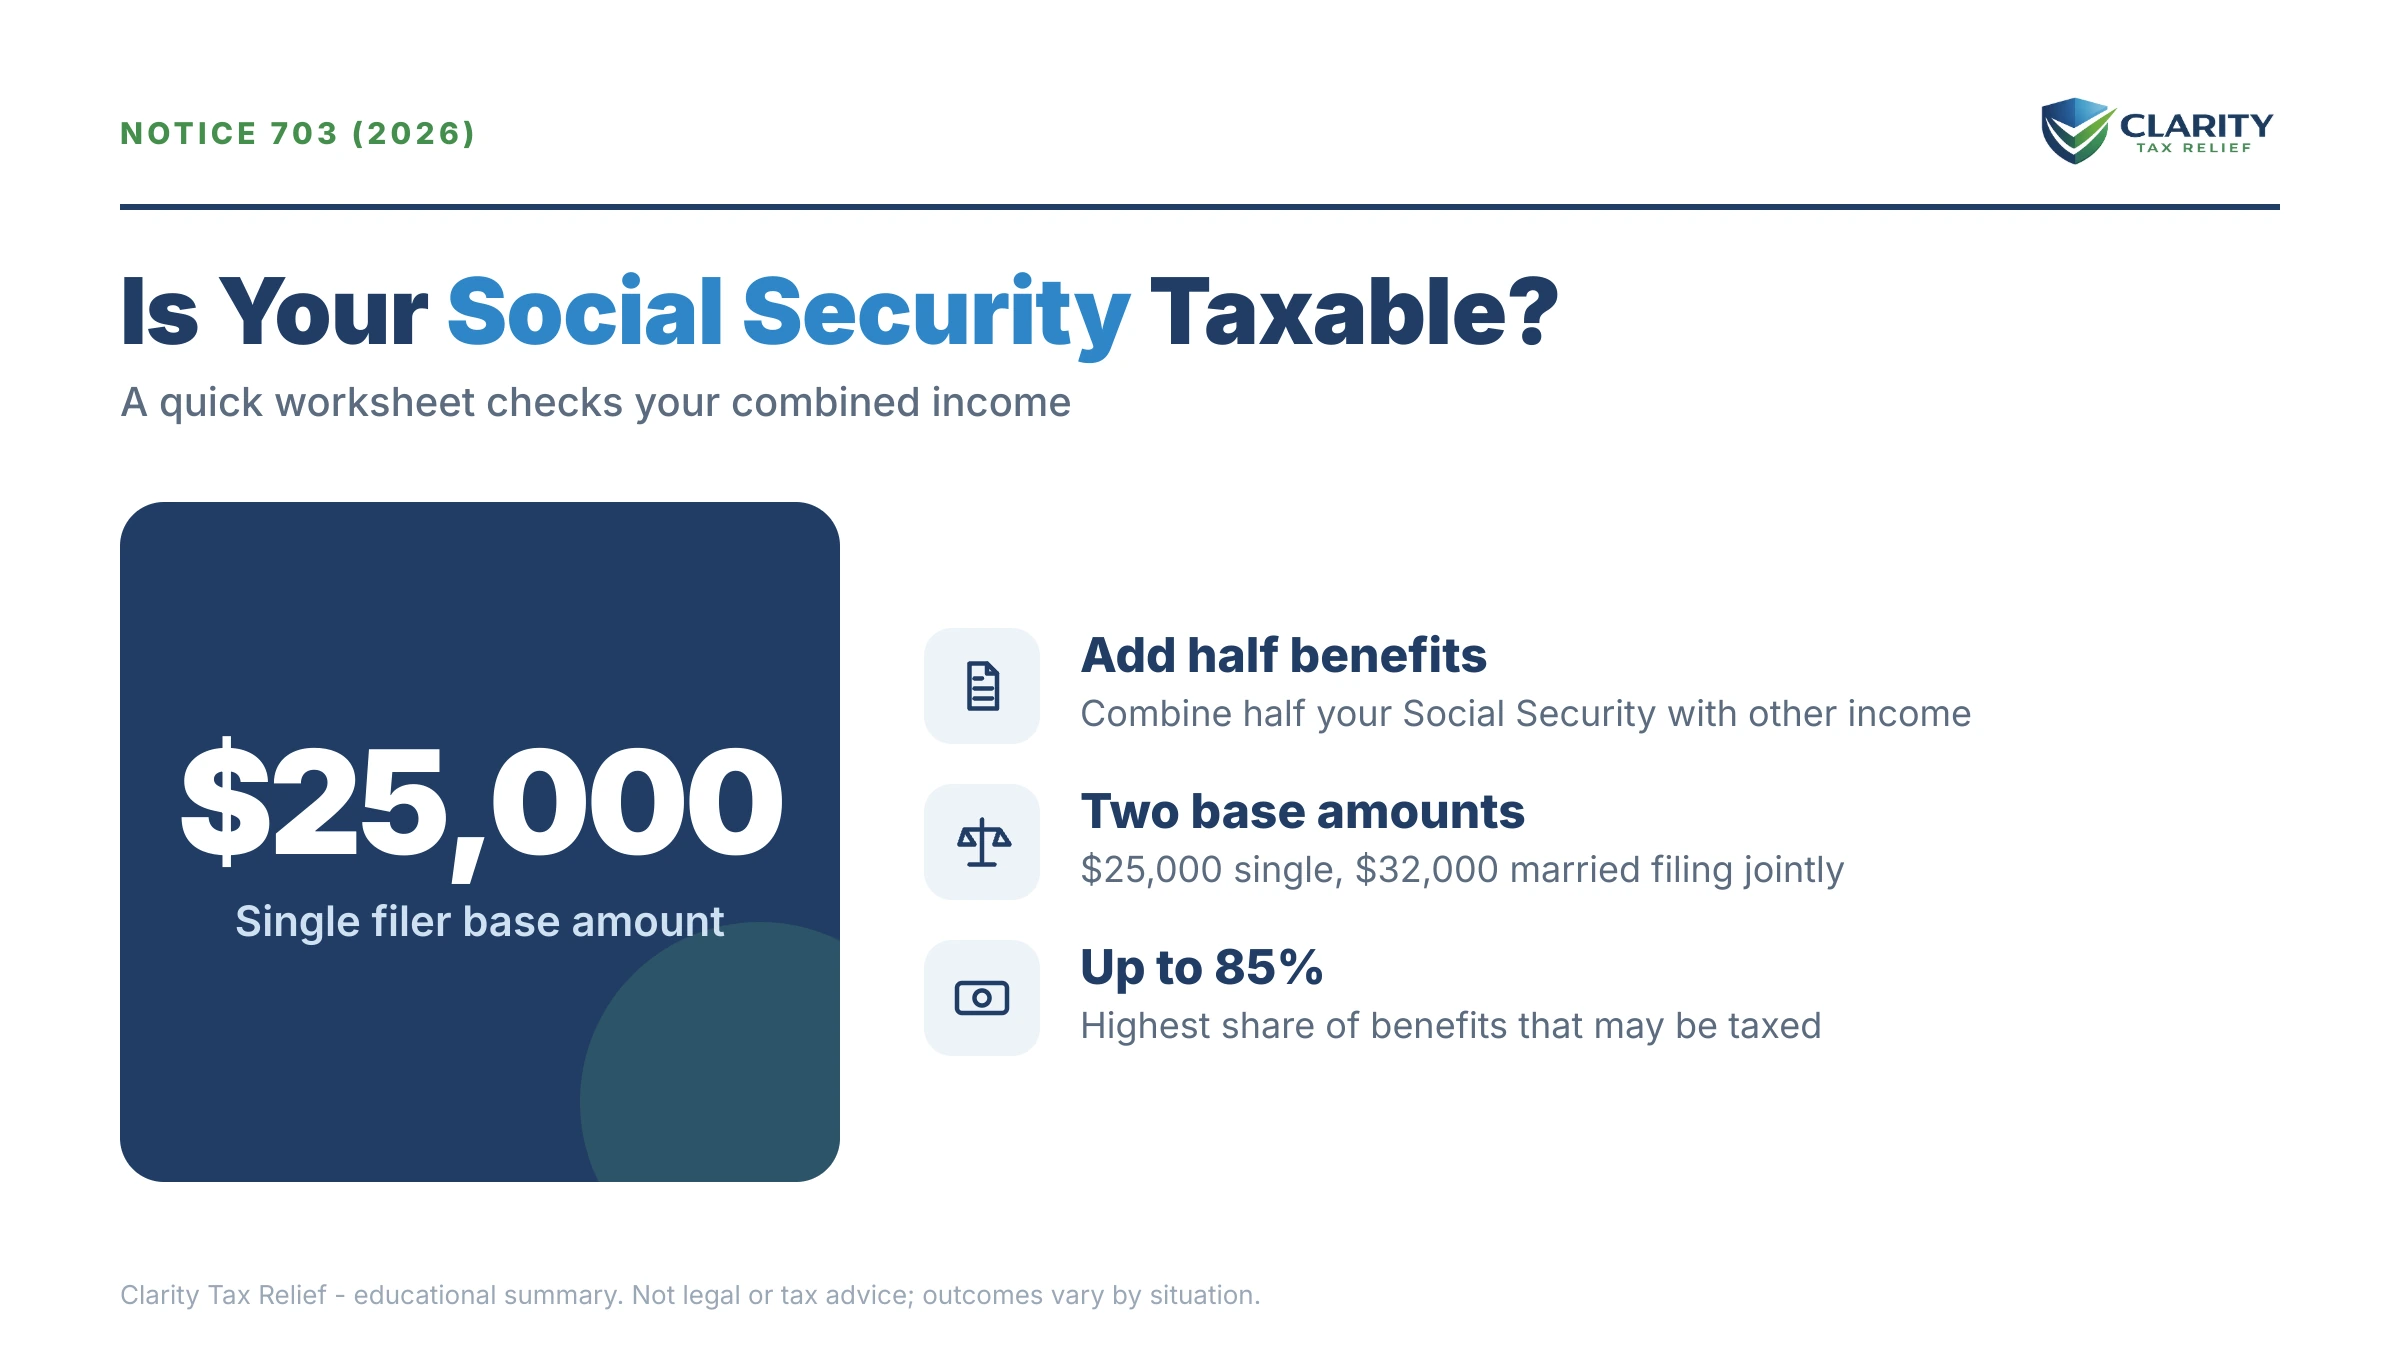
Notice 703 runs a single comparison: one-half of your benefits plus everything else you took in, measured against a base amount set by your filing status. The November 2026 revision uses five lettered lines:
| Line | What you enter | Where it comes from |
|---|---|---|
| A | Total from Box 5 of all your 2026 Forms SSA-1099, including any lump-sum payment received in 2026 for earlier years | Box 5, net benefits, on each SSA-1099 (both spouses' forms if you file jointly) |
| B | Line A multiplied by 50 percent | Your own arithmetic |
| C | All of your taxable income other than benefits: pensions, wages, interest, ordinary dividends, capital gain distributions, IRA withdrawals. Do not subtract any deductions or exclusions | 1099-R, W-2, 1099-INT, 1099-DIV, 1099-B and similar forms |
| D | Tax-exempt interest, such as municipal bond interest | Box 8 of Form 1099-INT or your brokerage statement |
| E | Lines B + C + D. This is the number you compare to your base amount | Your own arithmetic |
If line E lands at or below your base amount, none of your benefits are taxable. If it lands above, some portion may be. How large that portion is comes from the longer worksheet in Publication 915 or from your tax software, never from Notice 703 itself. The notice also tells you to skip it entirely and go straight to Publication 915 if you received Form RRB-1099 (railroad retirement), Form SSA-1042S or RRB-1042S (nonresident forms), or if you exclude foreign earned income, foreign housing, or interest from Series EE or I savings bonds issued after 1989.
| Filing status | Base amount |
|---|---|
| Single, head of household, or qualifying surviving spouse | $25,000 |
| Married filing separately, lived apart from your spouse for all of 2026 | $25,000 |
| Married filing jointly | $32,000 |
| Married filing separately, lived with your spouse at any time during 2026 | $0 |
Two statuses deserve a closer look. On a joint return you combine both spouses' benefits and both spouses' other income against the single $32,000 base, even if only one of you collects Social Security. And the $0 base for married-filing-separately couples who lived together is not a typo. At that status, some benefits may be taxable at nearly any income level, which is how separated-but-cohabiting couples get blindsided. The base amounts are written into the tax code and have not been indexed for inflation since they were set, which is why more retirees cross them every year.
What counts as "other income" on the worksheet?
Every kind of income counts toward the Notice 703 test except SSI, and that includes tax-exempt interest. That last part is the trap that catches careful savers. Municipal bond interest is untaxed on its own, yet line D adds it to the total that decides whether your Social Security is taxed.
Line C covers the usual list: pension and annuity payments, IRA and 401(k) withdrawals, wages from a part-time job, self-employment earnings, bank and CD interest, dividends, capital gain distributions and rental income. A required minimum distribution counts. A one-time gain from selling stock counts. And the notice says in so many words not to reduce the number by deductions, exclusions or exemptions. It is gross income, before the standard deduction.
What does not count: SSI, and the other half of your benefits. You only ever add one-half of Box 5 on the income side of the test, never the full amount.
How much of your Social Security can be taxed once you cross the line?
Crossing the base amount never makes all of your benefits taxable. Publication 915 sets two tiers. Up to 50 percent of your benefits can be taxable once line E is over $25,000 single or $32,000 joint. Up to 85 percent can be taxable once line E is over $34,000 single or $44,000 joint, or at any level if you are married filing separately and lived with your spouse. The ceiling is 85 percent in every case.
Those percentages describe the most that can be included, not what you will pay. The actual taxable slice ramps up gradually inside each tier, so a retiree a few hundred dollars over the line includes only a few hundred dollars of benefits. The tax on that slice is then figured at ordinary rates, which for many retirees means the 10 or 12 percent bracket after the standard deduction.
How does the math look with $19,000 of Social Security and a $14,000 pension?
For a single retiree with $19,000 of Social Security and a $14,000 pension, line E on Notice 703 is $23,500. That is $1,500 under the $25,000 base amount, so none of the benefits are taxable. Here is the arithmetic, plus two variations that show how fast the answer changes. All three are hypothetical.
Say you are single with $19,000 in Box 5 and a $14,000 pension. Line B is $9,500. Line C is $14,000. Line D is zero. Line E is $9,500 + $14,000 = $23,500. That is under $25,000, so line 6b of your Form 1040 is zero, though you still report the full $19,000 on line 6a.
Now say the same retiree also earned $3,700 of CD interest. Line E becomes $9,500 + $14,000 + $3,700 = $27,200, which is $2,200 over the base. The worksheet's verdict is that some benefits may be taxable. That does not mean you owe tax on $2,200, and it does not mean the whole $19,000 is taxed. Under the Publication 915 formula, the taxable portion in the 50 percent tier is the smaller of half the excess over the base ($1,100) or half your benefits ($9,500), so $1,100 of benefits becomes taxable. In the 12 percent bracket that is about $132 of tax. Small, but the IRS will notice if it is missing.
| Hypothetical scenario | Line E (half of benefits + other income) | Base amount | Worksheet result |
|---|---|---|---|
| Single: $19,000 Social Security + $14,000 pension | $9,500 + $14,000 = $23,500 | $25,000 | Under by $1,500: none taxable |
| Single: same, plus $3,700 CD interest | $9,500 + $17,700 = $27,200 | $25,000 | Over by $2,200: about $1,100 of benefits taxable |
| Married filing jointly: $28,000 combined benefits + $22,000 pension and IRA withdrawals | $14,000 + $22,000 = $36,000 | $32,000 | Over by $4,000: about $2,000 of benefits taxable |
Look at row two. One maturing CD, one IRA withdrawal or one part-time W-2 is often what pushes a retiree over the line for the first time. If it happened this year, it may have happened in earlier years too. More on that below.
What if the worksheet says some benefits may be taxable?
When line E tops the base amount, the Box 5 figure goes on line 6a of Form 1040 or 1040-SR and the taxable portion goes on line 6b. Your software or preparer computes line 6b using the full worksheet. Notice 703 only tells you whether that computation is needed. If you are married filing separately and lived apart from your spouse all year, the notice also tells you to check the box on line 6d.
If you received a lump-sum payment in 2026 that covered earlier years (a back-pay award after a disability approval, for instance), the whole lump goes on line A, which can push line E over the base in a single year. Publication 915 allows a lump-sum election that spreads the earlier-year portion back to the years it was for, and that election often lowers the taxable amount. It is worth running both ways.
If you would rather not meet a surprise balance every April, you have two levers. File Form W-4V with the Social Security Administration to have federal income tax withheld from each monthly check at 7, 10, 12 or 22 percent (those are the only four rates the form allows), or make quarterly estimated payments on your other income. Either approach also protects you from an underpayment penalty on top of the tax. As of the January 2026 revision of the form, you can also request withholding online through your my Social Security account instead of mailing the paper form.
And if you are just under the line, timing matters. Spreading a planned IRA withdrawal across two tax years, instead of taking it all in one, can keep each year's line E below the base amount. That is ordinary planning, because the test runs year by year.
What happens if taxable benefits went unreported for years?
The Social Security Administration reports your Box 5 amount directly to the IRS every year, so a return that leaves lines 6a and 6b blank, or understates them, surfaces through automated document matching. Nothing about that process requires a human to notice you. Here is the sequence when it runs:
- Automated matching. The IRS computer compares the SSA's Box 5 figure against what your return reported. A gap gets queued for the underreporter program, often for more than one year at once.
- CP2000 proposal. A CP2000 notice arrives proposing additional tax on the unreported benefits, plus interest and sometimes an accuracy-related penalty. It is a proposal, not a bill, and it can be answered and corrected.
- Notice of deficiency. Ignore the CP2000 and it hardens into a CP3219A notice of deficiency, your last formal chance to dispute before the amount is assessed.
- Assessed balance and collection notices. Once assessed, the balance accrues interest plus a failure-to-pay penalty of 0.5 percent per month, refunds get offset, and the standard collection notice sequence begins.
- Levy on the benefits themselves. Left unresolved, the IRS can take up to 15 percent of each monthly Social Security payment through the Federal Payment Levy Program. That means collecting the tax on your benefits out of your benefits. Our guide on the IRS taking 15 percent of Social Security covers how that levy starts and stops.
The stages matter more than the speed. The matching, notices and levies above are automated, and they never stopped. The cheapest point to fix an unreported year is before stage two. If you want a rough sense of what penalties and interest have added to an old balance, our IRS penalty and interest calculator can estimate it.
Just realized past years' benefits should have been reported?
Do not wait for the matching notices to price it for you. An experienced tax professional will review the affected years free, tell you what you would actually owe, and map the cleanest way to fix it before interest and penalties grow the number.
What are your options if you already owe on unreported benefits?
An assessed balance from unreported Social Security benefits qualifies for the same IRS resolution programs as any other tax debt, and retirees on fixed incomes often fit the gentler ones.
- Answer the CP2000 first. If the proposal is right but you cannot pay, agreeing and arranging payment beats silence (see CP2000: agree but can't pay). If the IRS's math is wrong, dispute it before it is assessed.
- Short-term plan: up to 180 days to pay in full, with no setup fee. Interest and the monthly penalty continue, and collection stops.
- Installment agreement: balances of $50,000 or less in combined tax, penalties and interest can generally be set up online. On a hypothetical $2,200 CP2000 balance, even a small monthly payment resolves it long before it can escalate.
- Currently Not Collectible: if paying anything would leave you unable to cover basic living expenses, collection can be paused. Our guide for taxpayers who are retired and owe back taxes explains how fixed-income budgets change the math.
- Penalty relief: a clean compliance history for the prior three years supports first-time abatement. The IRS is adding the Automatic Exemption from Penalty (AEP), applied automatically during original return processing to eligible returns processed after it starts; earlier 2025 returns still need that request. Until then, eligible 2024 returns, and 2025 returns processed before AEP starts, still need a first-time abatement request, per IRS fact sheet FS-2026-12.
- Unfiled years: if some years were never filed at all, get current first. Our guide on how many years of back taxes you have to file covers the IRS's standard look-back.
If several years are involved, or a CP91 notice has already warned that your benefits will be levied, a free case review can sequence these options so you fix the cheapest problem first.
How to use SSA Notice 703, step by step
- Find Box 5 on your Form SSA-1099. That is your net Social Security benefits for 2026 and the only SSA-1099 number the worksheet uses. Enter it on line A.
- Take half of it. Multiply line A by 50 percent and write the result on line B.
- Add your other income. Enter all taxable income other than benefits on line C and any tax-exempt interest on line D, with nothing subtracted for deductions.
- Compare line E to your base amount. Add lines B, C and D. Measure the total against $25,000, $32,000 or $0 for your filing status.
- Report the result on Form 1040. Put the Box 5 amount on line 6a and the taxable portion, if any, on line 6b. Under the base amount, line 6b is zero.
- Keep Notice 703 with your records. The notice says in print not to return it to the SSA or the IRS.
Lost the SSA-1099 itself? You can print a replacement from your my Social Security account at the Social Security Administration's website instead of waiting on hold.
Red flags to check before you file the notice away
For most people Notice 703 is a quick check. These are the signs it deserves more of your time:
- Your filing status is married filing separately and you lived with your spouse at any time in the year, so your base amount is $0.
- You took a one-time IRA withdrawal, cashed a maturing CD or sold stock at a gain this year.
- You hold municipal bonds and left their interest off line D.
- You received a lump-sum back payment in 2026 for earlier years and have not looked at the lump-sum election.
- Earlier returns left lines 6a and 6b blank in years your total was over the base amount.
- A CP2000 has arrived proposing tax on unreported benefits, or a CP11 notice says the IRS recomputed your taxable benefits.
- Your monthly benefit is already smaller because of a levy.
Can you handle Notice 703 yourself?
Most people can finish Notice 703 in five minutes with no help at all. If line E lands under the base amount, you are done. Report line 6a, put zero on 6b, and file the notice away. If you are modestly over the line for the current year, any mainstream tax software or a free VITA or AARP volunteer preparer will compute line 6b correctly. None of that requires a tax-relief firm, and anyone who tells a comfortably-under-the-line retiree otherwise is selling something.
Experienced help changes the outcome in fewer cases. Think of multiple past years of unreported benefits, a CP2000 or notice of deficiency already in hand, a levy already taking a slice of your monthly check, or a balance you cannot pay on a fixed income. Then the order of operations matters: dispute or agree, file or amend, penalty relief before a payment plan. It changes the final number, and getting it wrong is expensive to unwind. Our pricing page spells out what a review of several years costs before you commit to anything.
What do the terms on your notice mean?
- Box 5 (net benefits): the total Social Security benefits paid to you for the year, after adjustments. It is the only SSA-1099 number the worksheet uses.
- Base amount: the filing-status threshold ($25,000, $32,000 or $0) that line E is measured against.
- Combined income: the informal name for line E: half your benefits plus all other income, including tax-exempt interest.
- Tax-exempt interest: interest, usually from municipal bonds, that is not taxed itself but still counts on line D.
- SSI: Supplemental Security Income, a needs-based payment that is not taxable and is excluded from the worksheet entirely.
- Lines 6a and 6b: the Form 1040 lines for your total benefits (6a) and the taxable portion (6b).
- Lump-sum election: the Publication 915 method for taxing a back payment as if it had been received in the years it covered.
SSA Notice 703 questions, answered
What is SSA Notice 703?
SSA Notice 703 is an IRS worksheet, titled "Read This To See if Your Social Security Benefits May Be Taxable," that the Social Security Administration mails with every Form SSA-1099. It runs one test: half of your benefits plus all your other income, including tax-exempt interest, compared with the base amount for your filing status. It is a math check, never a bill, and the current revision is dated November 2026.
Do I have to send Notice 703 back to the IRS or the SSA?
No. The notice says in print, "Do not return this notice to the SSA or the IRS. Keep it with your records." Fill it out, keep it with your tax papers, and use the result when you complete lines 6a and 6b of your Form 1040 or 1040-SR. There is no response deadline and no penalty attached to the notice itself.
How much of my Social Security can be taxed?
At most 85 percent, and often much less. Up to 50 percent of your benefits can be taxable once half your benefits plus other income tops $25,000 (single) or $32,000 (joint). Up to 85 percent can be taxable once that total tops $34,000 single or $44,000 joint. The taxable share ramps up gradually inside each tier, so a retiree a few hundred dollars over the line includes only a few hundred dollars of benefits.
Does Notice 703 apply to survivor and SSDI benefits?
Yes. Social Security benefits for this test include monthly retirement, survivor and disability (SSDI) benefits. All of them show up in Box 5 of an SSA-1099 and run through the same worksheet. Only SSI is excluded. If SSDI is your sole income, half of it alone rarely tops the $25,000 single base amount, so many SSDI-only recipients owe nothing.
Where do Social Security benefits go on Form 1040?
The full amount from Box 5 of your SSA-1099 goes on line 6a of Form 1040 or 1040-SR, and the taxable portion goes on line 6b. If none of your benefits are taxable, line 6b is zero, but you still report the Box 5 total on line 6a so your return matches what the SSA reported to the IRS. Married-filing-separately filers who lived apart from their spouse all year also check the box on line 6d.
Can I have tax withheld from my Social Security check instead of paying in April?
Yes. File Form W-4V with the Social Security Administration, not the IRS, and choose 7, 10, 12 or 22 percent to be withheld from each payment. Those are the only four rates the form allows. The January 2026 form also points to the online request in your my Social Security account. Withholding is voluntary and you can change or stop it with a new form at any time.
What if I got a lump-sum Social Security payment for earlier years?
Enter the whole lump sum on line A for the year you received it, because that is how the SSA reports it in Box 5. Then look at the lump-sum election in Publication 915, which lets you figure the taxable amount as if the earlier-year portion had been received in those years. The election often lowers the total, especially when your income in the earlier years was below the base amount.
Bottom line
Notice 703 is a worksheet that comes with your SSA-1099. Add half of Box 5 to all your other income, tax-exempt interest included, and compare the total with the base amount for your filing status. Under it, report line 6a and put zero on 6b. Over it, let the full worksheet or your software figure line 6b, consider W-4V withholding for next year, and look back at earlier years too.
Your next 24 hours
- Find Box 5 on your SSA-1099 and write down half of it. That single number is the starting point of the whole Notice 703 test.
- Gather last year's Form 1040 and your other income documents, such as a 1099-R for the pension or IRA, a 1099-INT for interest (including tax-exempt), and any W-2, and run the five-line comparison against your base amount.
- If the math shows past years over the base amount that never made it onto a return, get a free case review through the 2-minute form at claritytaxrelief.com/#consult or (888) 825-7779. There is no deadline on the notice itself, but interest on any real balance compounds every month it waits.
Primary sources, checked November 4, 2026: the IRS's Notice 703 (Rev. November 2026), Publication 915, Social Security and Equivalent Railroad Retirement Benefits (the full worksheet that computes the exact taxable amount), Form W-4V, Voluntary Withholding Request, and IRS.gov/payments if a balance from a prior year needs paying.
This guide is general information, not tax or legal advice for your specific situation. Eligibility for IRS programs depends on individual facts and circumstances; no outcome is guaranteed.